


Spain
Highlights for the period January - September 2026
- Lending dynamism continues, driven by corporate and consumer lending
- Favorable performance of net interest income
- The NPL ratio remains at historical lows
- Year-on-year stability in net attributable profit, with a decrease in the third quarter
BUSINESS ACTIVITY (1)
(VARIATION COMPARED TO 31-12-25)
(1) Excluding repos.
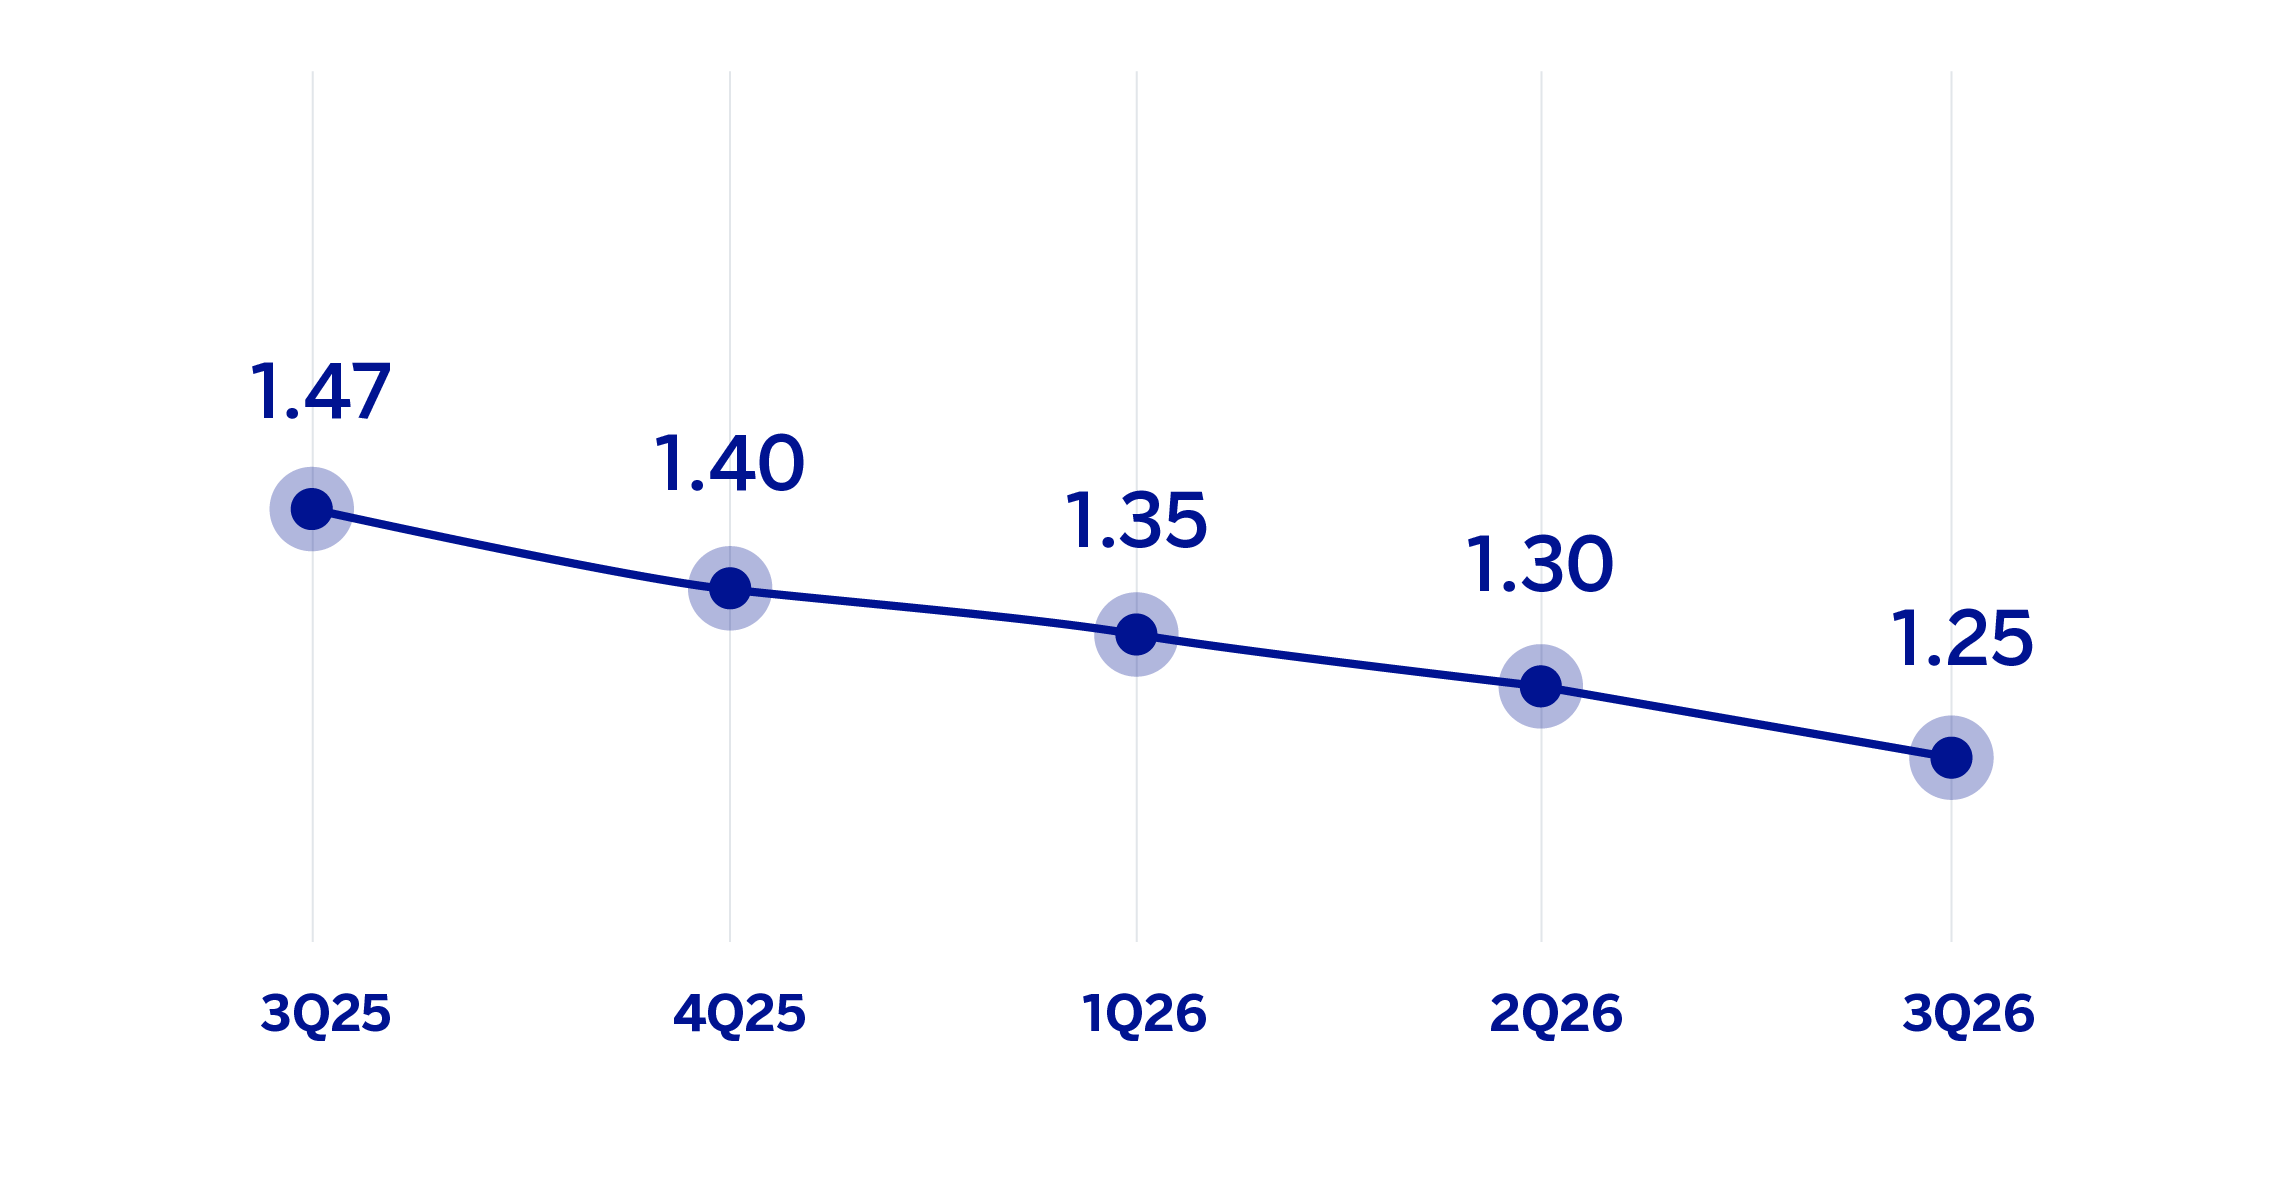
NET INTEREST INCOME / AVERAGE TOTAL ASSETS
(PERCENTAGE)
OPERATING INCOME (MILLIONS OF EUROS)
NET ATTRIBUTABLE PROFIT (LOSS) (MILLIONS OF EUROS)
| FINANCIAL STATEMENTS AND RELEVANT BUSINESS INDICATORS (MILLIONS OF EUROS AND PERCENTAGE) | |||
|---|---|---|---|
| Income statement | Jan.-Sep.26 | 𝚫 % | Jan.-Sep.25 (1) |
| Net interest income | 5,055 | 3.4 | 4,886 |
| Net fees and commissions | 1,770 | 2.3 | 1,731 |
| Net trading income | 494 | (7.0) | 531 |
| Other operating income and expenses | 283 | (2.0) | 289 |
| Of which: Insurance activities | 316 | 5.7 | 299 |
| Gross income | 7,601 | 2.2 | 7,436 |
| Operating expenses | (2,603) | 7.7 | (2,418) |
| Personnel expenses | (1,418) | 8.0 | (1,312) |
| Other administrative expenses | (876) | 6.9 | (820) |
| Depreciation | (309) | 8.2 | (285) |
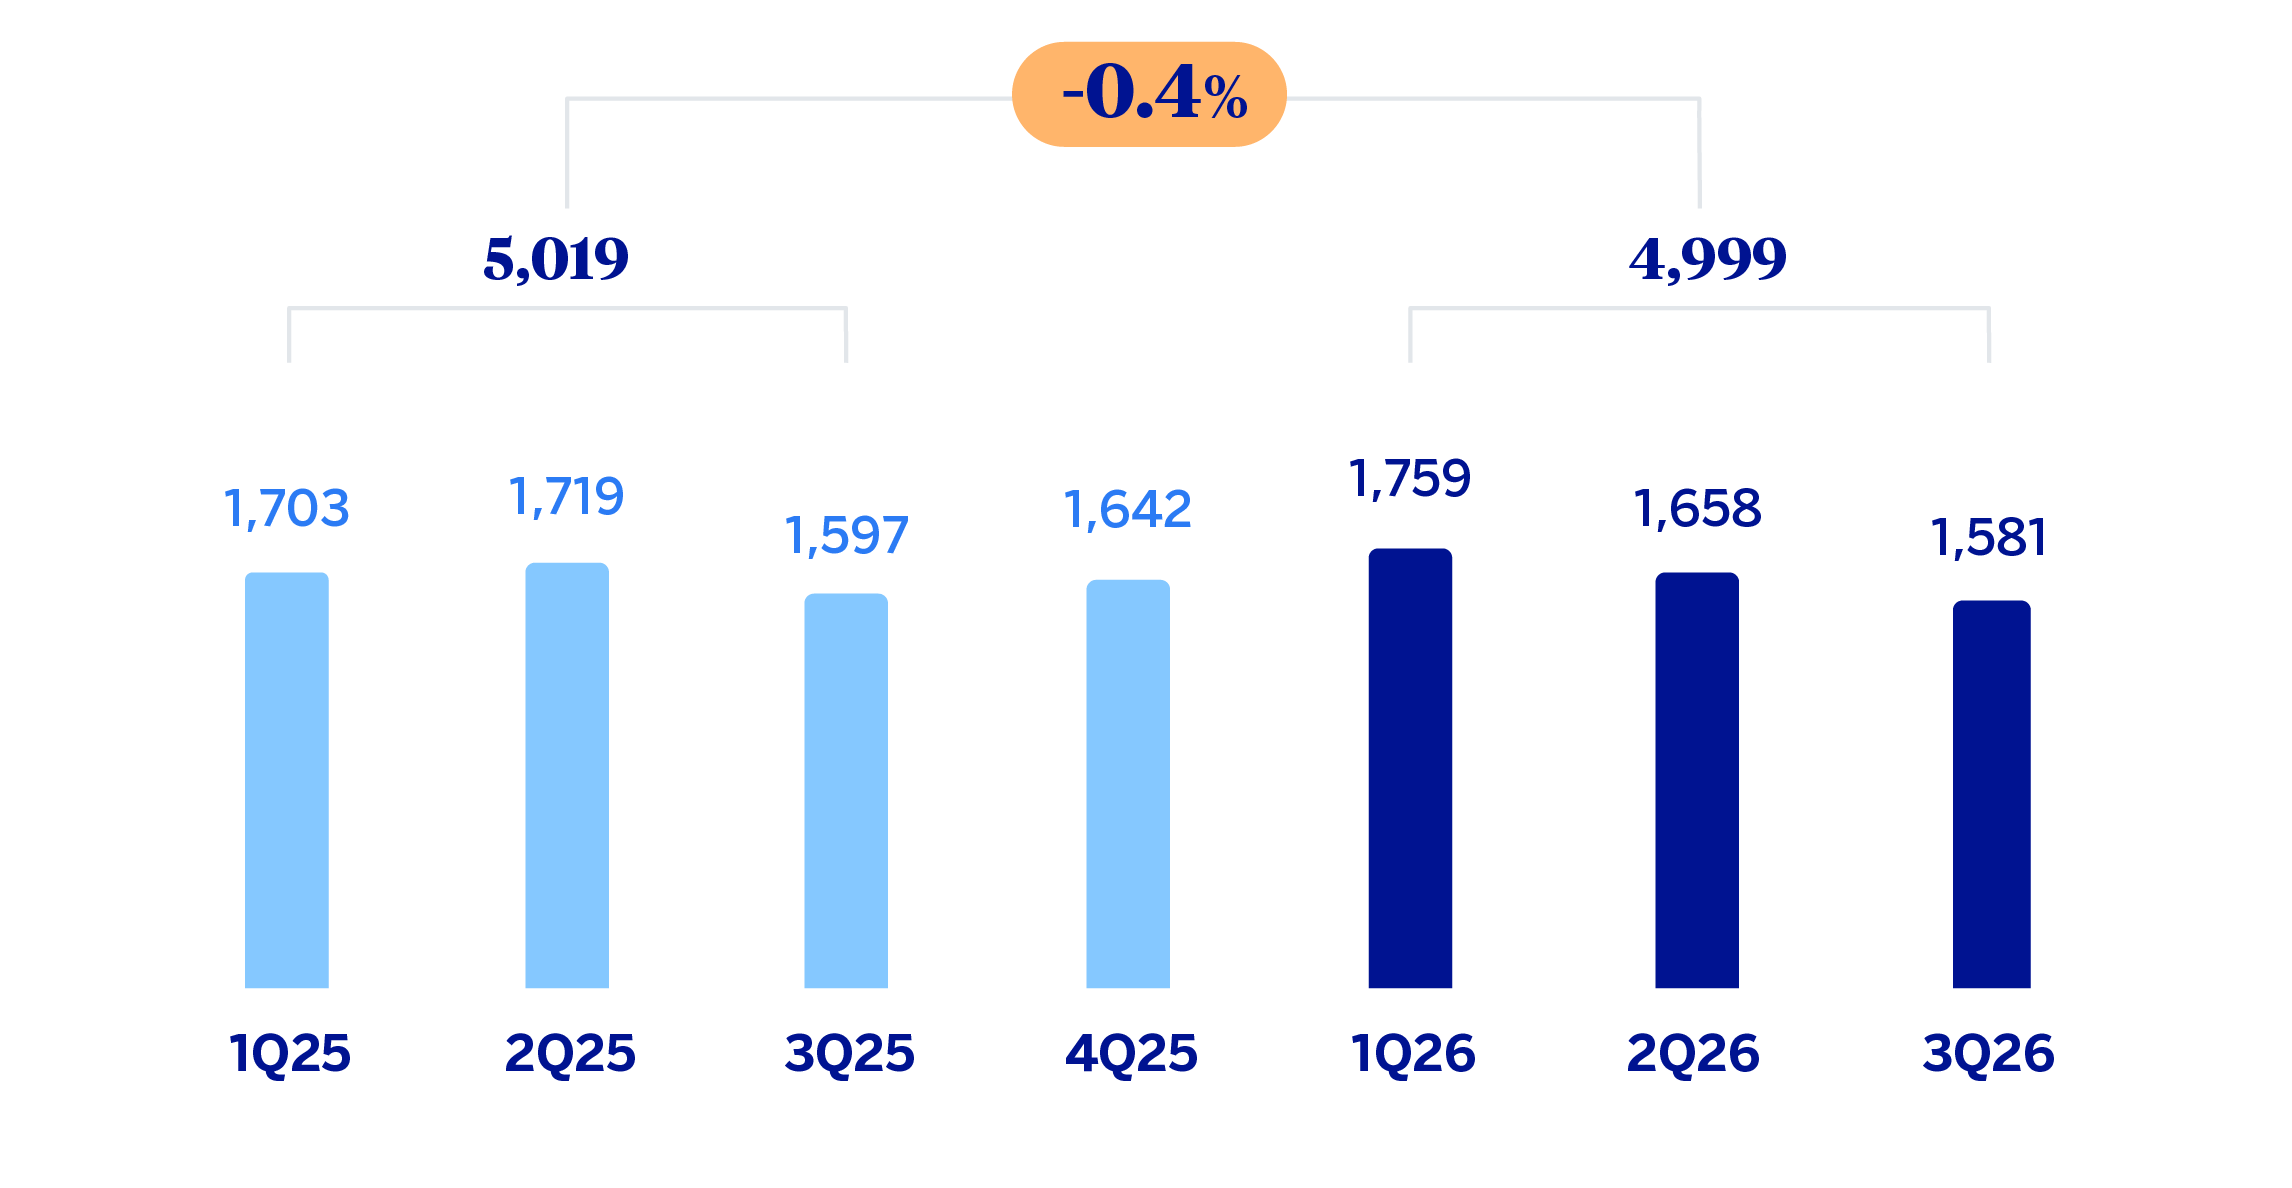
| Operating income | 4,999 | (0.4) | 5,019 |
| Impairment on financial assets not measured at fair value through profit or loss | (491) | 2.8 | (478) |
| Provisions or reversal of provisions and other results | (73) | 37.9 | (53) |
| Profit (loss) before tax | 4,435 | (1.2) | 4,488 |
| Income tax | (1,326) | (3.5) | (1,375) |
| Profit (loss) for the period | 3,108 | (0.2) | 3,113 |
| Non-controlling interests | (2) | 8.8 | (2) |
| Net attributable profit (loss) | 3,106 | (0.2) | 3,111 |
| Balance sheets | 30-09-26 | 𝚫 % | 31-12-25 (1) |
| Cash, cash balances at central banks and other demand deposits | 12,824 | (35.6) | 19,929 |
| Financial assets designated at fair value | 147,495 | 23.0 | 119,910 |
| Of which: Loans and advances | 63,993 | 47.6 | 43,346 |
| Financial assets at amortized cost | 280,601 | 6.5 | 263,437 |
| Of which: Loans and advances to customers | 201,581 | 4.5 | 192,959 |
| Inter-area positions | 89,978 | 86.3 | 48,288 |
| Tangible assets | 2,696 | (0.8) | 2,718 |
| Other assets | 3,637 | (4.5) | 3,808 |
| Total assets/liabilities and equity | 537,231 | 17.3 | 458,090 |
| Financial liabilities held for trading and designated at fair value through profit or loss | 115,554 | 39.6 | 82,785 |
| Deposits from central banks and credit institutions | 40,131 | 16.0 | 34,582 |
| Deposits from customers | 262,293 | 4.3 | 251,430 |
| Debt certificates issued | 81,849 | 53.6 | 53,300 |
| Inter-area positions | — | — | — |
| Other liabilities | 21,500 | 3.3 | 20,822 |
| Allocated regulatory capital | 15,904 | 4.8 | 15,171 |
| Relevant business indicators | 30-09-26 | 𝚫 % | 31-12-25 |
| Performing loans and advances to customers under management (2) | 199,892 | 4.7 | 190,943 |
| Non-performing loans | 6,672 | (1.3) | 6,759 |
| Customer deposits under management (1)(2) | 243,070 | 1.9 | 238,447 |
| Off-balance sheet funds (1)(3) | 127,350 | 6.5 | 119,535 |
| Risk-weighted assets (1) | 121,532 | 1.5 | 119,734 |
| RORWA (4) | 3.5 | 3.4 | |
| Efficiency ratio (%) | 34.2 | 33.3 | |
| NPL ratio (%) | 2.9 | 3.0 | |
| NPL coverage ratio (%) | 72 | 67 | |
| Cost of risk (%) | 0.33 | 0.34 | |
| (1) Revised balances. For more information, please refer to the “Business Areas” section. (2) Excluding repos. (3) Includes mutual funds, customer portfolios and pension funds. (4) For more information on the calculation methodology, as well as the calculation of the metric at the consolidated Group level, see Alternative Performance Measures at this report. |
|||
Macro and industry trends
Economic activity maintained a favorable tone in the second quarter of 2026, and forward-looking expectations remain positive. The strength of domestic demand, supported by private consumption and investment; job creation; and the dynamism of service exports are expected to offset, to some extent, the effects of higher commodity costs, a more restrictive monetary policy, and bottlenecks in sectors such as housing or energy. In this context, BBVA Research forecasts a GDP growth of 2.6% for 2026, two-tenths of a percentage point above the previous scenario's forecast, and a progressive moderation toward growth of 2.1% in 2027.
For its part, inflation increased sharply during the third quarter of the year, with the headline inflation rate reaching 4.9% in September, driven by rising fuel and package holiday prices. Going forward, a gradual correction is expected toward levels of 4% by year-end, which would leave the annual average for 2026 at 3.7%, and place that of 2027 at 3.2%, albeit with figures below that level in the final months of the year.
Regarding the banking sector, as of August 2026, the volume of lending to the private sector grew by 3.4% year-on-year (4.6% excluding the consumer loan portfolio for other purposes, which underwent a methodological change in April 2026 by the Bank of Spain), with a growth of 2.9% in the household loan portfolio (+5.2% excluding consumer loans for other purposes) and 4.4% in lending to non-financial corporations. Deposits from the non-financial sector increased by 1.6% year-on-year in August 2026, with a negative contribution from public sector demand deposits (-15.4%). Interest rate hikes have accelerated the growth of time deposit balances, which represent 14.9% of the total balance, to 9.0% year-on-year in August, compared to the 0.4% growth in demand deposits. The NPL ratio stood at 2.51% in July 2026, 41 basis points below the figure for July of the previous year. Additionally, the system maintains comfortable solvency and liquidity levels.
Activity
The most relevant aspects related to the area's activity during the first nine months of 2026 were:
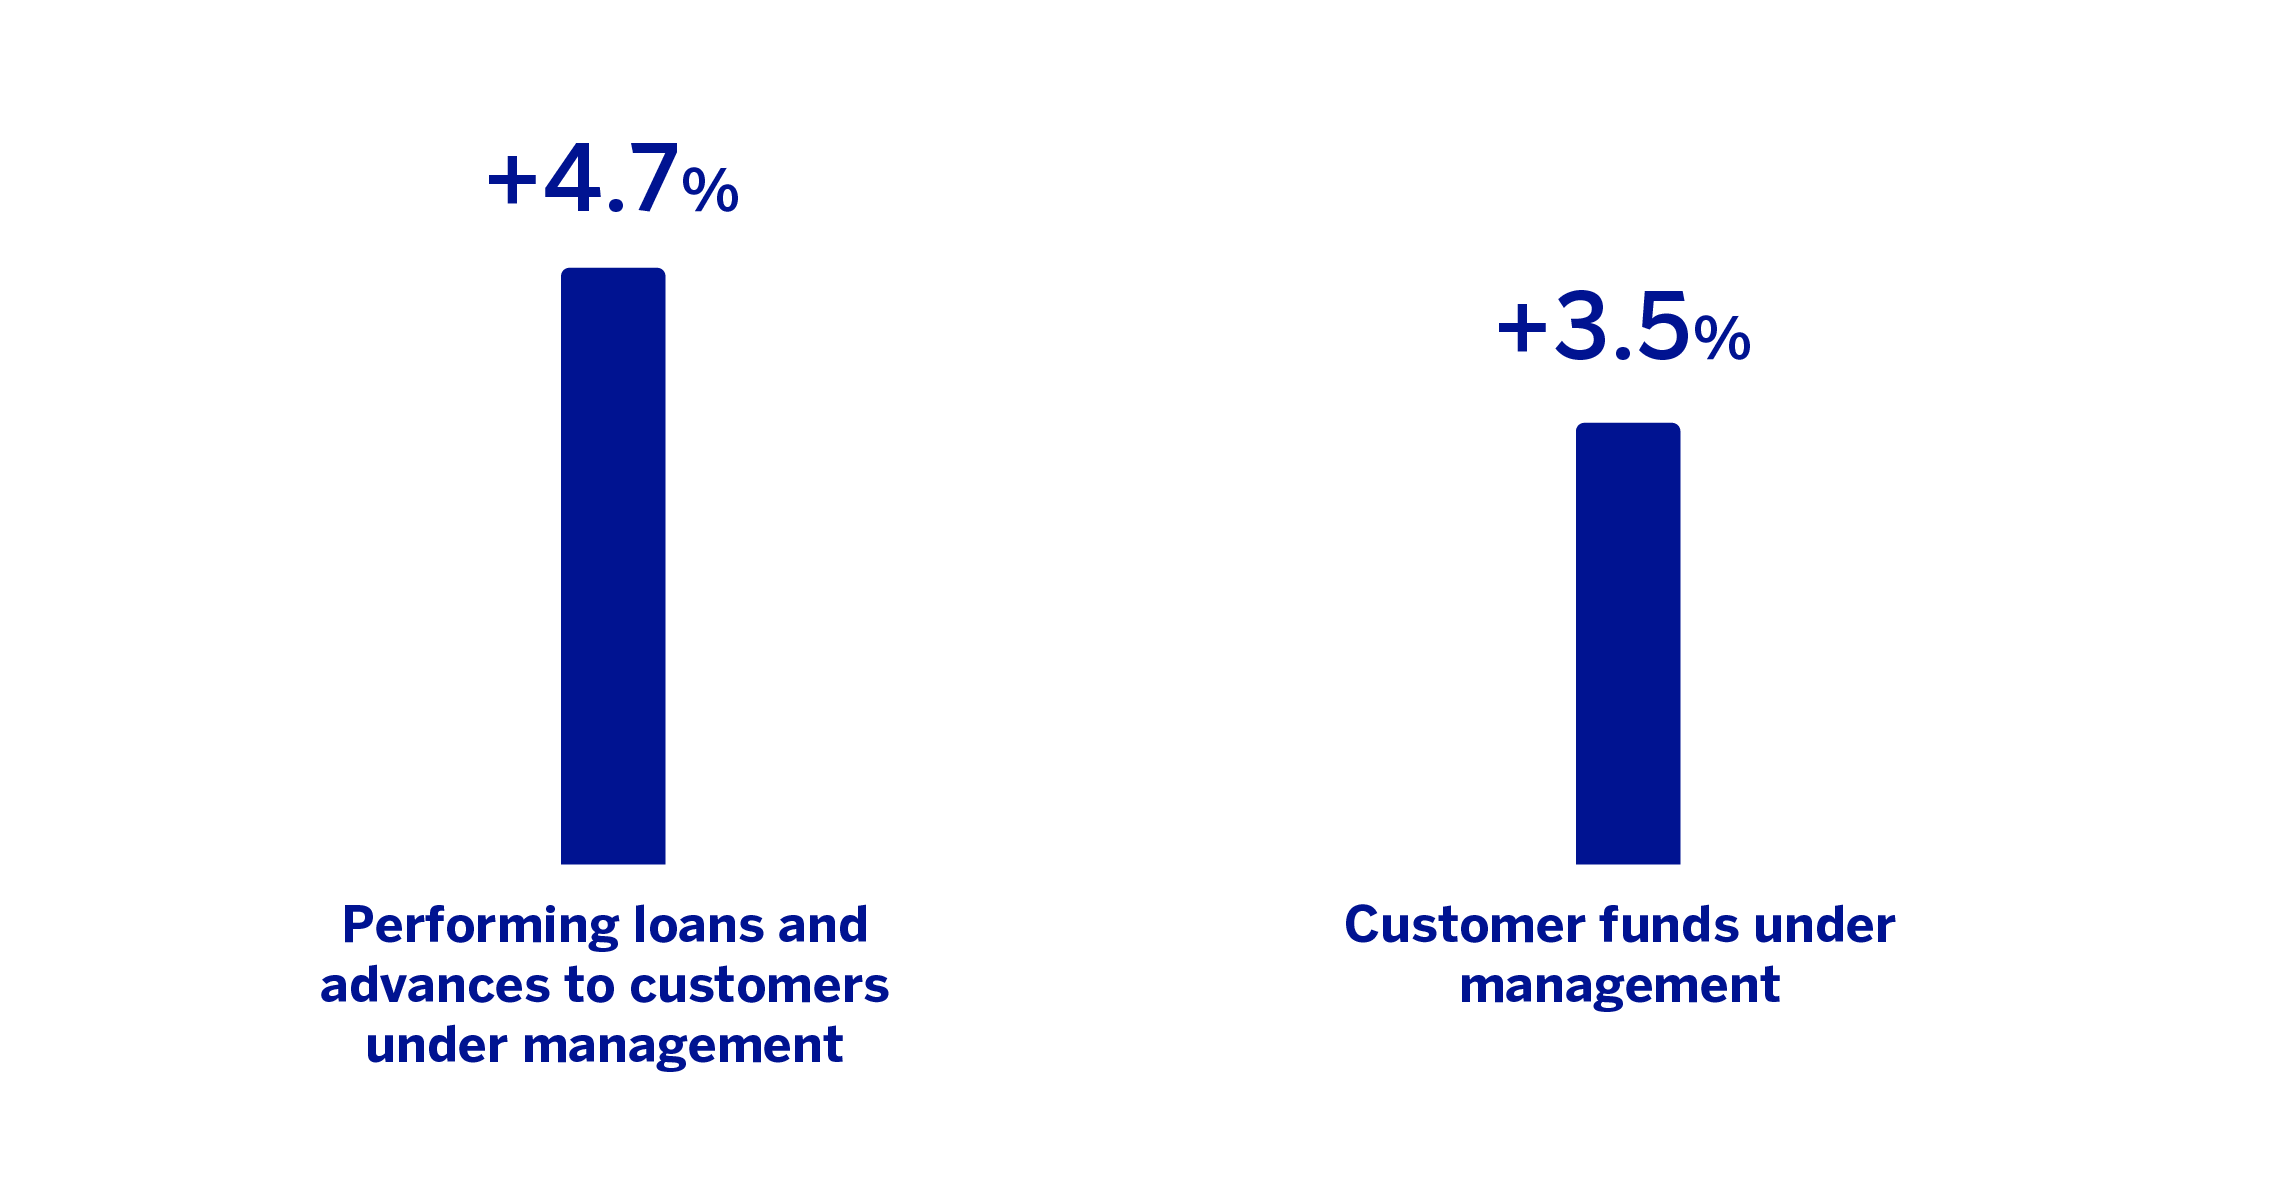
Lending balances were 4.7% higher than at the end of December 2025, mainly driven by the performance of the larger corporate segments (+7.4%) and consumer lending (+7.5%).
Total customer funds increased by 3.5%, mainly explained by the growth in off-balance sheet funds (mutual and pension funds), which increased by 6.5% due to the positive market effect concentrated in the first half of the year and, to a lesser extent, by the favorable performance of customer deposits (+1.9%).
The most relevant aspects related to the area's activity during the third quarter of 2026 were:
Lending activity remained stable (+0.2% compared to the end of June 2026), mainly driven by the dynamism of credit to companies (+3.9% larger companies and +2.5% SMEs), which, together with the rest of the portfolios, offset the seasonal decline in public sector loans (which as of the end of June included the advance on extra payments to pensioners).
Regarding asset quality, the NPL ratio stood at 2.9%, an increase of 4 basis points compared to the end of June and a contained increase in the non-performing balance (+1.2%). The NPL ratio shows a cumulative decrease of 15 basis points throughout 2026. For its part, the NPL coverage ratio increased by 116 basis points in the quarter, to 72% at the end of September 2026.
Total customer funds grew by 0.9% in the third quarter of 2026, favored by the evolution of time deposits which presented a growth of 15.3%, driven by the performance of wholesale balances. Off-balance sheet funds showed stability compared to the end of the previous quarter at 0.6%.
Results
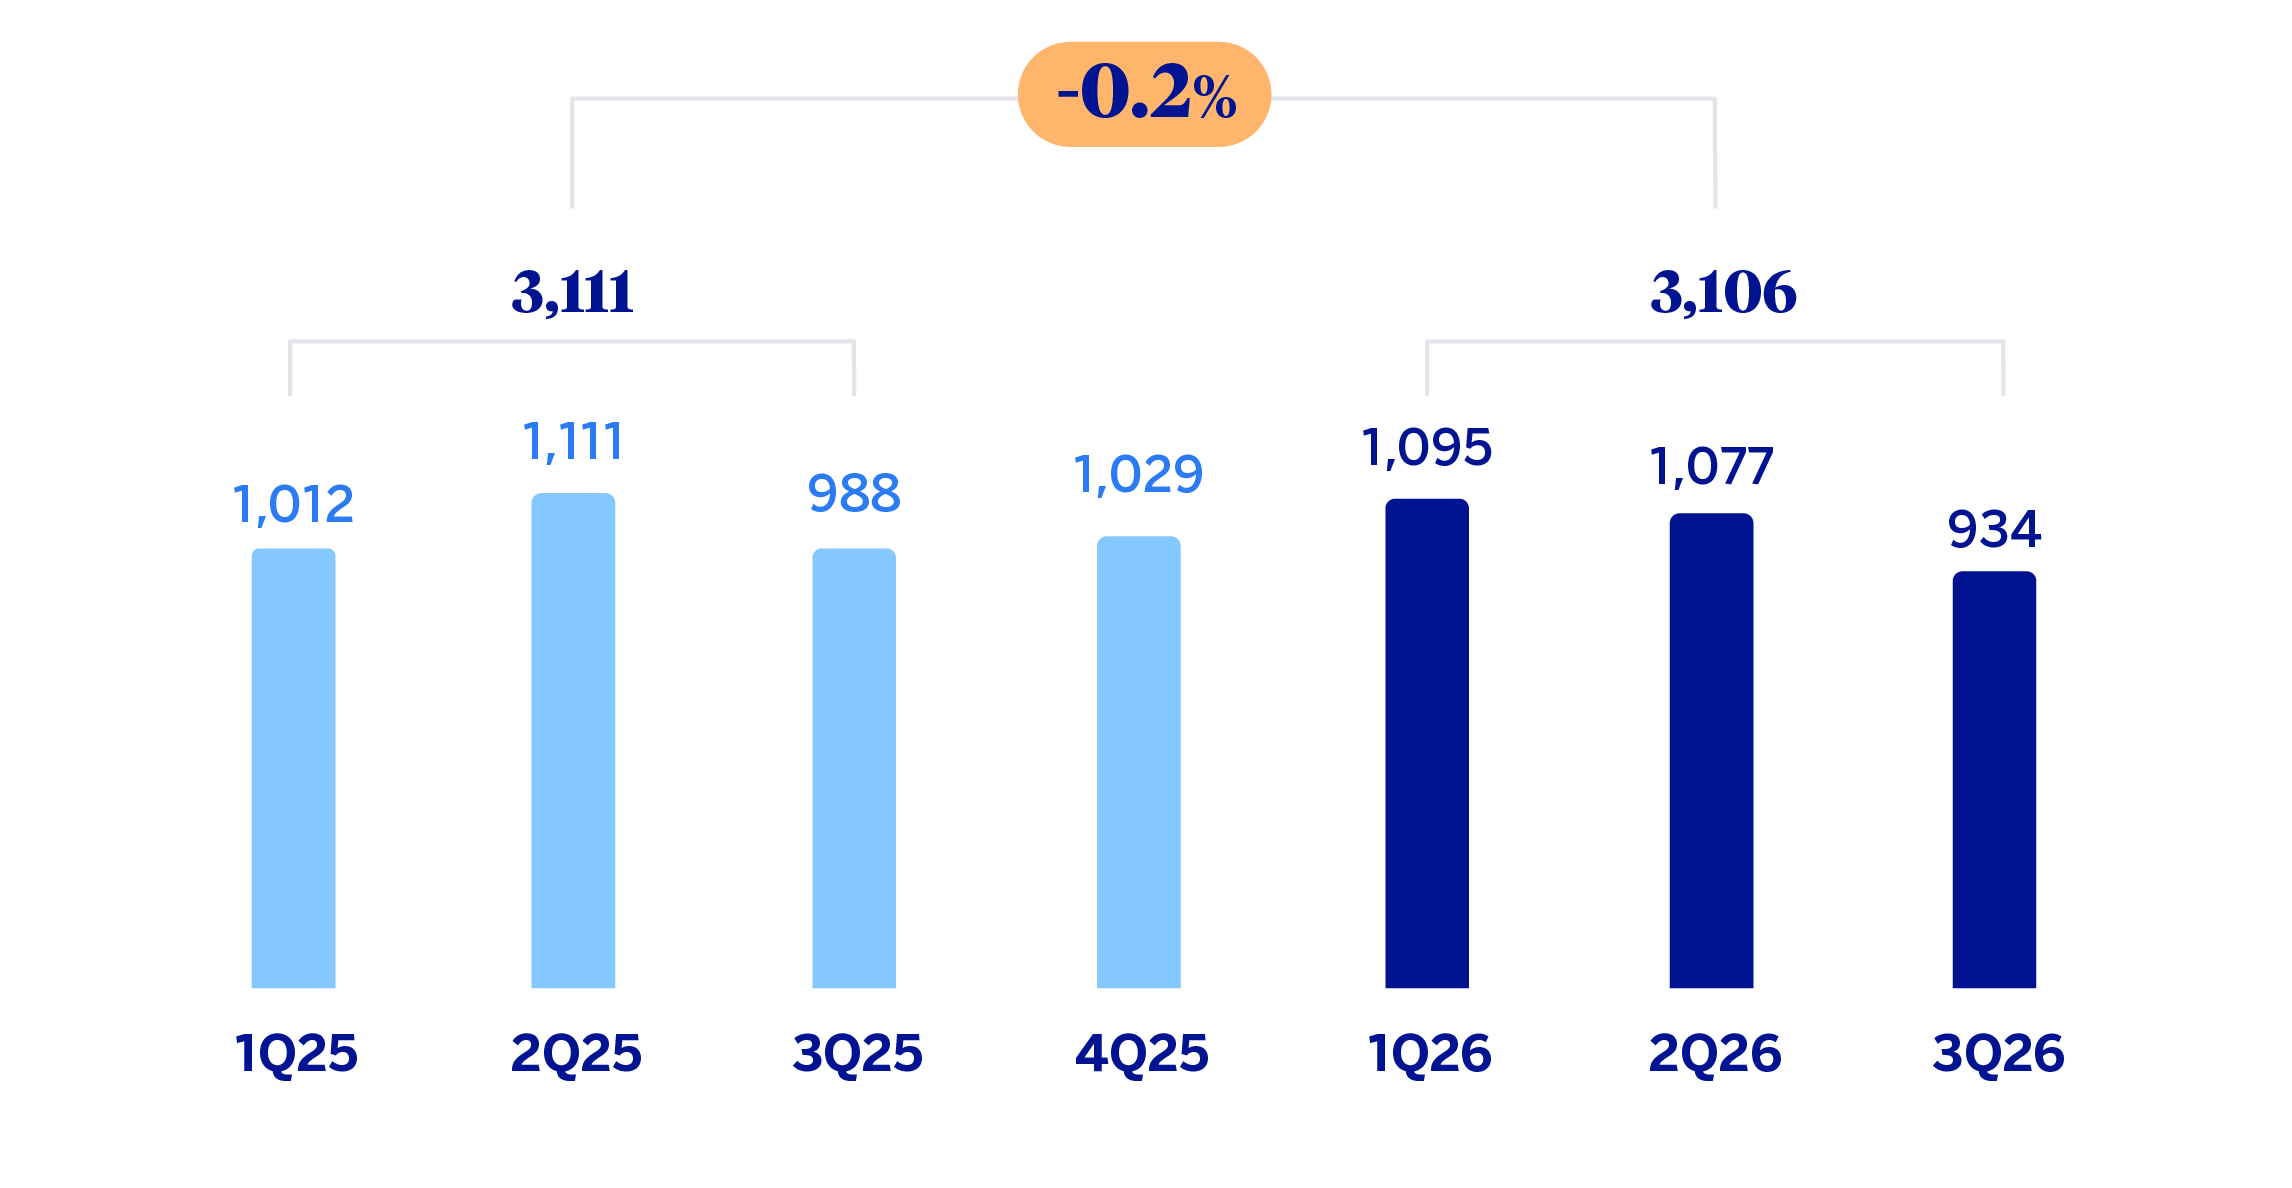
Spain generated a net attributable profit of €3,106 million in the first nine months of 2026, which is in line with that achieved in the same period of 2025 (-0.2%) favored by the good performance of net interest income, which offset the growth in expenses and provisions for financial asset impairments.
The most relevant aspects of the year-on-year evolution of the area's income statement at the end of September 2026 were:
Net interest income grew by 3.4%, supported by higher lending balances and a higher contribution from the securities portfolio.
Net fees and commissions grew by 2.3% compared to the same period of the previous year, mainly driven by the performance of asset management fees.
Net Trading Income (NTI) showed a decrease of 7.0% compared to the first nine months of the previous year, with lower results achieved by the Global Markets unit.
The other operating income and expenses line showed a balance of €283m, which is 2.0% lower than in the same period of the previous year, as the first nine months of 2025 included extraordinary income associated with the achievement of certain milestones foreseen in the Allianz bancassurance agreement, recorded at the end of June of that year. Aside from the factors mentioned above, earnings from the insurance business performed well.
Operating expenses increased by 7.7% compared to the cumulative figures for the first nine months of 2025, due to both higher general expenses (mainly in technology) and personnel expenses, the latter reflecting the impact of voluntary redundancies in the first quarter of 2026. Both periods include, in the general expenses line, the impact of re-estimation of the applied pro-rata on the Value Added Tax.
The impairment on financial assets increased compared to the first nine months of the previous year (+2.8%), mainly as a result of the growth in the volume of lending. Meanwhile, the cumulative cost of risk at the end of September 2026 rose by 2 basis points compared to the previous quarter to stand at 0.33%, remaining practically stable compared to the end of the previous year (a decrease of 1 basis point), mainly because the second quarter was positively affected by a portfolio sale.
Finally, the income tax line includes the accrual corresponding to the first nine months of 2026, of the tax on net interest income and net fees and commissions which stood at approximately €225 million, compared to the €224 million accrued in the same period of the previous year.
The net attributable profit generated by Spain in the third quarter of 2026 reached €934m, with a decrease of 13.3% compared to the previous quarter. This performance is due to a lower contribution from all of gross income components except net interest income, together with an increase in provisions for financial assets (the previous quarter included the positive impact coming from a portfolio sale) and higher operating expenses.
Read legal disclaimer of this report.