


South America
Highlights for the period January - September 2026
- Growth in lending activity, with stronger momentum in the commercial portfolio
- Favorable evolution of recurring revenues in Argentina, Colombia and Peru
- Greater adjustment for hyperinflation compared to the first nine months of 2025
- Year-on-year increase in the area's net attributable profit, with higher contribution from Colombia
BUSINESS ACTIVITY (1) (VARIATION AT CONSTANT EXCHANGE RATES COMPARED TO 31-12-25)
(1) Excluding repos.
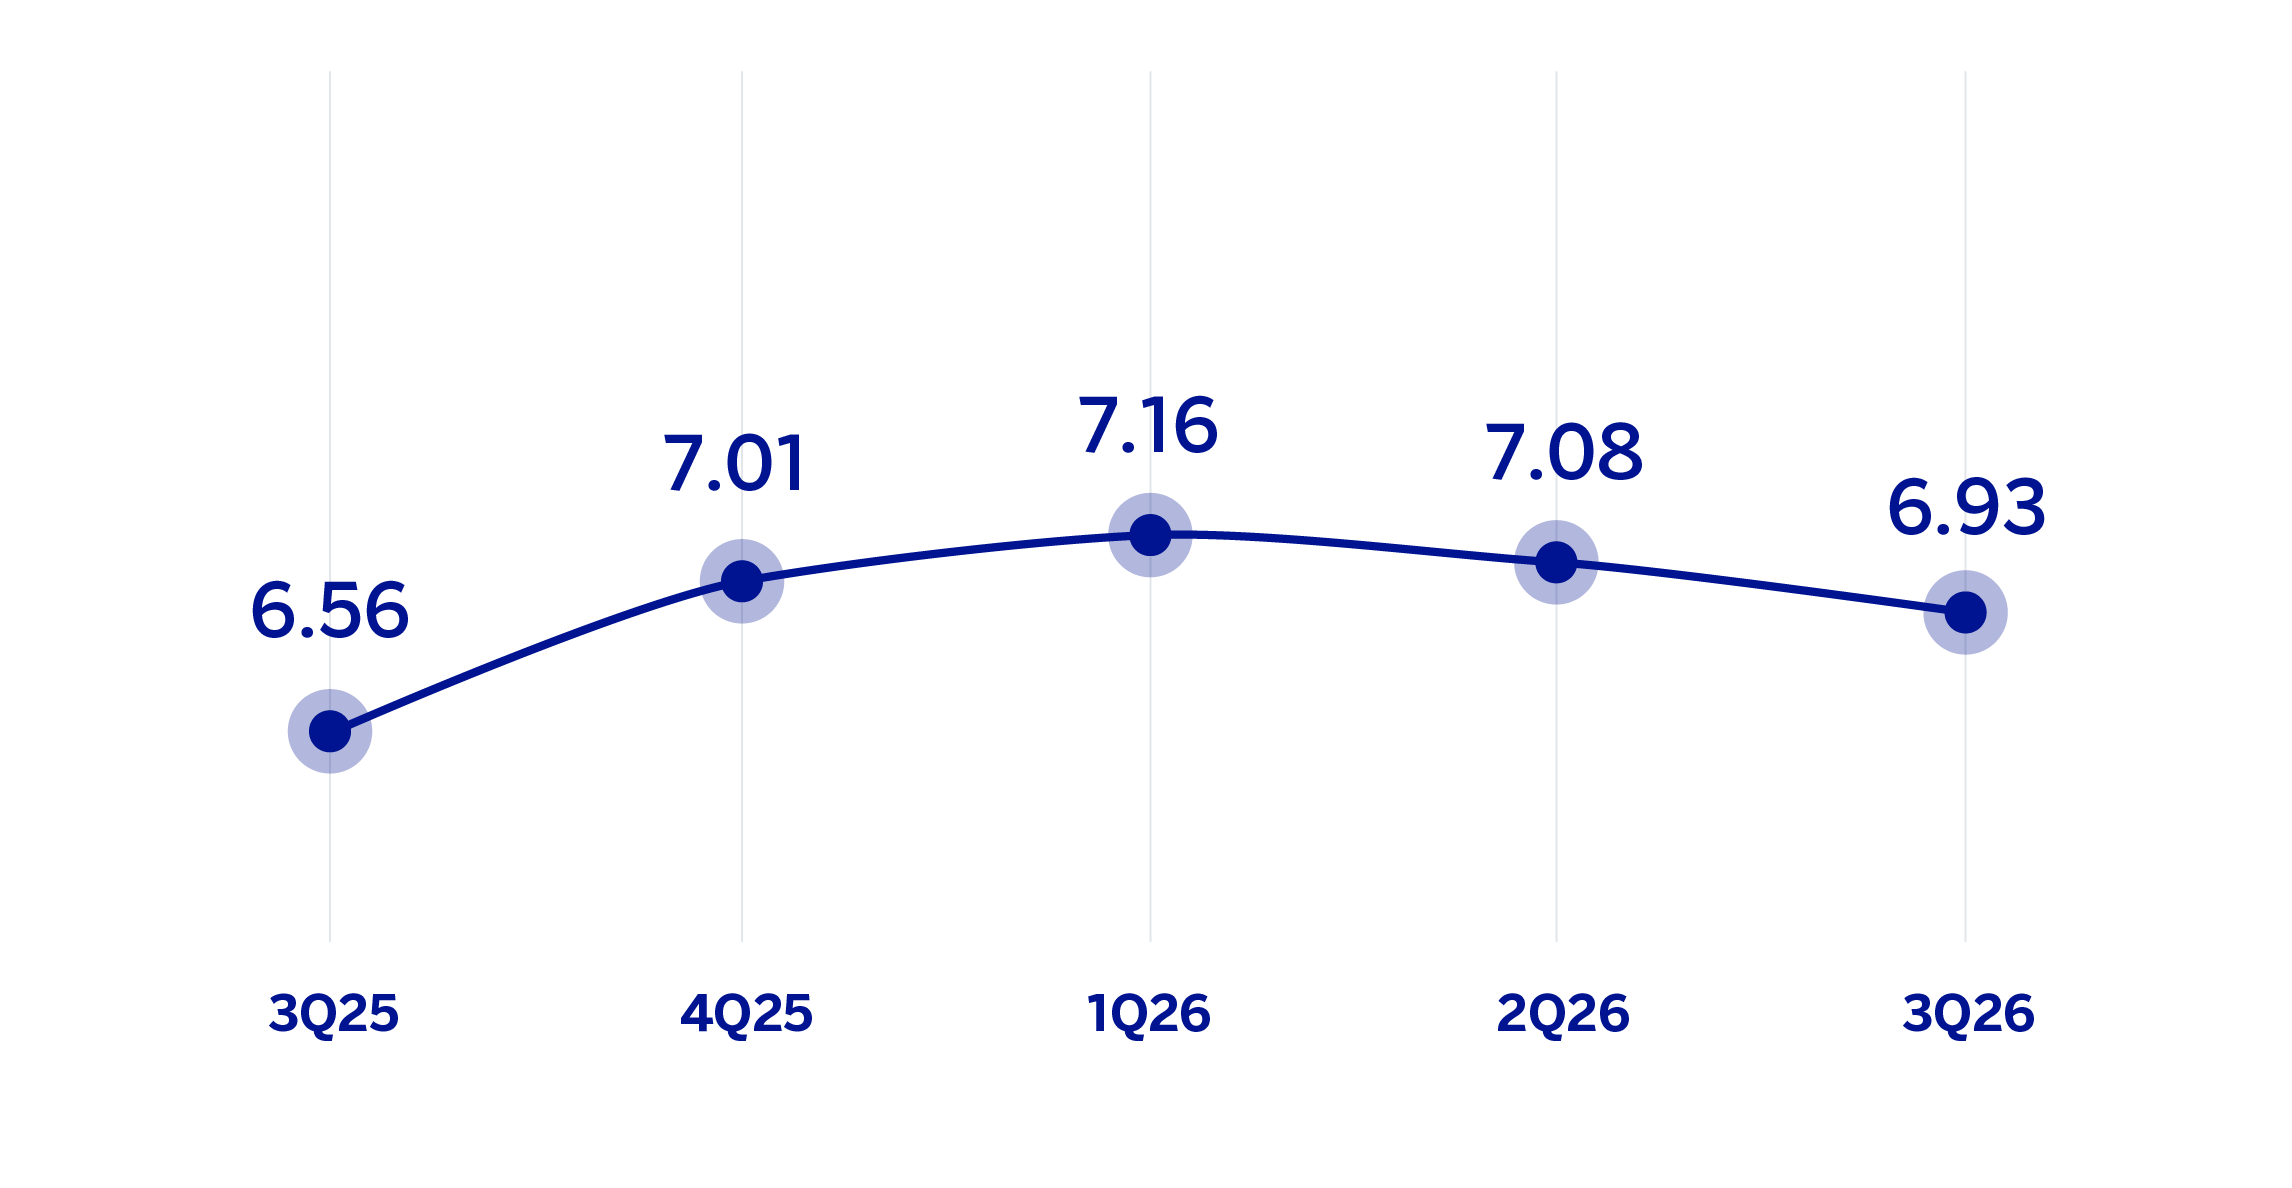
NET INTEREST INCOME / AVERAGE TOTAL ASSETS
(PERCENTAGE AT CONSTANT EXCHANGE RATES)
OPERATING INCOME
(MILLIONS OF EUROS AT CURRENT EXCHANGE RATES)
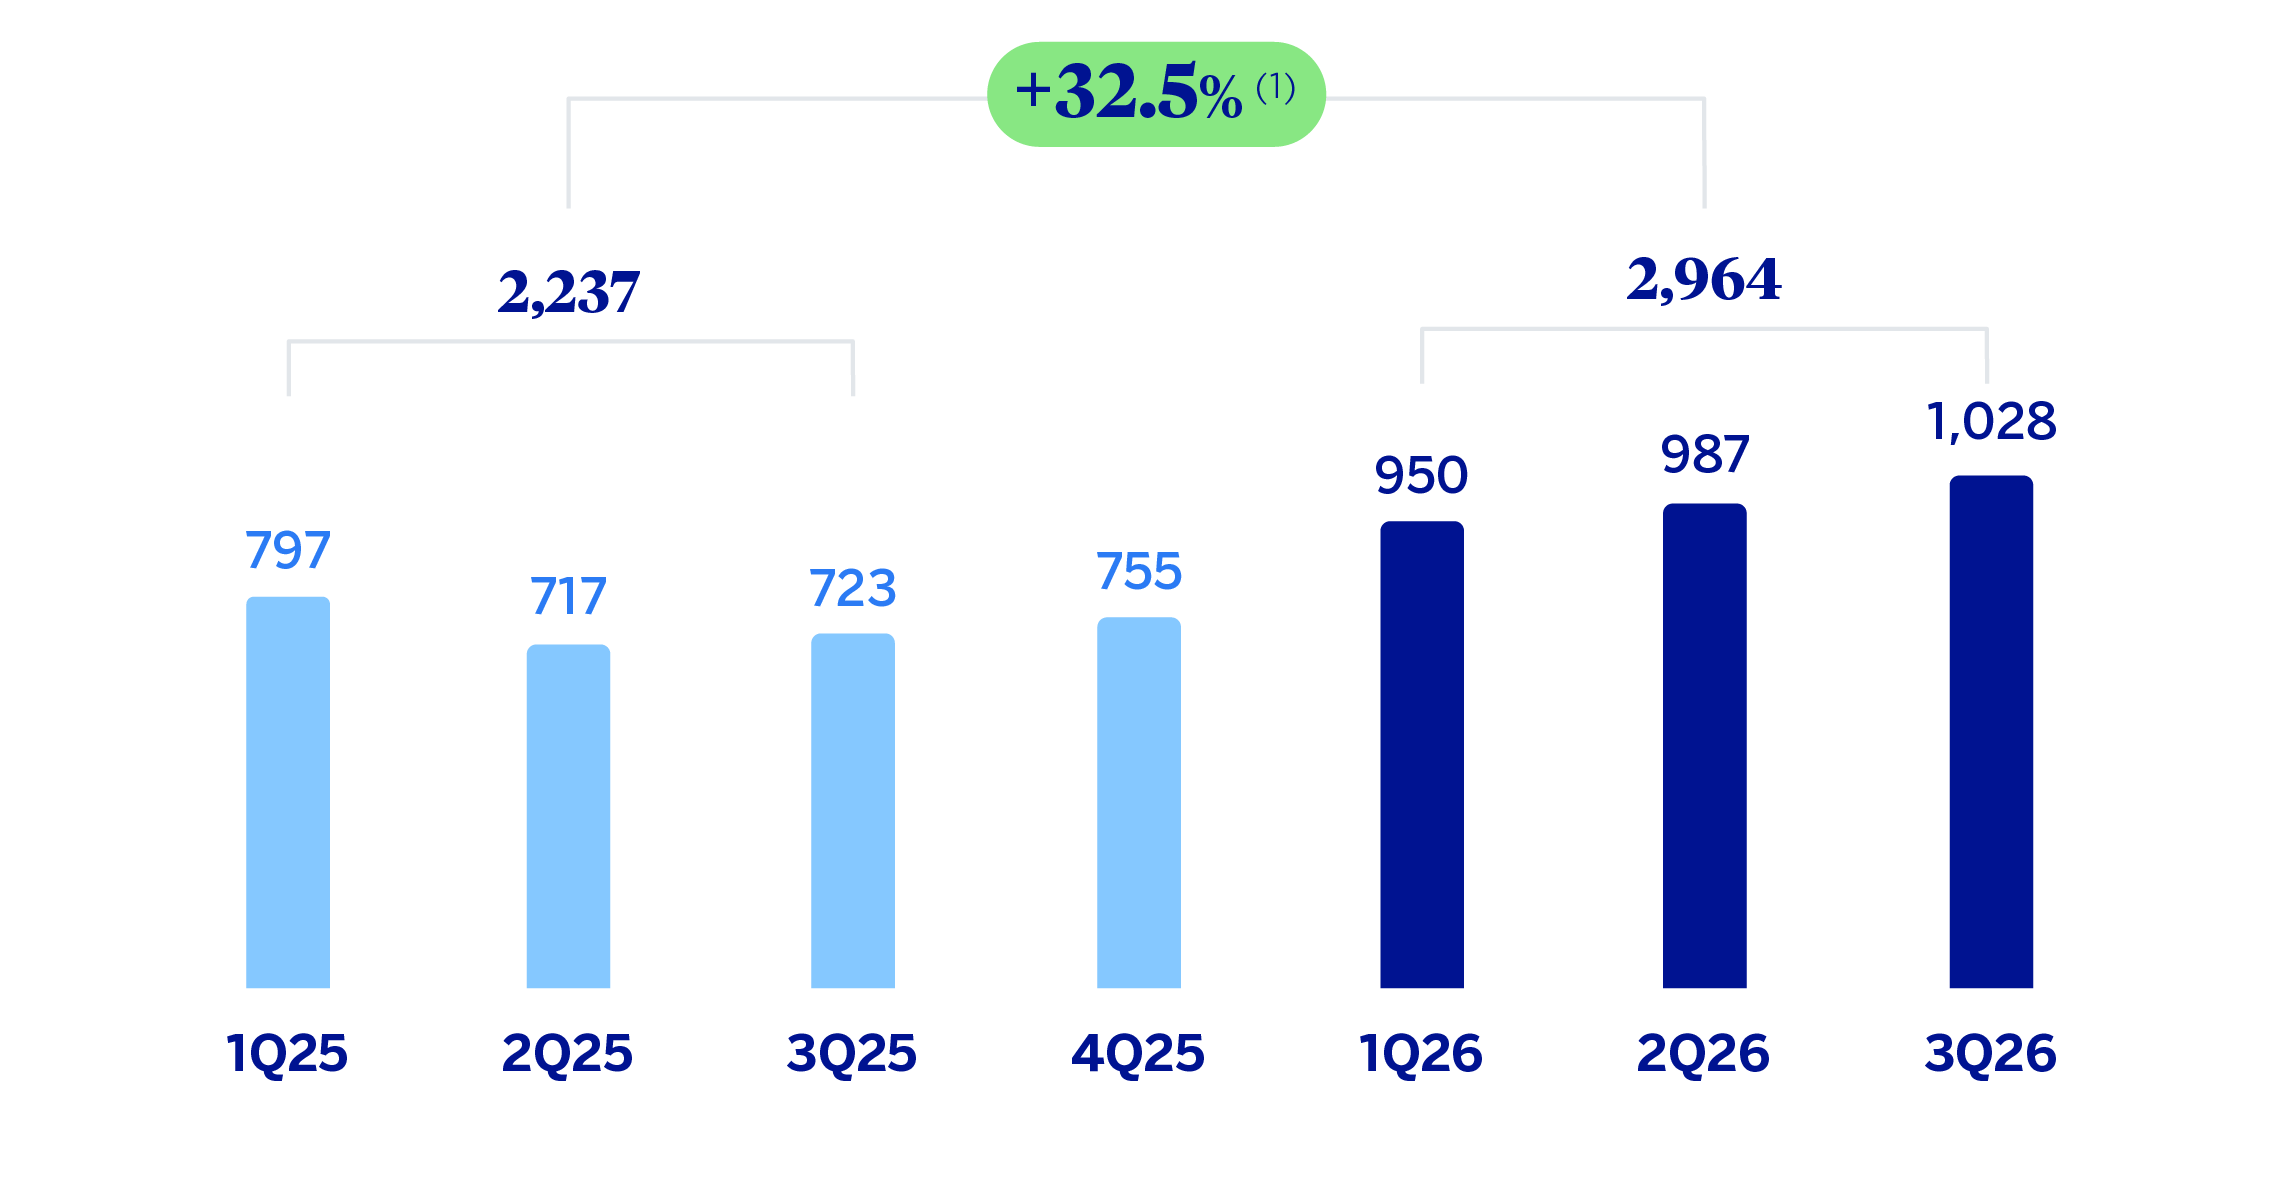
(1) At constant exchange rates: +31.0%.
NET ATTRIBUTABLE PROFIT (LOSS)
(MILLIONS OF EUROS AT CURRENT EXCHANGE RATES)
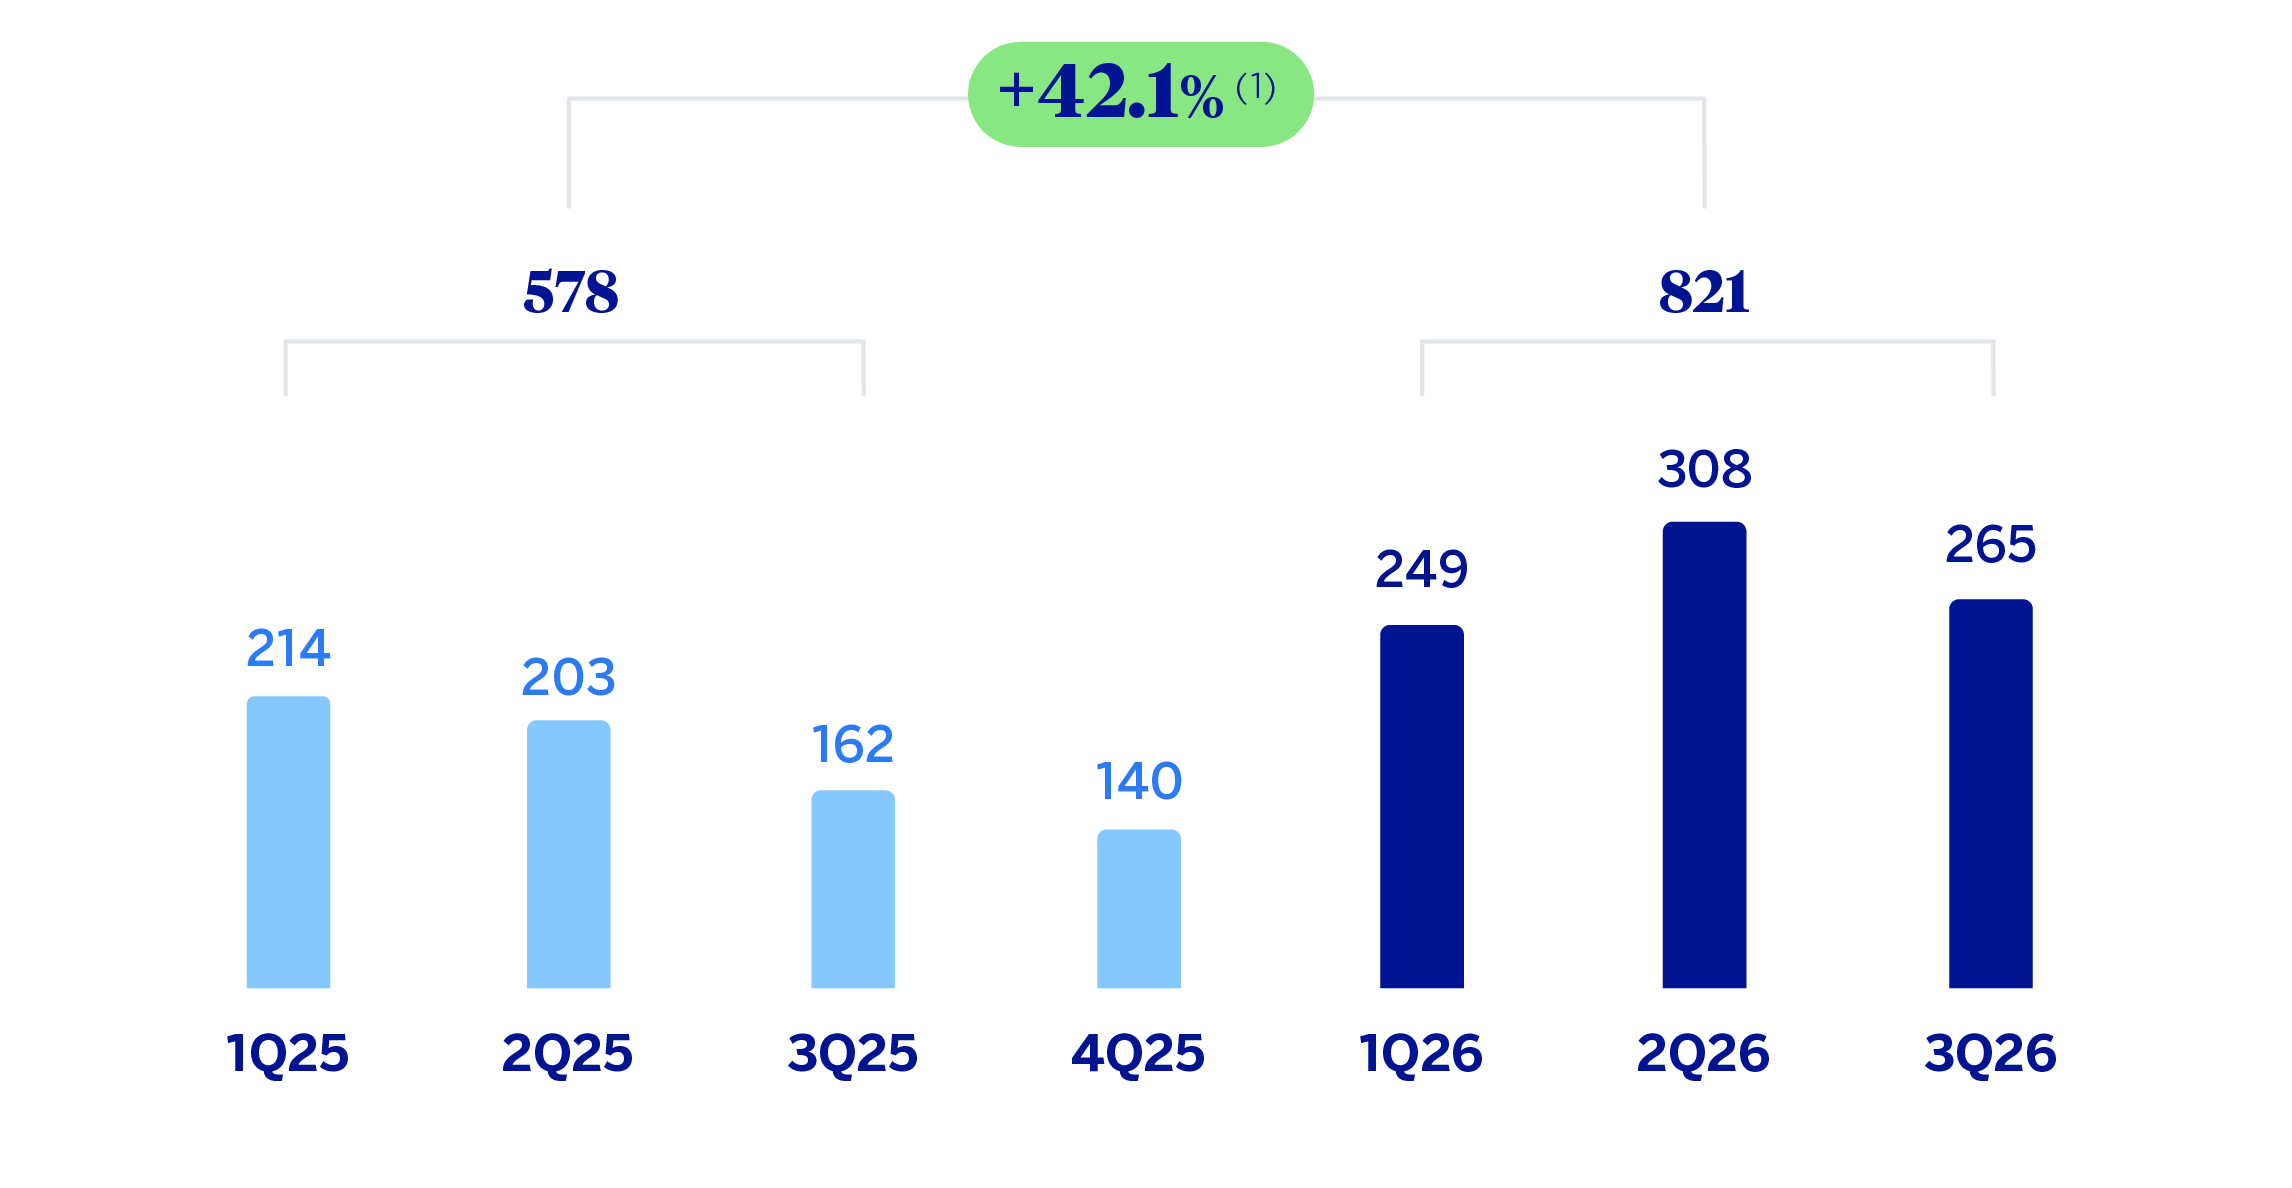
(1) At constant exchange rates: +41.1%.
| FINANCIAL STATEMENTS AND RELEVANT BUSINESS INDICATORS (MILLIONS OF EUROS AND PERCENTAGE) | ||||
|---|---|---|---|---|
| Income statement | Jan.-Sep.26 | 𝚫 % | 𝚫 % (1) | Jan.-Sep.25 (2) |
| Net interest income | 4,518 | 27.4 | 26.1 | 3,547 |
| Net fees and commissions | 844 | 28.7 | 28.9 | 655 |
| Net trading income | 459 | 6.0 | 5.8 | 433 |
| Other operating income and expenses | (756) | 20.9 | 23.2 | (625) |
| Gross income | 5,065 | 26.3 | 24.8 | 4,011 |
| Operating expenses | (2,101) | 18.4 | 17.0 | (1,774) |
| Personnel expenses | (971) | 21.9 | 21.0 | (797) |
| Other administrative expenses | (945) | 14.9 | 13.3 | (822) |
| Depreciation | (185) | 19.6 | 16.2 | (155) |
| Operating income | 2,964 | 32.5 | 31.0 | 2,237 |
| Impairment on financial assets not measured at fair value through profit or loss | (1,171) | 36.4 | 32.3 | (858) |
| Provisions or reversal of provisions and other results | 9 | n.s. | n.s. | (34) |
| Profit (loss) before tax | 1,803 | 34.0 | 34.2 | 1,345 |
| Income tax | (539) | 30.1 | 31.0 | (414) |
| Profit (loss) for the period | 1,264 | 35.8 | 35.6 | 931 |
| Non-controlling interests | (442) | 25.4 | 26.4 | (353) |
| Net attributable profit (loss) | 821 | 42.1 | 41.1 | 578 |
| Balance sheets | 30-09-26 | 𝚫 % | 𝚫 % (1) | 31-12-25 (2) |
| Cash, cash balances at central banks and other demand deposits | 8,475 | 5.0 | 1.5 | 8,073 |
| Financial assets designated at fair value | 14,836 | 39.9 | 31.7 | 10,602 |
| Of which: Loans and advances | 1,191 | n.s. | 244.7 | 297 |
| Financial assets at amortized cost | 63,157 | 16.3 | 10.0 | 54,283 |
| Of which: Loans and advances to customers | 59,866 | 16.8 | 10.5 | 51,235 |
| Tangible assets | 1,274 | 10.8 | 9.1 | 1,149 |
| Other assets | 2,708 | 7.6 | (0.2) | 2,517 |
| Total assets/liabilities and equity | 90,449 | 18.0 | 11.8 | 76,624 |
| Financial liabilities held for trading and designated at fair value through profit or loss | 3,448 | 41.9 | 23.6 | 2,430 |
| Deposits from central banks and credit institutions | 4,256 | 11.2 | 8.8 | 3,826 |
| Deposits from customers | 62,998 | 18.0 | 11.4 | 53,375 |
| Debt certificates issued | 4,409 | 9.8 | 6.0 | 4,015 |
| Other liabilities | 7,115 | 24.7 | 22.7 | 5,707 |
| Allocated regulatory capital | 8,224 | 13.1 | 7.1 | 7,271 |
| Relevant business indicators | 30-09-26 | 𝚫 % | 𝚫 % (1) | 31-12-25 |
| Performing loans and advances to customers under management (3) | 58,996 | 16.7 | 10.3 | 50,566 |
| Non-performing loans | 2,554 | 10.4 | 4.4 | 2,314 |
| Customer deposits under management (4) | 62,998 | 18.0 | 11.4 | 53,375 |
| Off-balance sheet funds (5) | 11,045 | 33.5 | 25.9 | 8,271 |
| Risk-weighted assets | 65,146 | 16.5 | 10.2 | 55,912 |
| RORWA (6) | 2.8 | 2.1 | ||
| Efficiency ratio (%) | 41.5 | 44.4 | ||
| NPL ratio (%) | 3.8 | 4.0 | ||
| NPL coverage ratio (%) | 89 | 92 | ||
| Cost of risk (%) | 2.72 | 2.50 | ||
| (1) At constant exchange rate. (2) Revised balances. For more information, please refer to the “Business Areas” section. (3) Excluding repos. (4) Excluding repos and including specific marketable debt securities. (5) Includes mutual funds and customer portfolios in Peru and Colombia (preliminary as of September 30, 2026). (6) For more information on the calculation methodology, as well as the calculation of the metric at the consolidated Group level, see Alternative Performance Measures at this report. |
||||
| SOUTH AMERICA. DATA PER COUNTRY (MILLIONS OF EUROS) | |||||||||
|---|---|---|---|---|---|---|---|---|---|
| Country | Operating income | Net attributable profit (loss) | |||||||
| Jan.-Sep.26 | 𝚫 % | 𝚫 % (1) | Jan.-Sep.25 | Jan.-Sep.26 | 𝚫 % | 𝚫 % (1) | Jan.-Sep.25 | ||
| Argentina | 783 | 55.6 | n.s. | 503 | 102 | (1.4) | n.s. | 104 | |
| Colombia | 720 | 54.6 | 36.0 | 466 | 278 | 129.2 | 101.5 | 121 | |
| Peru | 1,016 | 11.0 | 8.0 | 915 | 276 | 23.1 | 19.8 | 224 | |
| Other countries (2) | 445 | 26.2 | 25.5 | 353 | 165 | 28.0 | 27.3 | 129 | |
| Total | 2,964 | 32.5 | 31.0 | 2,237 | 821 | 42.1 | 41.1 | 578 | |
| (1) At constant exchange rates. (2) Chile (Forum), Uruguay, Venezuela and Brazil. Additionally, it includes eliminations and other charges. |
|||||||||
| SOUTH AMERICA. RELEVANT BUSINESS INDICATORS PER COUNTRY (MILLIONS OF EUROS) | ||||||||
|---|---|---|---|---|---|---|---|---|
| Argentina | Colombia | Peru | ||||||
| 30-09-26 | 31-12-25 | 30-09-26 | 31-12-25 | 30-09-26 | 31-12-25 | |||
| Performing loans and advances to customers under management (1)(2) | 9,981 | 8,085 | 21,597 | 20,182 | 21,616 | 19,991 | ||
| Non-performing loans (1) | 659 | 424 | 822 | 925 | 857 | 922 | ||
| Customer deposits under management (1)(3) | 11,844 | 9,997 | 23,425 | 21,659 | 23,050 | 21,037 | ||
| Off-balance sheet funds (1)(4) | 3,365 | 2,066 | 4,100 | 3,474 | 3,577 | 3,233 | ||
| Risk-weighted assets | 12,958 | 10,501 | 23,169 | 19,171 | 21,601 | 19,856 | ||
| RORWA (5) | 1.8 | 1.8 | 1.8 | 0.8 | 3.7 | 3.1 | ||
| Efficiency ratio (%) | 47.0 | 51.5 | 40.4 | 46.3 | 38.3 | 38.9 | ||
| NPL ratio (%) | 6.0 | 4.9 | 3.5 | 4.3 | 3.2 | 3.7 | ||
| NPL coverage ratio (%) | 76 | 84 | 83 | 88 | 107 | 99 | ||
| Cost of risk (%) | 7.52 | 5.67 | 2.07 | 2.19 | 1.43 | 1.67 | ||
| (1) Figures at constant exchange rates. (2) Excluding repos. (3) Excluding repos and including specific marketable debt securities. (4) Includes mutual funds and customer portfolios in Peru and Colombia (preliminary as of September 30, 2026). (5) For more information on the calculation methodology, as well as the calculation of the metric at the consolidated Group level, see Alternative Performance Measures at this report. |
||||||||
Unless expressly stated otherwise, all the comments below on rates of change, for both activity and results, will be given at constant exchange rates. These rates, together with the changes at current exchange rates, can be found in the attached tables of the financial statements and relevant business indicators.
Activity and results
The most relevant aspects related to the area's activity during the first nine months of 2026 were:
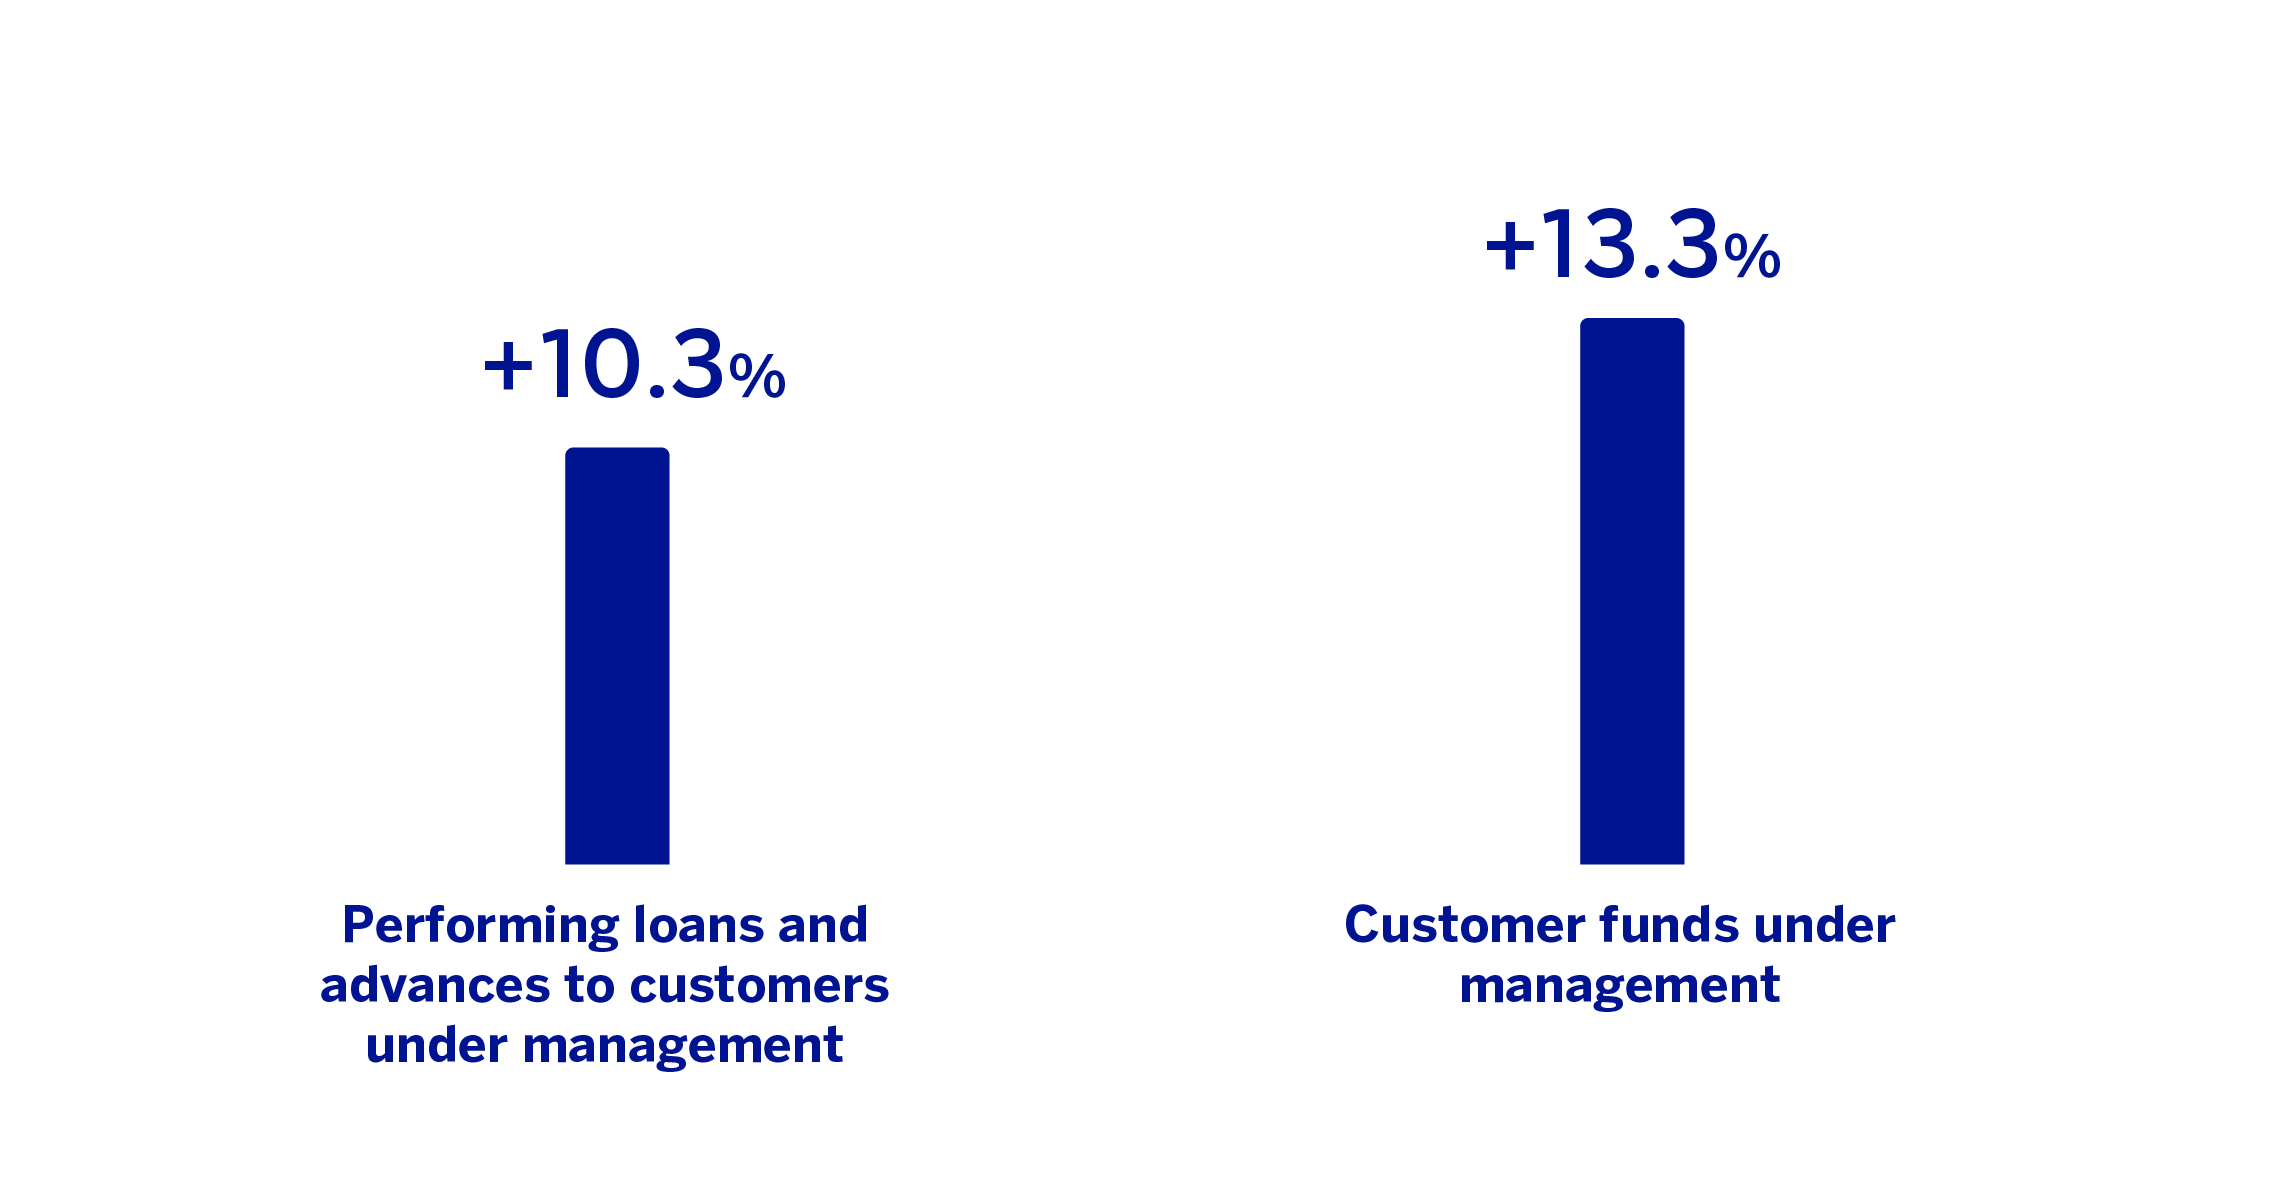
Lending activity (performing loans under management) increased by 10.3%, with a more dynamic growth in the wholesale portfolio (+12.7%) and a favorable evolution of all products in the retail portfolio, which grew by 7.7%.
Customer funds under management grew by 13.3% compared to the balances at the end of 2025, with a favorable performance in time deposits (+17.7%), demand deposits (+7.4%), and off-balance sheet funds(+25.9%).
The most relevant aspects related to the area's activity during the third quarter of the year 2026 have been:
Lending activity increased by 3.3%, mainly supported by the strong momentum in wholesale loans (+3.4%), where loans to enterprises stand out (+3.3%) along with solid evolution across all products in the retail segment (+3.1%).
With respect to credit quality, the area's NPL ratio stood at 3.8%, which represents a decrease of 18 basis points compared to the previous quarter, supported by activity growth and a reduction in non-performing balances in Peru and Colombia. For its part, the NPL coverage ratio stood at 89%, representing a decrease of 25 basis points compared to the end of June.
Customer funds under management increased at a rate of 4.2%, driven by the boost from time deposits from customers, which increased by 7.6%, and off-balance sheet funds, which grew by 11.6%.
South America generated a net attributable profit of €821 million in the first nine months of 2026, which represents a year-on-year growth of 42.1% at current exchange rates, favored by the evolution of net interest income and, to a lesser extent, fees and NTI. Within the main countries of the area, the evolution of the net attributable profit in Colombia stands out.
Meanwhile, the impact of the hyperinflation adjustment of subsidiaries domiciled in Argentina stands out, which implies, among other effects, the recording of the loss on the net monetary position in the "Other operating income and expenses" line of the income statement. This impact amounted to €384 million in the period January - September 2026, above the €277 million recorded in the period January - September 2025.
More detailed information on the most representative countries of the business area is provided below.
Argentina
Macro and industry trends
The Argentine economy continues to consolidate its macroeconomic stabilization process, supported by fiscal balance, greater exchange rate stability, and growth in the primary and energy sectors. Even so, the recovery remains uneven and the labor market maintains a weak tone. According to BBVA Research, GDP will grow by 3.0% in both 2026 and 2027, unchanged from the previous scenario. For its part, inflation stood at 33.4% in September, a level similar to that of previous months. Going forward, the forecast for a gradual moderation toward levels of 29.5% at the end of 2026 (+0.5 percentage points compared to the previous scenario) and 20% by the end of next year is maintained.
The banking system maintains more moderate growth than in previous quarters, in both loans and deposits. With data at the end of September 2026, total lending increased by 37.4% compared to September 2025, favored by the consumer, corporate, and, above all, mortgage portfolios, which grew by 22.1%, 46.7%, and 74.6% year-on-year, respectively. For their part, deposits have slightly slowed their growth, registering a year-on-year growth of 27.8% at the end of September. Finally, the NPL ratio continues to rise and stood at 7.7% at the end of July 2026, driven by the increase in the NPL ratio in household lending.
Activity and results
In the first nine months of 2026, the lending activity recorded a growth of 23.4% (slightly lower the accumulated inflation rate which reached +23.6%, while in the third quarter, this increase stood at 8.2% (above the quarterly inflation rate), in both cases favored mainly by the performance of corporate loans. At the end of September 2026, the NPL ratio stood at 6.0%, a decrease of -39 basis points compared to the second quarter, supported by growth in activity and a more contained increase in the non-performing balance (+1.6% at constant exchange rates) stemming from lower NPL inflows, higher recoveries, and higher write-offs. For its part the NPL coverage ratio, which stood at 76%, with a decrease of 37 basis points in the period.
Customer funds grew by 26.1% in the first nine months of 2026 (9.4% in the third quarter), with standout growth in time deposits and off-balance sheet funds.
Regarding the evolution of the income statement16, the cumulative net attributable profit at the end of September 2026 stood at €102 million (in line with the same period of the previous year), with growth in recurring revenue, offset, among others, by a more negative impact for hyperinflation compared to the first nine months of 2025 and, especially, by an increase in provisions for impairment in financial assets (mainly due to higher requirements in the retail portfolio, partly affected by a larger portfolio volume). Meanwhile, the accumulated cost of risk stood at 7.52%, which represents a decrease of 19 basis points compared to the cost of risk of the preceding quarter. The result of the third quarter reached €29 million, which represents a decrease compared to the previous quarter, driven by lower recurring revenue and NTI, partially offset by a lower negative adjustment for hyperinflation.
Colombia
Macro and industry trends
Private consumption and public spending have continued to support activity during the first half of 2026. According to BBVA Research, GDP will grow by 2.6% this year, the same figure anticipated in the previous scenario, and by 2.3% in 2027, with private investment playing an increasingly important role as a supporting factor for activity. For its part, inflation has continued the upward trend of recent months, standing at 6.3% in September. The El Niño phenomenon, persistent high energy prices and the strength of domestic demand could cause inflation to close 2026 at 7.0%, before beginning a path of gradual moderation toward levels of 5.4% by the end of 2027.
Total lending growth in the banking system stood at 9.0% year-on-year in August 2026, with growth across all portfolios. Thus, the corporate lending, mortgages, and consumer loan portfolios showed year-on-year growth rates of 7.6%, 10.6%, and 10.6%, respectively. On the other hand, total deposits showed a growth of 10.2% year-on-year at the end of August 2026, with a trend driven growth in demand deposits. Thus, demand and time deposits grew by 11.7% and 8.5% year-on-year, respectively. The system's NPL grew slightly over the last month, standing at 3.81% in August 2026, 40 basis points below the figure for the same month of the previous year.
Activity and results
Lending activity grew at a rate of 7.0% compared to the end of 2025 (1.8% in the third quarter), favored mainly by the performance of the corporate segment and with a rebound in consumer loans in the third quarter. In terms of asset quality indicators, the NPL ratio stood at 3.5%, representing a reduction of 18 basis points with respect to the previous quarter and 73 basis points compared to the end of the previous year, continuing the positive trend of recent quarters. On the other hand, coverage stood at 83%, with a decrease of 217 basis points compared to the previous quarter.
Customer funds grew by 9.5% compared to the end of 2025 and 2.4% during the third quarter. In the first nine months of 2026 the performance of time deposits stood out increasing by 13.3%, while demand deposits showed an increase of 3.2%, and off-balance sheet funds of 18.0%.
The cumulative net attributable profit at the end of September 2026 stood at €278 million, that is, 101.5% higher than the result for the same period of the previous year, favored mainly by growth in the net interest income, although all line items that make up gross income showed a favorable performance. For its part, impairment on financial assets stood slightly below the previous year, and the accumulated cost of risk reached 2.07% at the end of September 2026, 5 basis points above previous quarter. The net attributable profit of the third quarter stood at €94m, 6.5% below the previous quarter, mainly due to higher income tax expense. Apart from the above, the strong performance across all gross income components stood out, and lower operating expenses were recorded.
Perú
Macro and industry trends
In recent months, the dynamism of domestic demand, supported by private consumption and investment, has contrasted with the deterioration in activity in the primary sectors as a consequence of the El Niño phenomenon. Higher energy prices and a stronger than expected impact from weather conditions explain the downward revision of growth forecasts for the Peruvian economy. BBVA Research places GDP growth for 2026 at 2.9%, two-tenths of a percentage point below what was anticipated in the previous scenario, and keeps it at that figure for 2027. Regarding price performance, inflation picked up again in September to stand at 4.5%. It is expected to remain high over the coming months, potentially closing 2026 at levels of 4.9%, and beginning a path of progressive correction as 2027 progresses toward levels slightly above 2% by the end of that year. In this context, BBVA Research forecasts that the central bank will carry out two benchmark interest rate hikes before the end of 2026, from 4.25% to 4.75%, and reverse them during the following fiscal year once price pressures ease.
Total lending in the Peruvian banking system increased by 9.1% in year-on-year terms in August 2026, with positive growth across all portfolios. Thus, the consumer loan portfolio grew by 15.9% year-on-year, the mortgage portfolio increased by 7.9%, and the corporate lending portfolio increased by 7.1% year-on-year. For their part, the system's total deposits registered a year-on-year growth of 13.4% in August 2026, thanks to the 16.3% growth in demand deposits and 7.7% in time deposits. Finally, the system's NPL ratio stood at 2.82% in August 2026, below the level observed in the same month of the previous year.
Activity and results
Lending activity grew by 8.1% compared to the end of December 2025 (a 2.4% during the third quarter), driven by corporate loans, with a growth of 8.7%, as well as by consumer loans, which grew by 11.0%. Regarding the asset quality indicators, the NPL ratio improved compared to the end of June 2026 (-15 basis points and -54 basis points compared to the end of the previous year) placing at 3.2%, as a result of strong recovery performance and contained entries, and portfolio sales carried out during the quarter. Meanwhile, the NPL coverage ratio was 107%, which represents an increase of 223 basis points compared to the end of June, supported by the reduction in non-performing loans.
Customer funds under management increased during the first nine months of 2026 (+9.7%, and +3.5% in the third quarter), thanks to the favorable performance in customer deposits (+9.6%), mainly from retail customers.
BBVA Peru's cumulative attributable profit stood at €276 million at the end of September 2026, that is, 19.8% above the figure reached in the first nine months of the previous year, mainly as a result of growth in net interest income, associated with a higher profitability and volume of the loan portfolio, as well as lower impairment on financial assets and other provisions. For its part, the cumulative cost of risk at the end of the third quarter stood at 1.43%, representing an increase of 18 basis points compared to the cost of risk of the previous quarter. The profit of the quarter stood at €81 million, representing a decrease of 28.6% compared to the previous quarter, mainly as a result of higher impairment on financial assets (which were particularly low in the previous quarter).
16 At current rates, that is, the impact of exchange rate fluctuations on the profit and loss account is not excluded.
Read legal disclaimer of this report.