


Additional pro forma information: Corporate & Investment Banking
Highlights for the period January - September 2026
- Growth in lending and customer deposits
- Positive evolution of recurring revenues
- Strong gross income in all business divisions
- New increase in quarterly net attributable profit, one of the highest in the quarterly series
BUSINESS ACTIVITY (1) (VARIATION AT CONSTANT EXCHANGE RATES COMPARED TO 31-12-25)
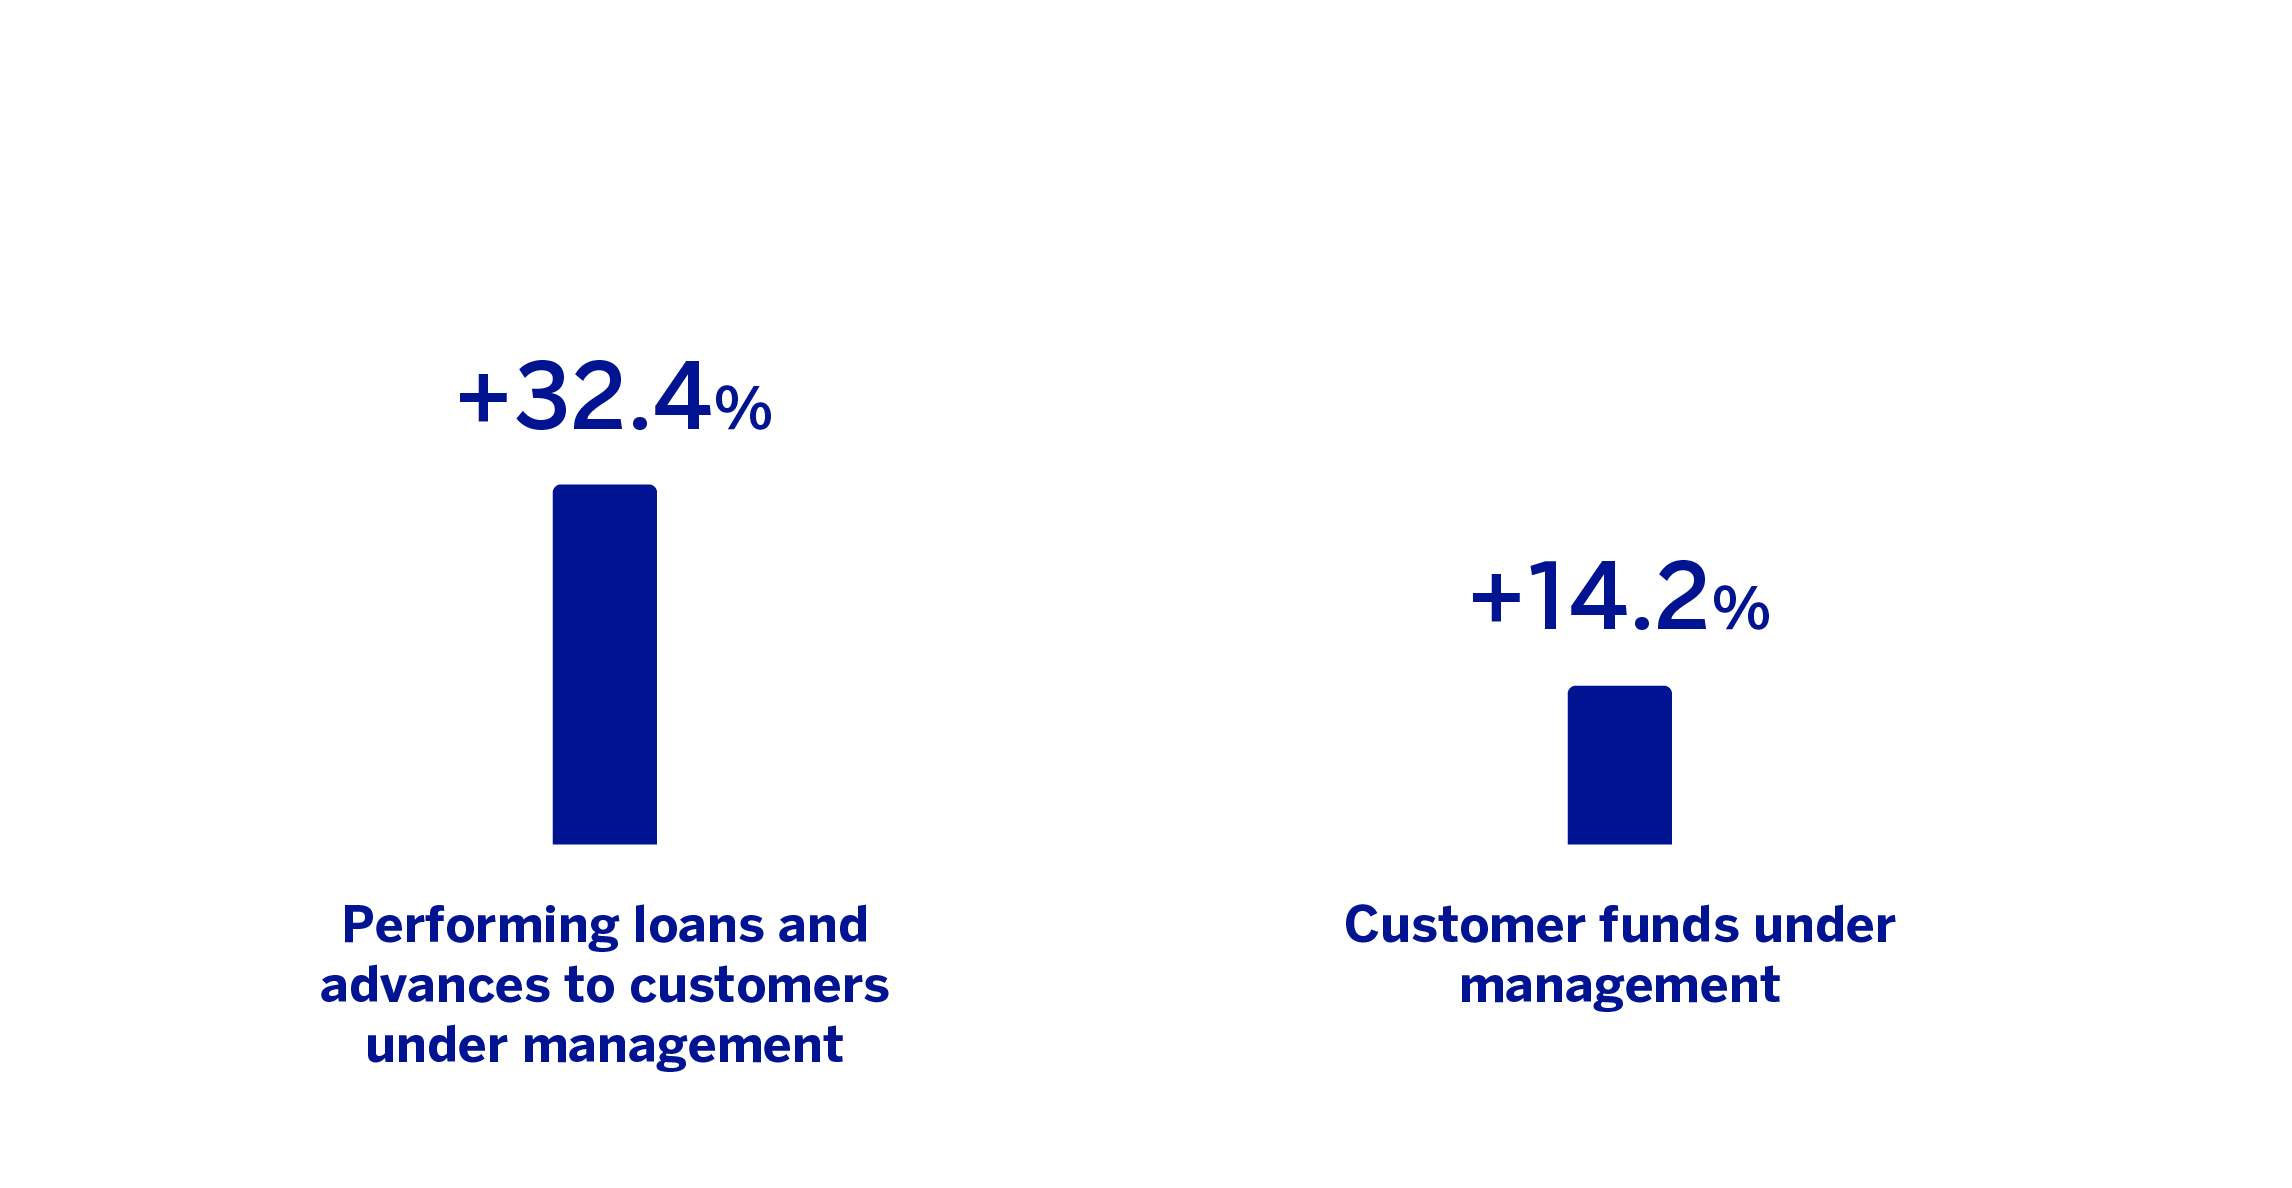
(1) Excluding repos.
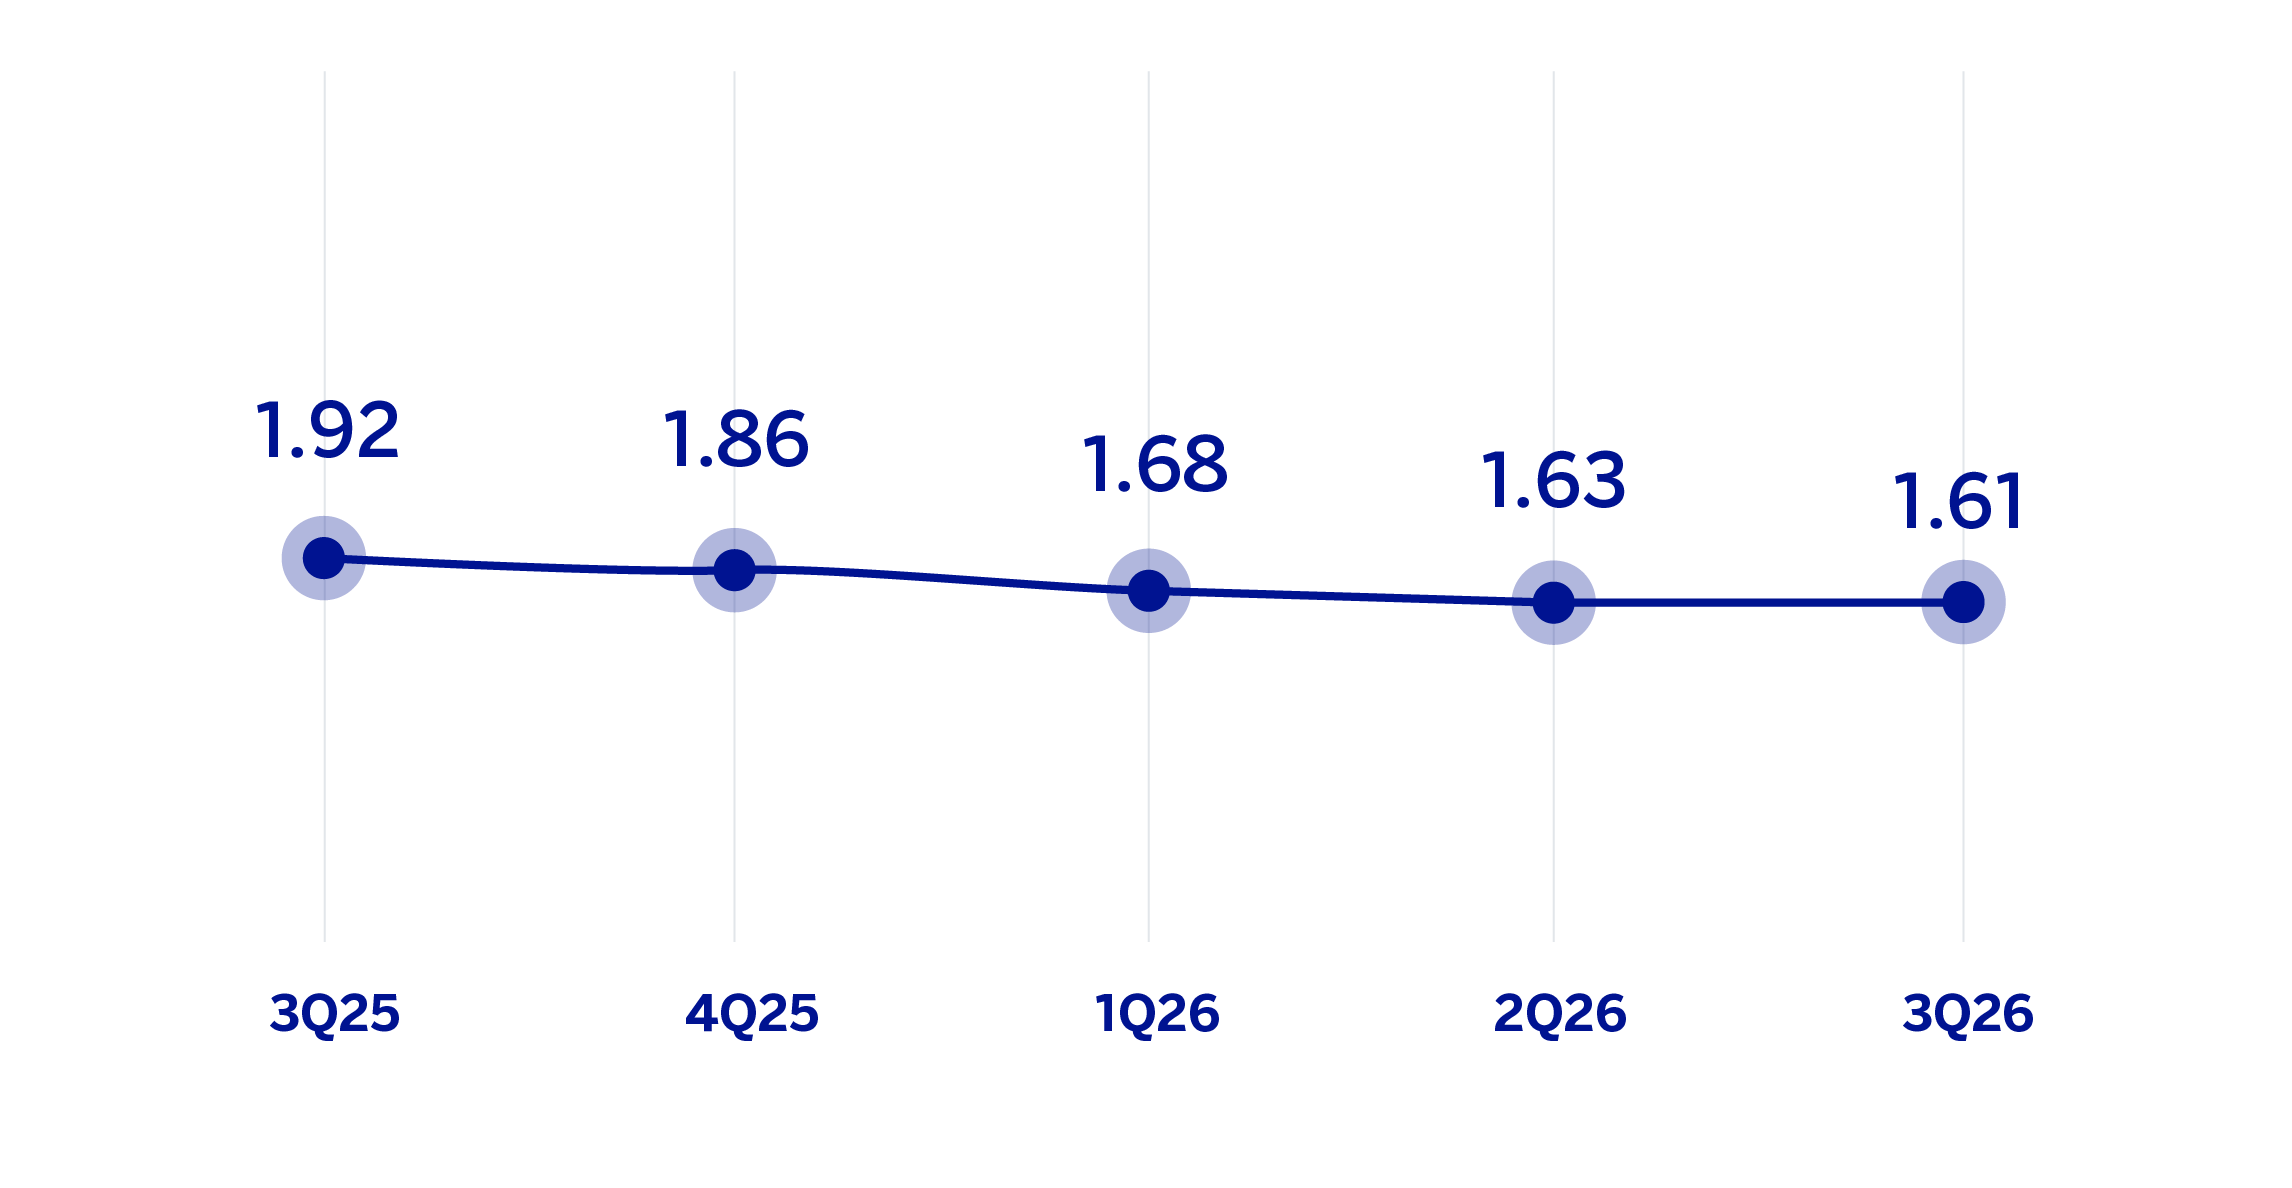
RECURRING REVENUES / AVERAGE TOTAL ASSETS
(PERCENTAGE AT CONSTANT EXCHANGE RATES)
OPERATING INCOME
(MILLIONS OF EUROS AT CONSTANT EXCHANGE RATES)
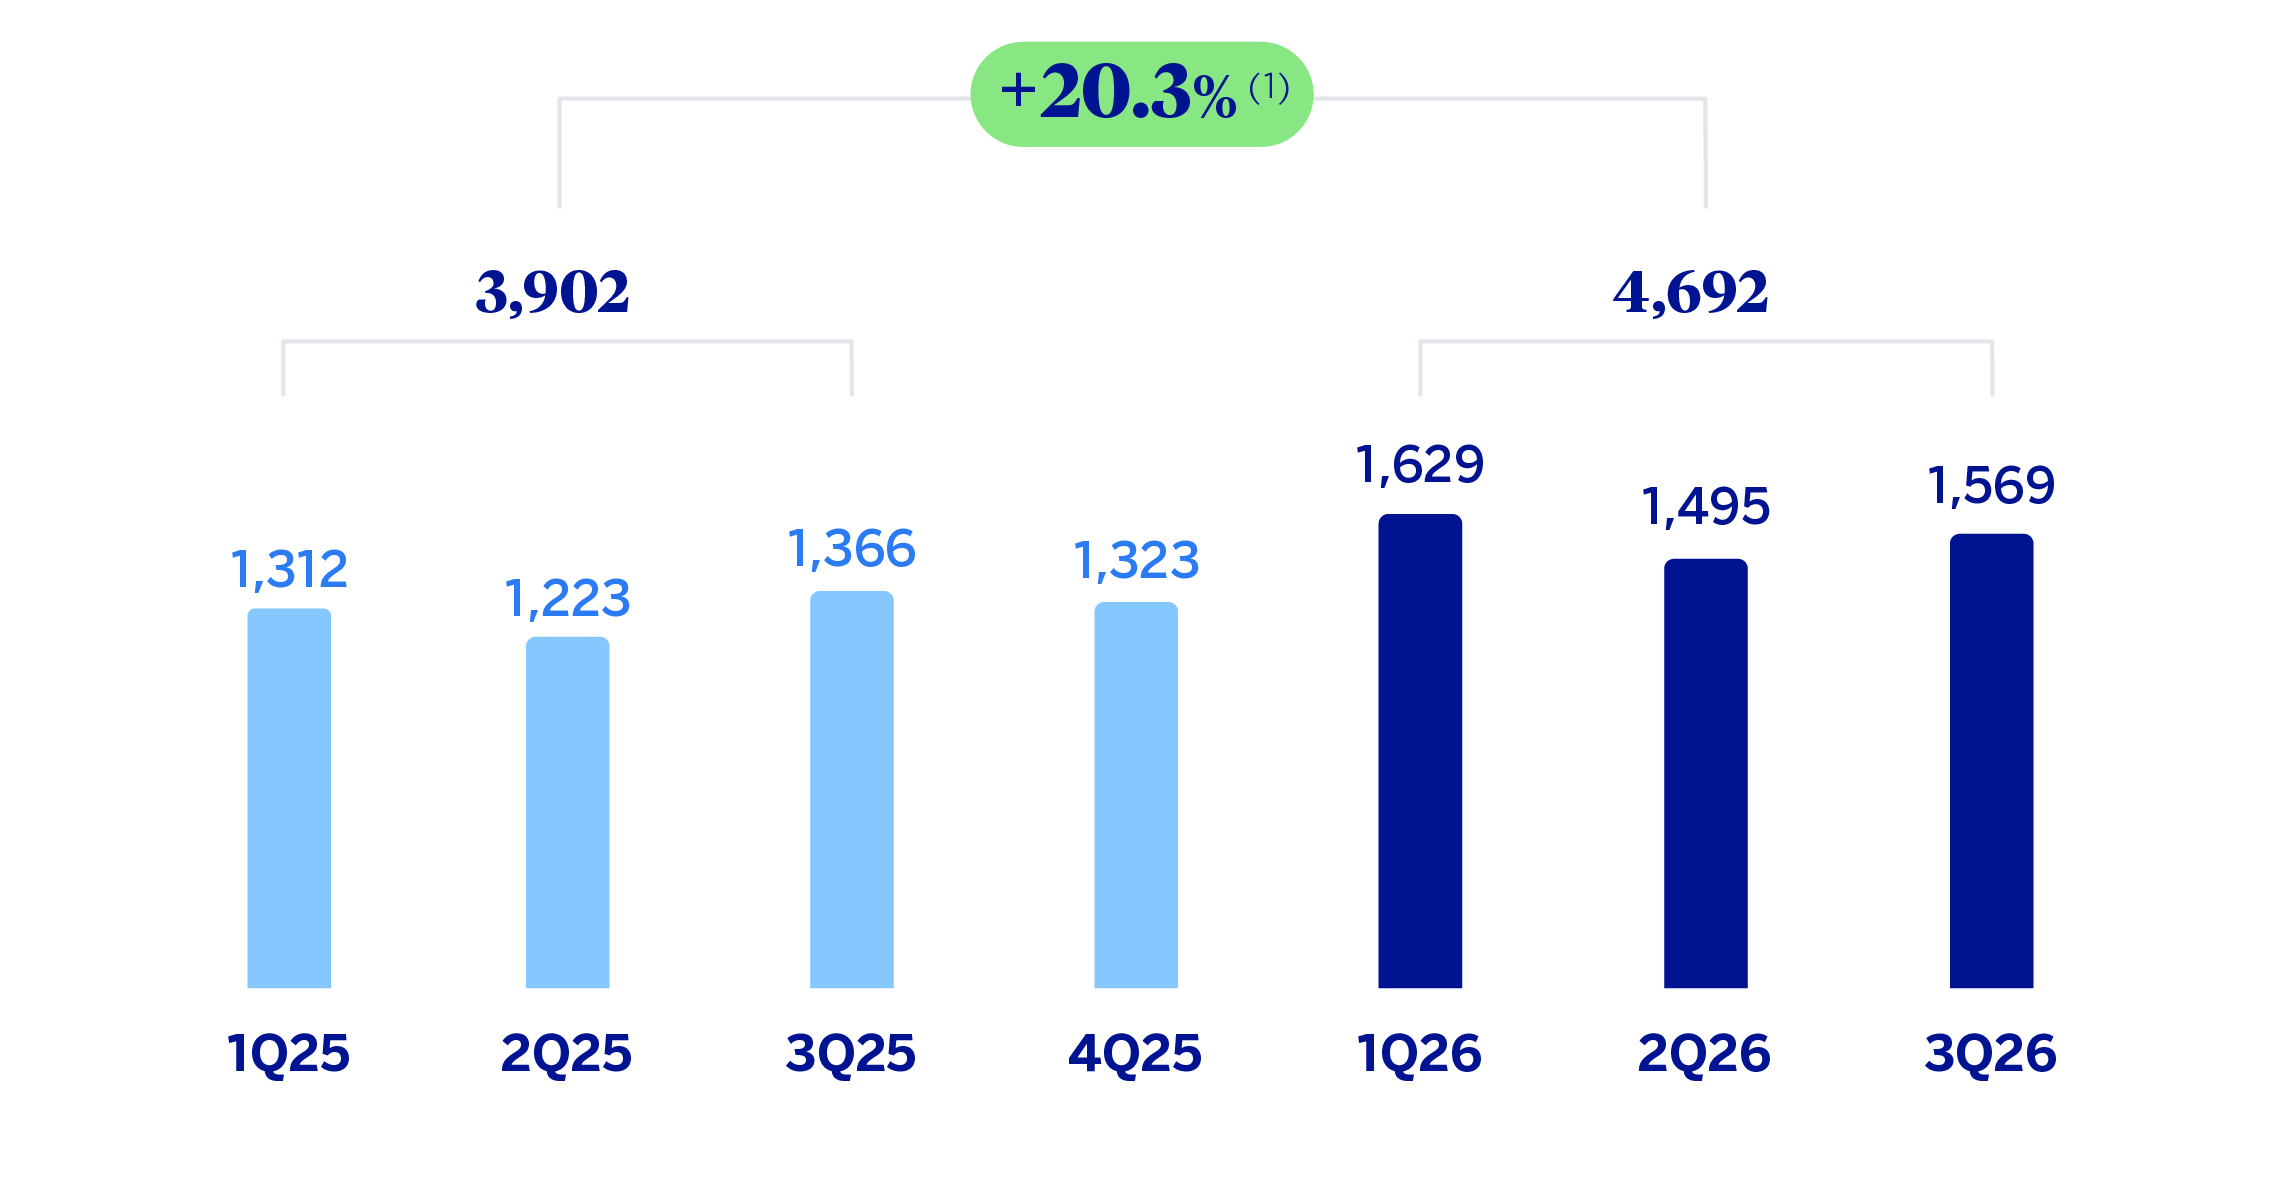
(1) At current exchange rates: +18.5%.
NET ATTRIBUTABLE PROFIT (LOSS)
(MILLIONS OF EUROS AT CONSTANT EXCHANGE RATES)
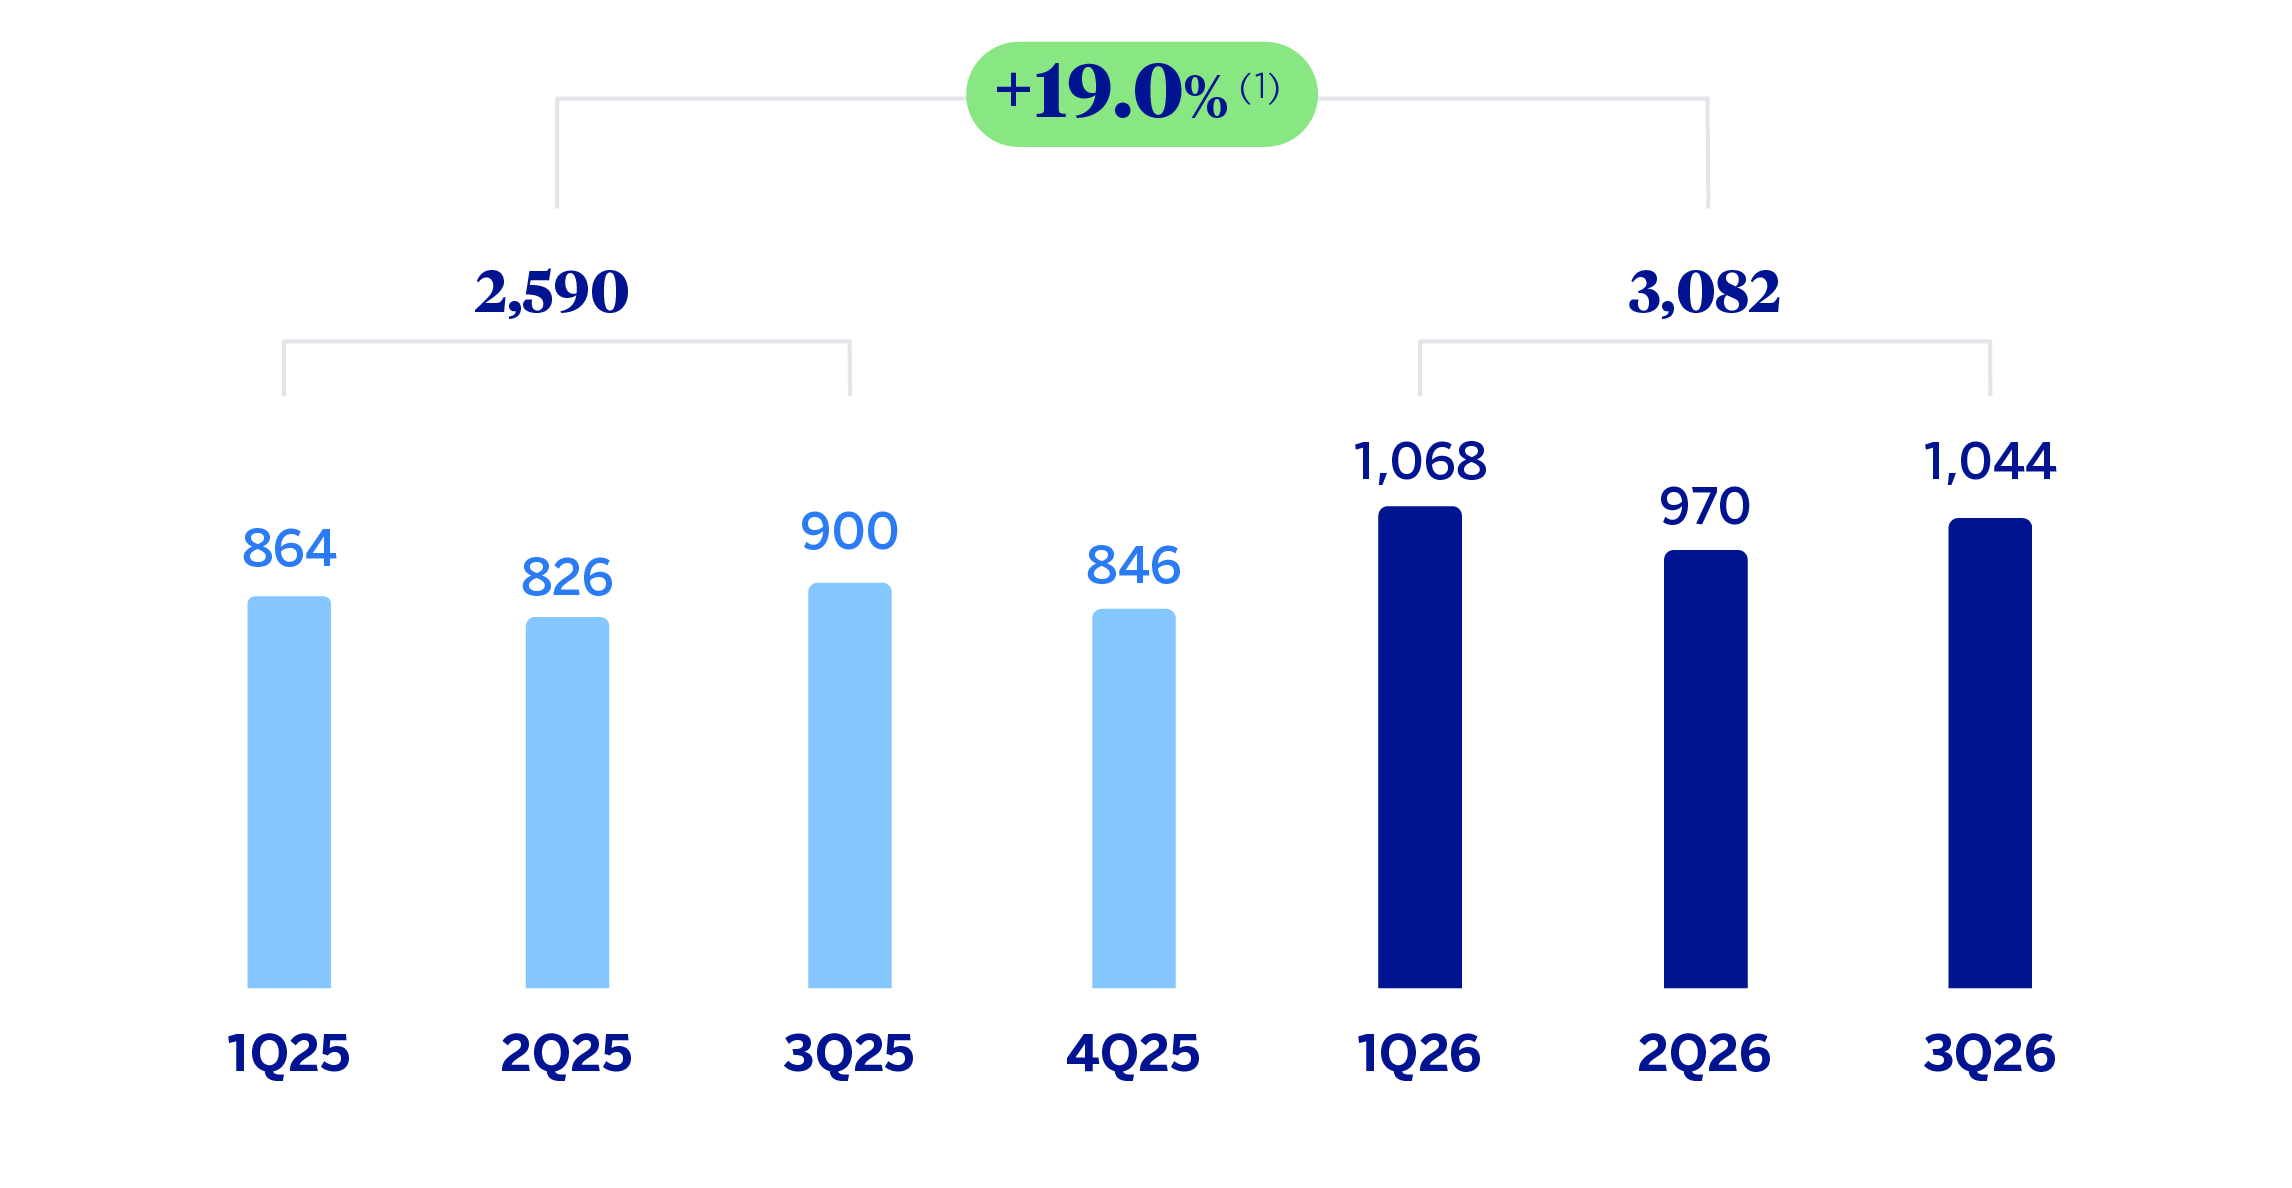
(1) At current exchange rates: +17.5%.
The additional pro forma information from CIB excludes the application of hyperinflation accounting and the Group's wholesale business in Venezuela.
| FINANCIAL STATEMENTS AND RELEVANT BUSINESS INDICATORS (MILLIONS OF EUROS AND PERCENTAGE) | ||||
|---|---|---|---|---|
| Income statement | Jan.-Sep.26 | 𝚫 % | 𝚫 % (1) | Jan.-Sep.25 (2) |
| Net interest income | 3,343 | 22.9 | 24.7 | 2,720 |
| Net fees and commissions | 1,295 | 20.6 | 18.9 | 1,074 |
| Net trading income | 1,774 | 15.6 | 16.6 | 1,535 |
| Other operating income and expenses | (61) | 82.5 | 71.0 | (34) |
| Gross income | 6,351 | 19.9 | 20.8 | 5,296 |
| Operating expenses | (1,659) | 24.2 | 22.5 | (1,336) |
| Personnel expenses | (794) | 20.7 | 20.0 | (658) |
| Other administrative expenses | (742) | 27.5 | 24.8 | (582) |
| Depreciation | (122) | 27.7 | 26.1 | (96) |
| Operating income | 4,692 | 18.5 | 20.3 | 3,960 |
| Impairment on financial assets not measured at fair value through profit or loss | (5) | n.s. | n.s. | 68 |
| Provisions or reversal of provisions and other results | 11 | n.s. | n.s. | (5) |
| Profit (loss) before tax | 4,698 | 16.8 | 18.9 | 4,022 |
| Income tax | (1,339) | 18.5 | 20.7 | (1,130) |
| Profit (loss) for the period | 3,358 | 16.1 | 18.2 | 2,892 |
| Non-controlling interests | (276) | 3.1 | 9.4 | (268) |
| Net attributable profit (loss) | 3,082 | 17.5 | 19.0 | 2,624 |
| Balance sheets | 30-09-26 | 𝚫 % | 𝚫 % (1) | 31-12-25 (2) |
| Cash, cash balances at central banks and other demand deposits | 24,910 | 64.9 | 60.8 | 15,106 |
| Financial assets designated at fair value | 169,214 | 29.6 | 28.6 | 130,559 |
| Of which: Loans and advances | 69,833 | 54.3 | 54.0 | 45,254 |
| Financial assets at amortized cost | 202,131 | 30.6 | 29.5 | 154,718 |
| Of which: Loans and advances to customers | 169,179 | 30.7 | 29.5 | 129,459 |
| Inter-area positions | — | — | — | — |
| Tangible assets | 271 | 0.7 | (1.5) | 269 |
| Other assets | 5,014 | 37.7 | 35.0 | 3,640 |
| Total assets/liabilities and equity | 401,539 | 32.0 | 30.7 | 304,292 |
| Financial liabilities held for trading and designated at fair value through profit or loss | 131,985 | 35.0 | 34.4 | 97,798 |
| Deposits from central banks and credit institutions | 44,047 | 5.4 | 5.0 | 41,780 |
| Deposits from customers | 120,472 | 13.9 | 13.6 | 105,751 |
| Debt certificates issued | 19,874 | 44.4 | 43.7 | 13,766 |
| Inter-area positions | 59,645 | 116.6 | 103.9 | 27,535 |
| Other liabilities | 9,278 | 165.8 | 152.4 | 3,490 |
| Allocated regulatory capital | 16,238 | 14.6 | 13.7 | 14,171 |
| Relevant business indicators | 30-09-26 | 𝚫 % | 𝚫 % (1) | 31-12-25 (2) |
| Performing loans and advances to customers under management (3) | 168,888 | 33.6 | 32.4 | 126,424 |
| Non-performing loans | 882 | 45.8 | 56.5 | 605 |
| Customer deposits under management (3) | 112,217 | 13.8 | 13.7 | 98,567 |
| Off-balance sheet funds (4) | 5,653 | 28.6 | 24.3 | 4,394 |
| Risk-weighted assets | 132,363 | 10.9 | 10.0 | 119,382 |
| RORWA (5) | 3.6 | 3.4 | ||
| Efficiency ratio (%) | 26.1 | 26.9 | ||
| General note: For the translation of the income statement in those countries where hyperinflation accounting is applied, the end of period exchange rate as of September 30, 2026 is used. (1) At constant exchange rates. (2) Revised balances. For more information, please refer to the “Business Areas” section. (3) Excluding repos. (4) Includes mutual funds, customer portfolios and other off-balance sheet funds. (5) For more information on the calculation methodology, as well as the calculation of the metric at the consolidated Group level, see Alternative Performance Measures at this report. |
||||
Unless expressly stated otherwise, all the comments below on rates of change, for both activity and results, will be given at constant exchange rates. For the conversion of these figures in those countries in which accounting for hyperinflation is applied, the end of period exchange rate as of September 30, 2026 is used. These rates, together with changes at current exchange rates, can be found in the attached tables of financial statements and relevant business indicators. When making comments referring to Europe in this area, Spain is excluded.
Activity
The most relevant aspects related to the area's activity in the first nine months of 2026 were:
Lending activity in the Group's wholesale businesses showed a solid performance, with growing balances of 32.4% over the end of 2025. This dynamism was driven by the United States, Europe and Asia (Rest of Business) highlighting the activity in project finance and corporate lending.
Customer funds resumed their positive performance and showed growth of 14.2% in the first nine months of 2026, thanks to the recovery in balances during the third quarter. All countries delivered customer funds growth, except Spain, where a slight decrease was observed.
The most relevant aspects related to the area's activity in the third quarter of 2026 were:
Lending stood at the end of September 2026, 10.7% above the balance as of June 30, 2026, continuing the upward trend of recent quarters driven by the performance of the countries comprising the Rest of Business area, particularly the United States and Asia.
Customer funds grew 16.5%, with strong growth in July that moderated in August and September, where the performance of Rest of Business and, to a lesser extent, Spain and Mexico mainly stood out.
Results
CIB generated a net attributable profit of €3,082 million in the first nine months of 202617. This result represents a 19.0% increase over the previous year, which once again reflects the strength of the Group's wholesale businesses, with the aim of offering a value proposition focused on the needs of its customers.
All business divisions recorded double-digit revenue growth: Global Markets with a strong performance in all its products, particularly in interest rates, credit and equities; Global Transaction Banking (GTB), thanks to the positive evolution of recurring revenues, mainly net interest income; excellent results in IB&F, with relevant operations that have generated fee and commission income and a positive evolution of net interest income. All business divisions showed growth in net attributable profit.
The most relevant aspects of the year-on-year income statement evolution as of the end of September 2026 are summarized below:
Net interest income increased by 24.7%, driven by the growth in the volume of lending activity, both in GTB and IB&F throughout 2025 and in the first nine months of 2026, which generally offset the narrowing of customer spreads across all geographical areas.
Net fees and commissions recorded an increase of 18.9%, mainly driven by the strong performance of Project Finance and Corporate Lending in IB&F as well as by the guarantee activity associated with Working Capital and Trade Finance in GTB.
Growth in the NTI line (+16.6%) was driven by commercial activity, with a strong performance across all underlying asset classes, where interest rates and equities stood out.
Operating expenses grew by 22.5% driven by higher personnel expenses, associated with strategic plans and new capabilities, together with the impact of the voluntary redundancies in the first quarter of 2026, and higher general expenses (mainly in technology).
The impairment on financial assets line recorded a provision of €-5 million, which contrasts with the releases of the first nine months of 2025, mainly originated in Turkey.
In the third quarter of 2026 and excluding the effect of the variation in exchange rates, the Group's wholesale businesses generated a net attributable profit of €1,044m, representing a growth of 7.7% compared to the previous quarter, driven mainly by growth in net interest income, followed by strong results in NTI.
17 The additional pro forma information from CIB excludes the application of hyperinflation accounting and the Group's wholesale business in Venezuela.
Read legal disclaimer of this report.