


Risk management
At a global level, uncertainty regarding the resolution of the geopolitical conflicts in the Middle East and Ukraine, with the resulting implications for the potential normalization of trade in the affected regions and its impact on energy input prices means that the balance of risks remains tilted to the downside. The evolution of these international tensions adds complexity to the global macroeconomic environment, and the duration and intensity of these factors could affect the geographical areas in which the Group operates to varying degrees, with differentiated impacts by country. Similarly, the occurrence of extreme weather events and the potential resurgence of the threat of interventionist actions by the U.S. administration also constitute sources of risk.
In Spain, economic activity maintained a favorable performance during the second quarter of 2026, with a positive outlook toward the end of the year. For its part, inflation recorded a significant uptick during the third quarter, although a gradual moderation is expected in the coming months. All of this took place in a context in which the financial system continues to show comfortable solvency and liquidity levels. In Mexico, the strong economic momentum in the second quarter has led to an upward revision of the growth forecast, in a context of moderating inflationary pressures, with a banking system that continues to show lending growth. In Turkey, macroeconomic developments remain conditioned by inflation, the management of monetary and fiscal policies, and the volatility of the environment. Lastly, in South America, a heterogeneous performance across countries is expected, in a context of differing trends in growth, inflation, and interest rates, in an environment also subject to the severity of potential weather events, which have a particular impact on the region.
Within this framework, the Group continuously monitors the evolution of the macroeconomic and geopolitical environment, as well as its potential impact on the evolution of credit risk, in accordance with the applicable accounting and prudential regulations.
Credit risk metrics
The Group periodically reviews its individual estimates and its models for collective estimates of expected losses, as well as the impact of macroeconomic scenarios considered for such purposes. It should be noted that, although these updates incorporate the best information available at the relevant time, they may not fully reflect the most recent developments in the economic environment, especially in contexts of high uncertainty and volatility, or with respect to very recent events still underway.
For the estimation of expected losses, the models include individual and collective estimates, taking into account the macroeconomic forecasts as established in IFRS 9. Thus, the estimate at the end of the quarter includes the effect on expected losses of updating macroeconomic forecasts. The Group may supplement these expected losses to account for effects that may not be included therein, either because it considers that there are additional risk factors, or to incorporate sectoral particularities or those that may affect a set of operations or borrowers, following a formal internal approval process established for this purpose.
As of September 30, 2026 and December 31, 2025, the Group had not recognized any material adjustment to the models used in the estimation of expected credit losses.
BBVA Group's credit risk indicators
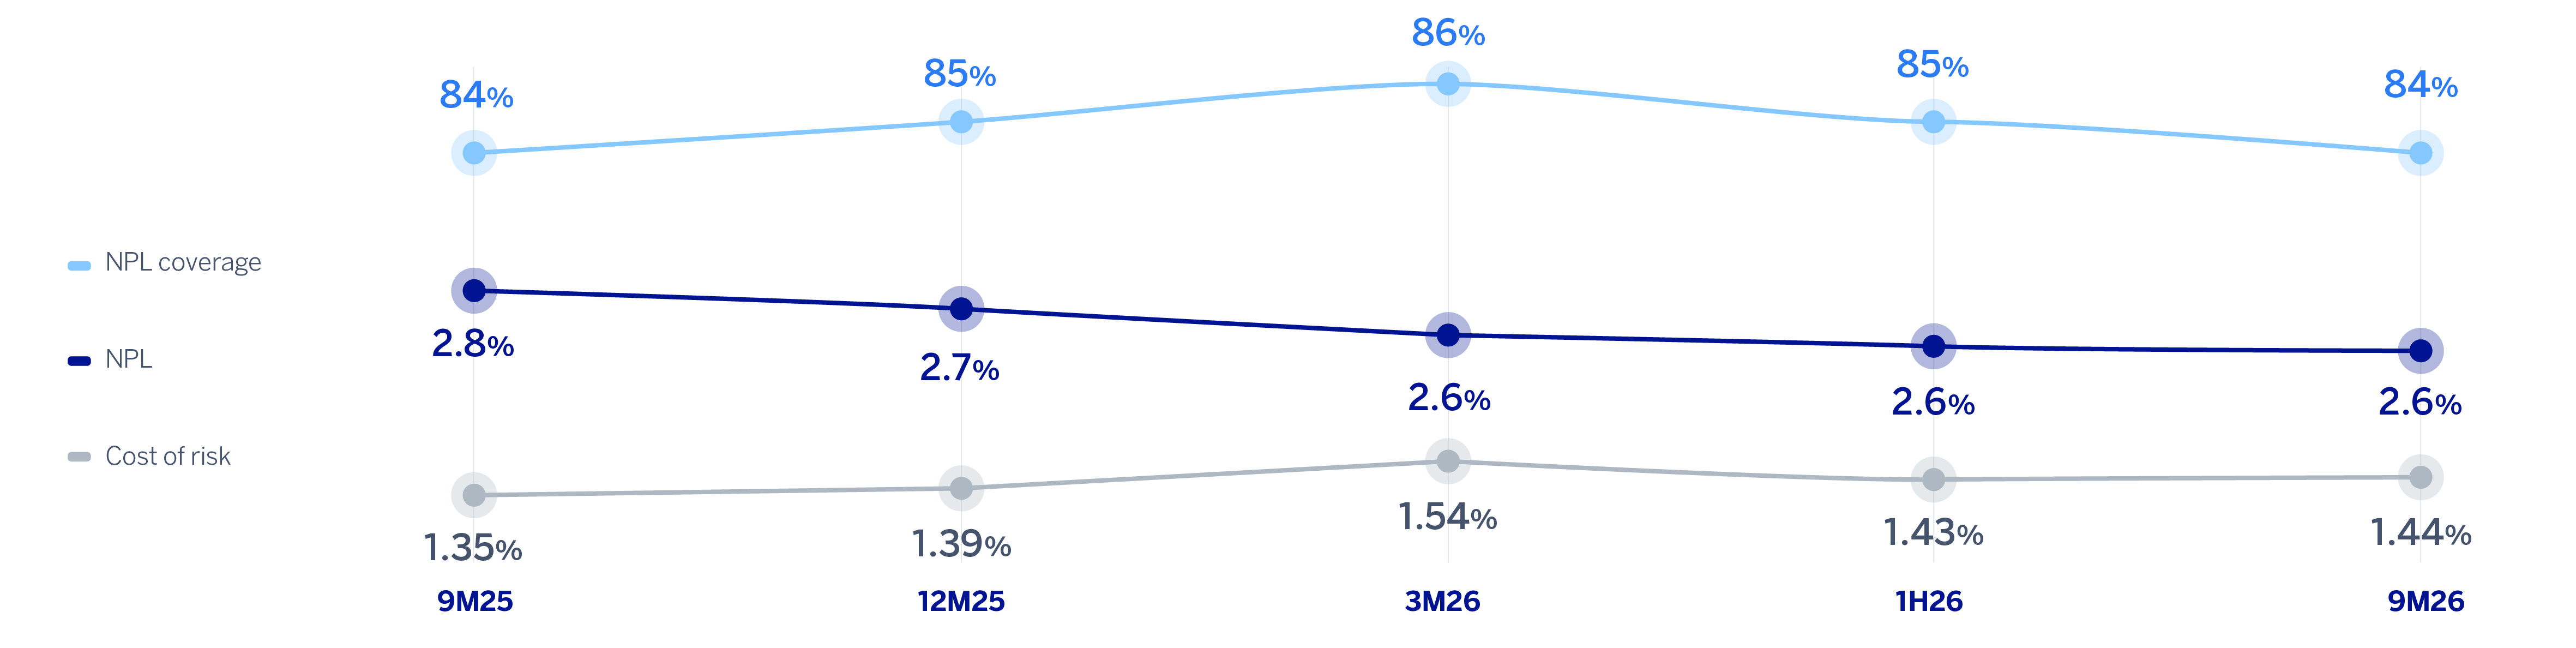
The following chart shows the evolution of the Group's risk metrics from the first nine months of 2025:
NPL AND NPL COVERAGE RATIOS AND COST OF RISK (PERCENTAGE)
The evolution of the Group’s main credit risk indicators is summarized below:
In terms of asset quality, the NPL ratio stood at 2.6% as of September 30, 2026, showing an improvement of 2 basis points compared to the previous quarter, and an improvement of 17 basis points when compared to the end of September 2025, with both comparisons driven by lending growth.
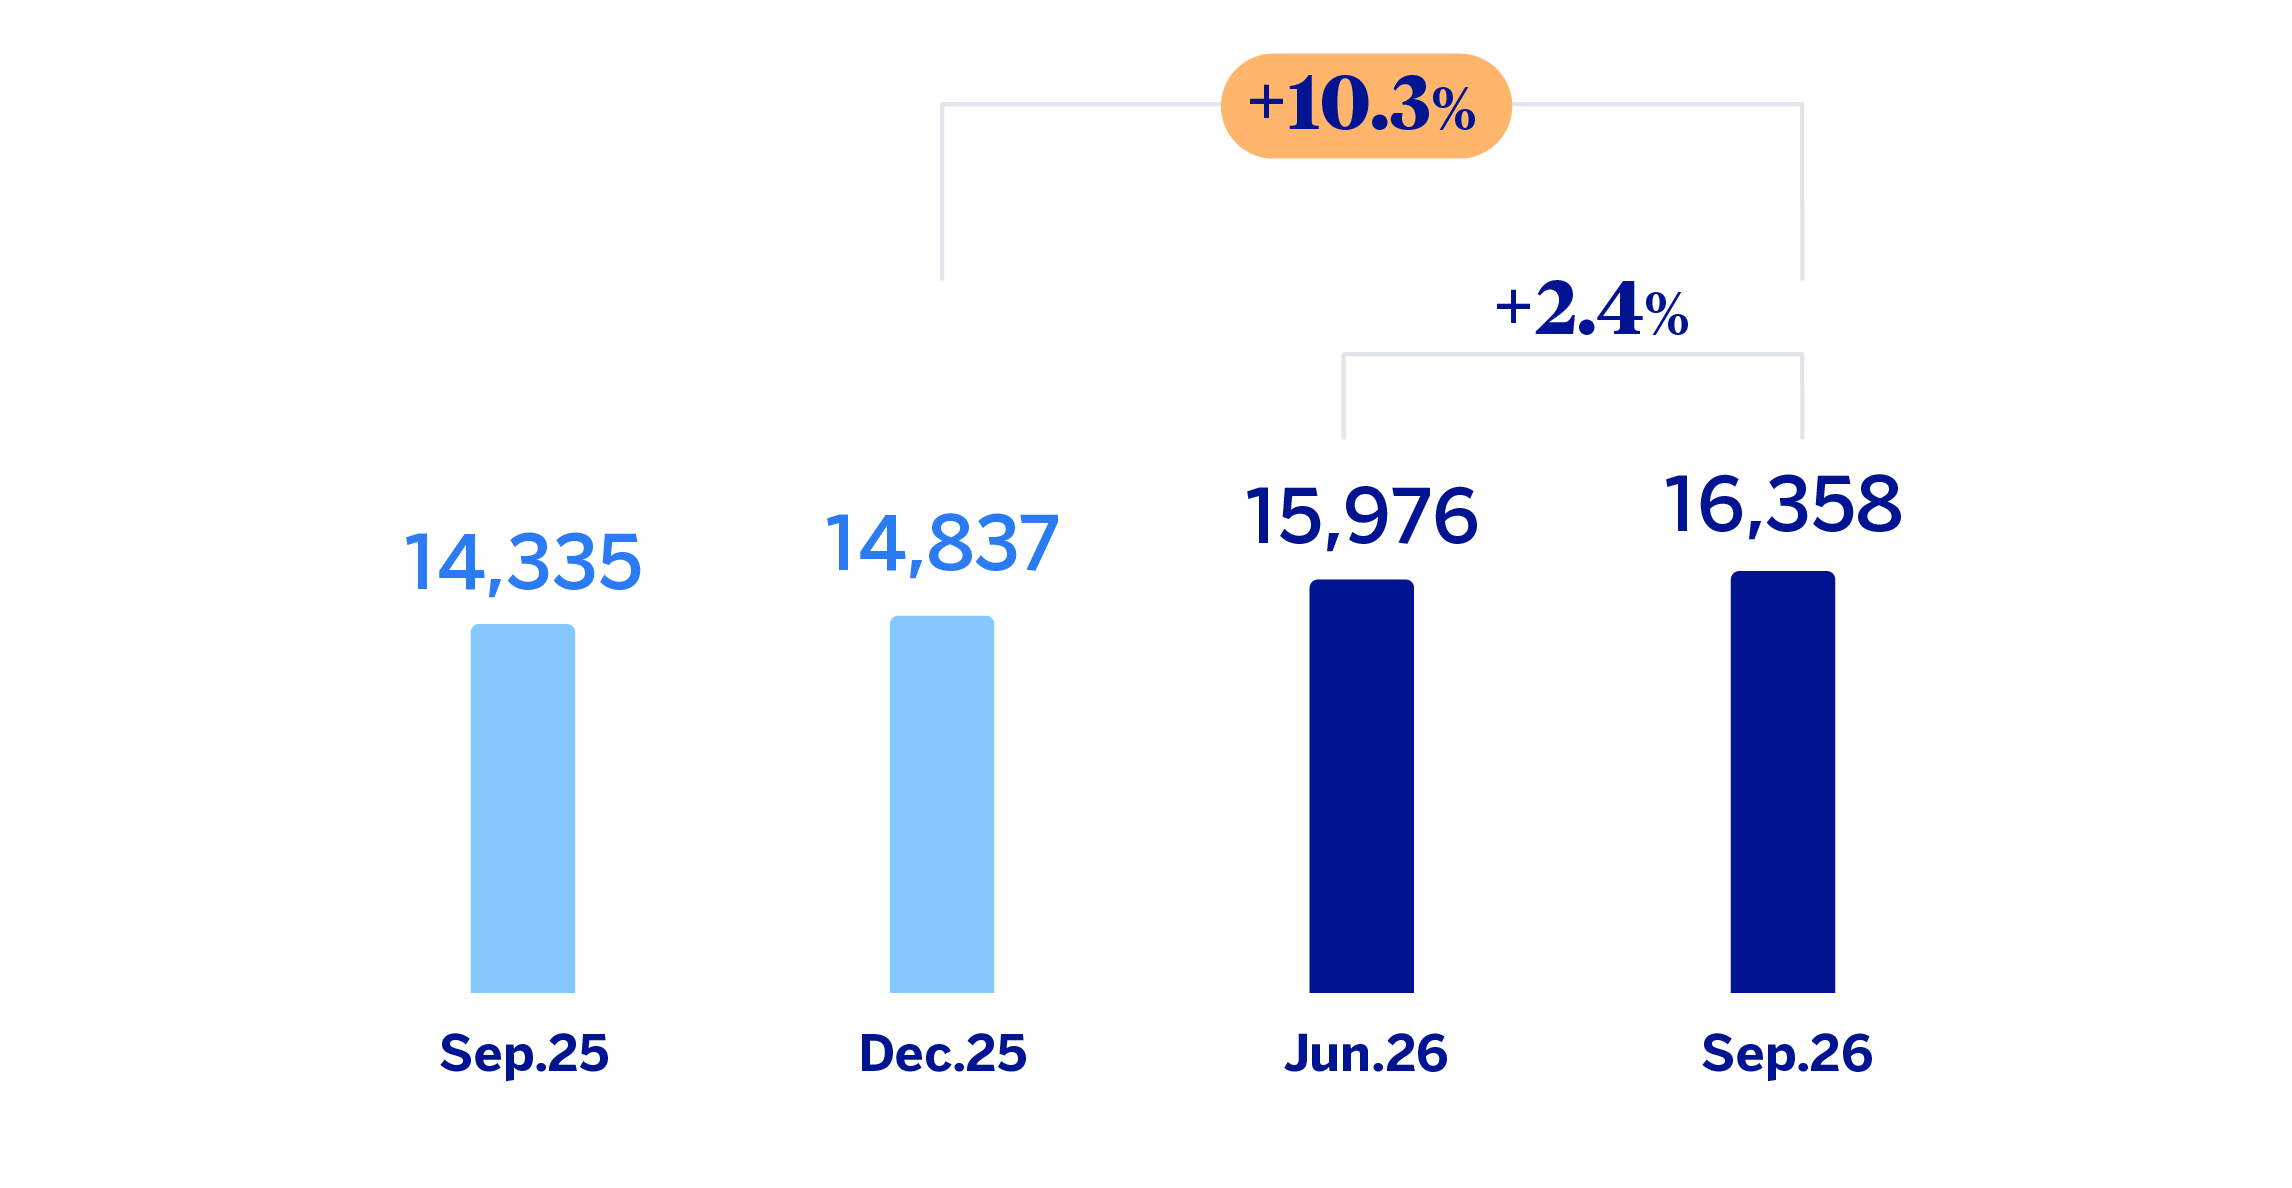
NON-PERFORMING LOANS (MILLIONS OF EUROS)
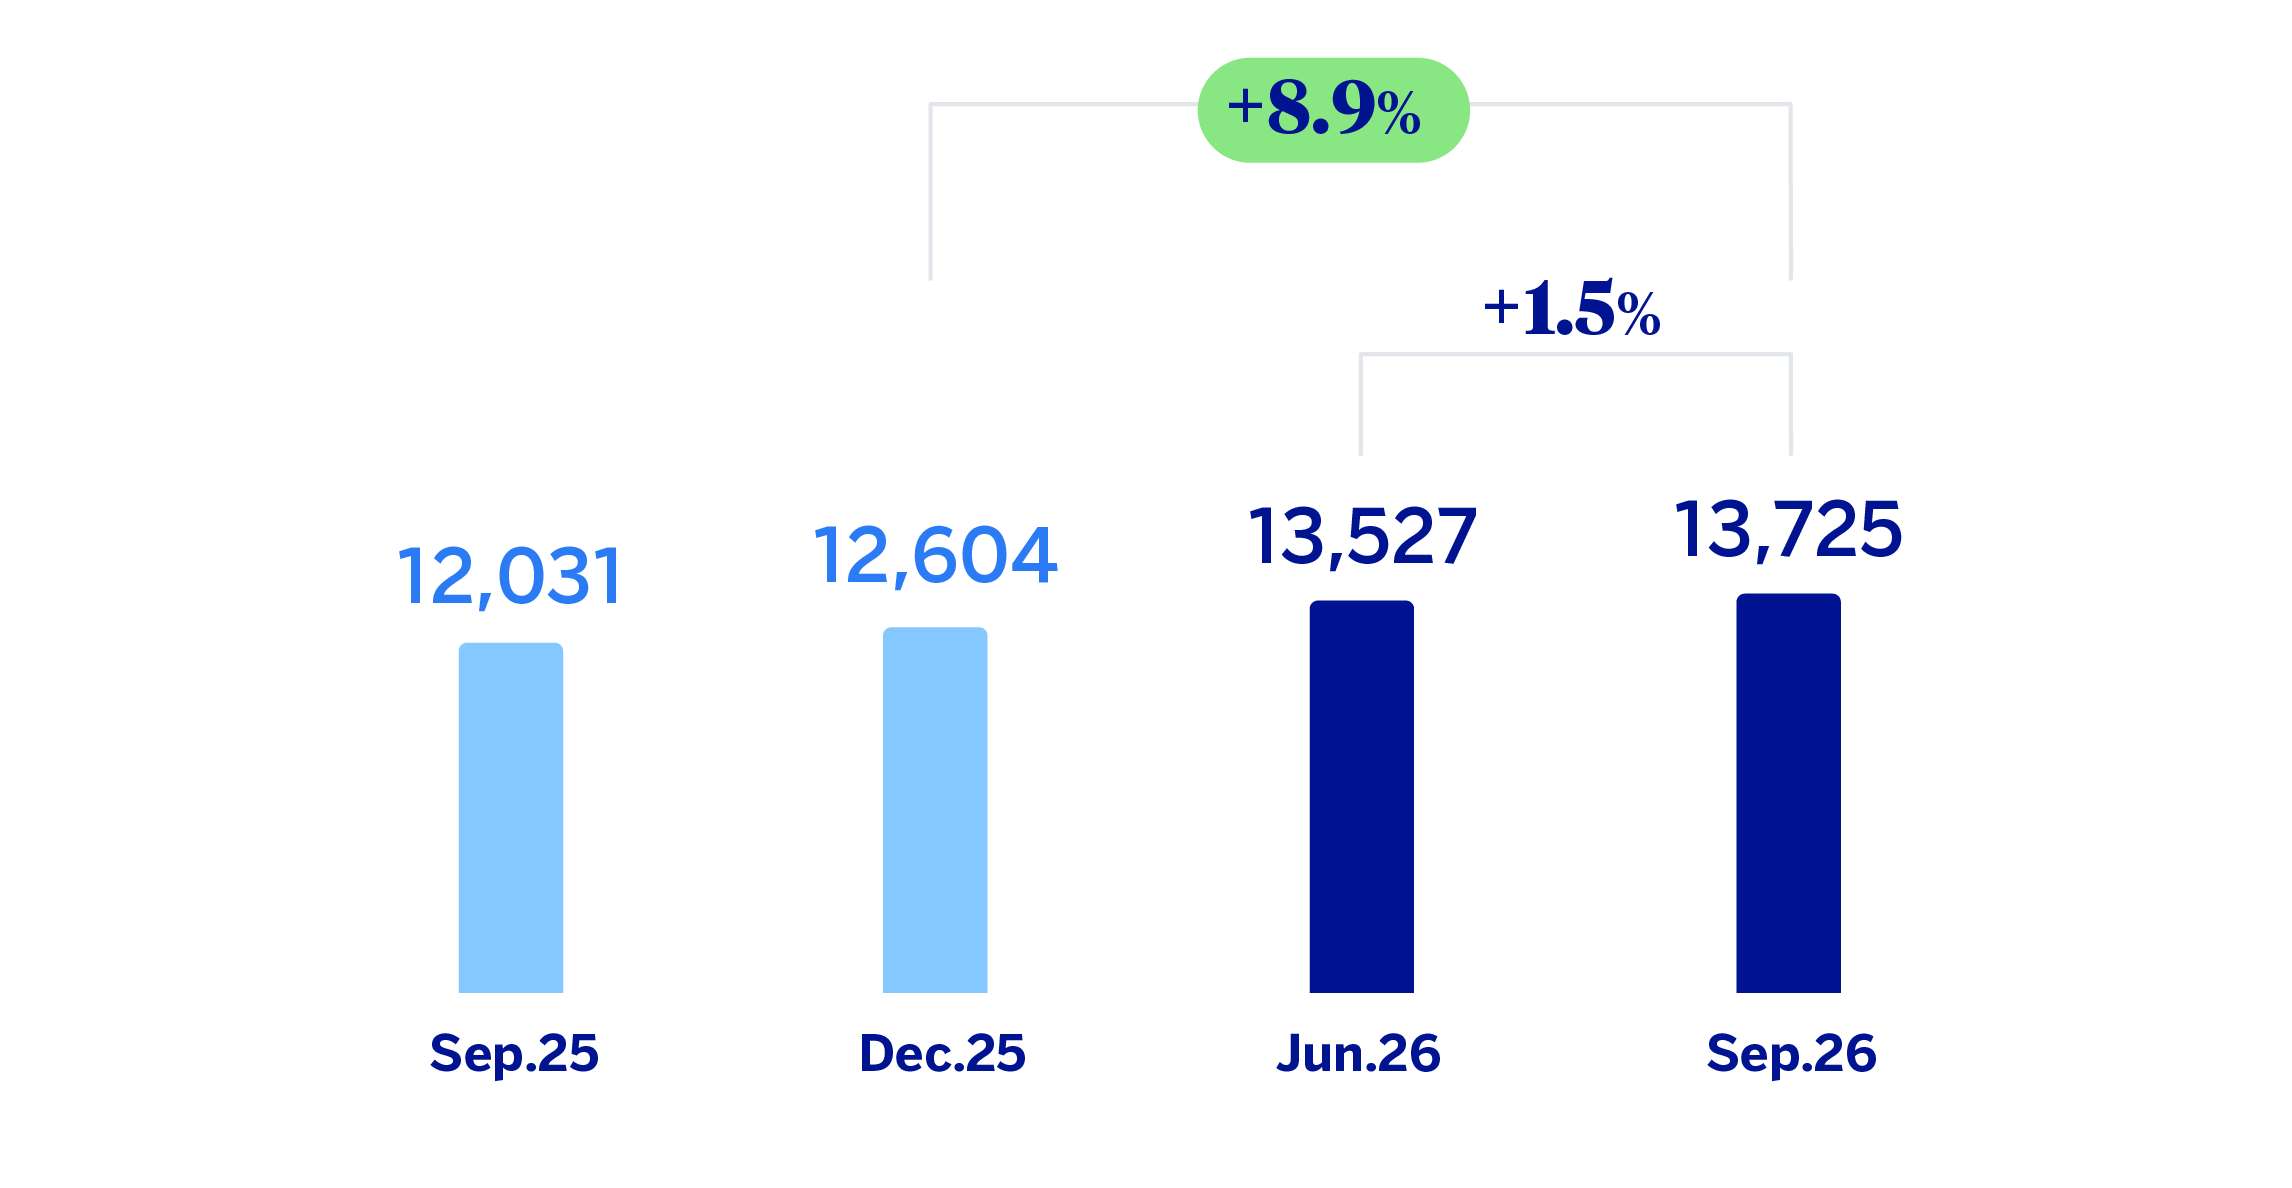
PROVISIONS (MILLIONS OF EUROS)
Credit risk increased by 3.3% in the third quarter of the year, (+4.2% at constant exchange rates), with generalized growth in all business areas except Spain, which remained practically stable due to the typical seasonality of the quarter. In the last twelve months, the growth has exceeded double digits, standing at 21.7% (+20.6% at constant exchange rates), showing greater dynamism than in the same period of 2025.
The balance of non-performing loans increased by 2.4% in the third quarter of 2026 at the Group level, and by 10.3% when compared to the end of December 2025 (+10.1% at constant exchange rates). At constant exchange rates, the quarterly variation stood at 3.8%, with widespread increases except in South America.
The NPL coverage ratio ended September 2026 at 84%, representing a slight decrease compared to the end of the previous year (-106 basis points) and compared to the previous quarter (-77 basis points), while remaining stable compared to the same period of the previous year (-3 basis points).
The cumulative cost of risk as of September 30, 2026 stood at 1.44%, which is 1 basis point above the end of the previous quarter and represents an increase of 5 basis points compared to the cost of risk at the end of 2025.
| CREDIT RISK (1) (MILLIONS OF EUROS) | |||||
|---|---|---|---|---|---|
| 30-09-26 (2) | 30-06-26 (2) | 31-03-26 (2) | 31-12-25 | 30-09-25 | |
| Credit risk | 628,878 | 608,755 | 572,273 | 547,184 | 516,896 |
| Stage 1 | 576,404 | 555,789 | 521,734 | 498,750 | 470,097 |
| Stage 2 | 36,116 | 36,990 | 35,375 | 33,597 | 32,464 |
| Stage 3 (non-performing loans) | 16,358 | 15,976 | 15,163 | 14,837 | 14,335 |
| Provisions | 13,725 | 13,527 | 13,077 | 12,604 | 12,031 |
| Stage 1 | 2,164 | 2,672 | 2,578 | 2,467 | 2,450 |
| Stage 2 | 2,503 | 2,109 | 2,155 | 2,005 | 1,938 |
| Stage 3 (non-performing loans) | 9,058 | 8,747 | 8,343 | 8,133 | 7,643 |
| NPL ratio (%) | 2.6 | 2.6 | 2.6 | 2.7 | 2.8 |
| NPL coverage ratio (%) (3) | 84 | 85 | 86 | 85 | 84 |
| (1) Includes gross loans and advances to customers plus guarantees given. (2) Figures without considering the classification of non-current assets held for sale (NCA&L) reached from the agreement to sell the Romanian subsidiary of Garanti BBVA. (3) The NPL coverage ratio includes the valuation adjustments for credit risk throughout the expected residual life in those financial instruments that have been acquired (mainly originating from the acquisition of Catalunya Banc, S.A.). If these valuation corrections had not been taken into account, the NPL coverage ratio would also have stood at 84% as of September 30, 2026. |
|||||
| NON-PERFORMING LOANS EVOLUTION (MILLIONS OF EUROS) | |||||
|---|---|---|---|---|---|
| 3Q26 (1) (2) | 2Q26 (2) | 1Q26 (2) | 4Q25 | 3Q25 | |
| Beginning balance | 15,976 | 15,163 | 14,837 | 14,335 | 14,621 |
| Entries | 4,077 | 4,094 | 3,359 | 3,450 | 3,600 |
| Recoveries | (1,988) | (2,000) | (1,587) | (1,722) | (1,754) |
| Net variation | 2,089 | 2,094 | 1,771 | 1,729 | 1,846 |
| Write-offs | (1,393) | (1,266) | (1,244) | (1,182) | (1,065) |
| Exchange rate differences and other | (314) | (15) | (201) | (45) | (1,067) |
| Period-end balance | 16,358 | 15,976 | 15,163 | 14,837 | 14,335 |
| Memorandum item: | |||||
| Non-performing loans | 15,904 | 15,521 | 14,709 | 14,346 | 13,813 |
| Non performing guarantees given | 454 | 455 | 455 | 491 | 522 |
| (1) Preliminary data. (2) Figures without considering the classification of non-current assets held for sale (NCA&L) reached from the agreement to sell the Romanian subsidiary of Garanti BBVA. |
|||||
Structural risks
Liquidity and funding
Liquidity and funding management at BBVA is aimed at driving sustained growth of the banking business, through access to a wide variety of alternative sources of funding and assuring optimal term and cost conditions. BBVA's business model, risk appetite framework and funding strategy are designed to ensure a solid funding structure based on stable customer deposits, mainly retail (granular). As a result of this model, a high proportion of deposits is covered by deposit guarantee schemes in each geographical area, close to 50% in Spain and Mexico. It is important to note that, given the nature of BBVA's business, lending is mainly financed through stable customer funds.
One of the key elements in the BBVA Group's liquidity and funding management is the maintenance of large high-quality liquidity buffers in all geographical areas. Thus, the Group has maintained during the last 12 months an average volume of high-quality liquid assets (HQLA) of €132.1 billion, of which 98% corresponded to maximum quality assets (level 1 in the liquidity coverage ratio, LCR).
Due to its subsidiary-based management model, BBVA is one of the few major European banks that follows a Multiple Point of Entry (MPE) resolution strategy: the parent company sets the liquidity policies, but the subsidiaries are self-sufficient and responsible for managing their own liquidity and funding (taking deposits or accessing the market with their own rating). This strategy limits the spread of a liquidity crisis among the Group's different areas and ensures the adequate transmission of the cost of liquidity and financing to the price formation process.
The BBVA Group maintains a solid liquidity position in every geographical area in which it operates, with ratios well above the minimum required:
The LCR requires banks to maintain a volume of high-quality liquid assets sufficient to withstand liquidity stress for 30 days. BBVA Group's consolidated LCR remained comfortably above 100% during the first nine months of 2026 and stood at 143% as of September 30, 2026. It should be noted that, given the MPE nature of BBVA, this ratio limits the numerator of the LCR for subsidiaries of BBVA S.A. to 100% of their net outflows, therefore, the resulting ratio is below that of the individual units (the LCR of the main components was 171% in BBVA, S.A., 153% in Mexico and 152% in Turkey). Without considering this restriction, the Group's LCR ratio was 173%.
The net stable funding ratio (NSFR) requires banks to maintain a stable funding profile in relation to the composition of their assets and off-balance sheet activities. The BBVA Group's NSFR ratio stood at 123% as of September 30, 2026.
The breakdown of these ratios in the main geographical areas in which the Group operates is shown below:
| LCR AND NSFR RATIOS (PERCENTAGE. 30-09-26) | ||||
|---|---|---|---|---|
| BBVA, S.A. | Mexico | Turkey (1) | South America | |
| LCR | 171 | 153 | 152 | All countries >100 |
| NSFR | 114 | 127 | 142 | All countries >100 |
| (1) Garanti Bank only. | ||||
During the first nine months of 2026, the conflict in Iran has continued to generate volatility and disruptions in energy supply, intensifying inflationary pressures and risks to economic growth. Against this backdrop, central banks adopted a more restrictive monetary policy stance, driving an uptick in sovereign bond yields.
In this context, BBVA maintains an adequate liquidity position across its different geographical areas, with no significant tensions observed. As shown previously, the main liquidity indicators (LCR, NSFR, and internal metrics) remain above regulatory thresholds, albeit with varying levels of headroom. Likewise, active balance sheet management and the diversification of funding sources contribute to preserving the Group's liquidity position and its capacity to respond to adverse scenarios.
Apart from the above, the most relevant aspects related to the main geographical areas are the following:
BBVA, S.A. has maintained a strong position with a large high-quality liquidity buffer, maintaining at all times the regulatory liquidity metrics well above the set minimums. During the first nine months of 2026, significant growth has been observed in lending activity, driven primarily by the wholesale segment, in an environment of a more moderate growth in deposits. This development has not put pressure on the liquidity position.
BBVA Mexico continues to show a solid liquidity situation, despite the widening of the credit gap in the first nine months of the year due to the strength of lending, in both local and foreign currency.
In Turkey, Garanti BBVA maintained an adequate liquidity situation in the first nine months of 2026. The local currency credit gap has deteriorated due to loan growth outpacing deposit gathering. On the other hand, an improvement in the foreign currency credit gap has been observed thanks to the increase in deposits.
In South America, the liquidity situation has also remained adequate throughout the region in the first nine months of 2026. BBVA Argentina maintains a solid liquidity position with an improvement in local currency credit gap thanks to the positive performance in deposits, despite a slight deterioration in the foreign currency gap. In BBVA Colombia, the liquidity situation remains stable with a narrowing credit gap, and deposit growth outpaced lending. In BBVA Peru, the liquidity position remains solid, with an improved credit gap thanks mainly to the good performance of retail deposits.
On the following page, the main wholesale financing transactions carried out by the BBVA Group during the first nine months of 2026 are detailed.
| Issuer | Type of issue | Date of issue | Nominal (millions) | Currency | Equivalent in euros (1) | Coupon | Maturity Date |
| BBVA, S.A. | Senior non-preferred | Jan-26 | 1,250 | EUR | 1,250 | 3.750% | Jan-36 |
| Jan-26 | 750 | EUR | 750 | Euribor 3m+55 bps | Jan-29 | ||
| Mar-26 | 1,000 | USD | 881 | 4.150% | Mar-29 | ||
| Mar-26 | 1,000 | USD | 881 | 5.127% | Mar-36 | ||
| Mar-26 | 500 | USD | 440 | SOFR+88 bps | Mar-29 | ||
| AT1 (2) | May-26 | 1,000 | USD | 881 | 7.125% | Perpetual | |
| Senior non-preferred | May-26 | 1,250 | USD | 1,101 | 4.968% | May-31 | |
| Covered bond (3) | Jun-26 | 1,000 | EUR | 1,000 | 3.125% | Jun-33 | |
| Jun-26 | 1,250 | EUR | 1,250 | 2.875% | Jun-29 | ||
| Senior non-preferred | Jun-26 | 1,250 | EUR | 1,250 | 3.375% | Jun-31 | |
| Senior non-preferred | Sep-26 | 1,000 | USD | 881 | 4.977% | Sep-29 | |
| Sep-26 | 300 | USD | 264 | SOFR+89 bps | Sep-29 | ||
| Sep-26 | 1,000 | USD | 881 | 5.244% | Sep-31 | ||
| Senior preferred | Sep-26 | 1,250 | EUR | 1,250 | 4.125% | Sep-33 | |
| Senior non-preferred (4) | Sep-26 | 600 | GBP | 702 | 5.750% | Sep-32 | |
| BBVA Mexico | Senior | Feb-26 | 8,876 | MXN | 431 | 9.260% | Jan-36 |
| Feb-26 | 6,124 | MXN | 298 | TIIE+32 bps | Jul-29 | ||
| Feb-26 | 16 | USD | 14 | 4.190% | Sep-28 | ||
| Jun-26 | 1,000 | USD | 881 | 5.400% | Jun-31 | ||
| Senior (5) | Jul-26 | 15,000 | MXN | 729 | TIIE+41 bps | Jul-31 | |
| Subordinated debt (6) | Oct-26 | 1,000 | USD | 881 | 8.350% | Apr-42 | |
| Garanti BBVA | Senior Debt MTNs (Medium term notes) | Several | 2,334 | EUR | 2,334 | Several | Several |
| Syndicated loans | Several | 66 | EUR | 66 | Several | Several | |
| Several | 225 | USD | 199 | Several | Several | ||
| Tier 2 | Ago-26 | 125 | USD | 110 | SOFR+380 bps | Ago-31 | |
| BBVA Argentina | Senior Debt | Several | 245 | USD | 215 | Several | Several |
| Several | 290,669 | ARS | 167 | Several | Several | ||
| BBVA Peru | Tier 2 (7) | Mar-26 | 300 | PEN | 77 | 6.750% | Mar-38 |
| Tier 2 (8) | Sep-26 | 350 | PEN | 90 | 7.060% | Sep-38 | |
| (1) Equivalent in euros at the closing exchange rate of the period. (2) First Reset Date in May 2033. (3) Issue of mortgage-covered bonds. (4) First Reset Date in September 2031. (5) Secured senior debt obtained from Sociedad Hipotecaria Federal (SHF), backed by a portfolio of mortgages (6) First Reset Date in October 2036. (7) First Reset Date in March 2033. (8) First Reset Date in September 2033. |
|||||||
During the first nine months of 2026, BBVA, S.A. carried out the early redemption of four issuances. First, on January 15, 2026, it carried out the early redemption of a green AT1 issuance made on July 15, 2020, for a combined nominal amount of €1 billion. Likewise, on March 24, 2026, BBVA, S.A. carried out the early redemption of a senior preferred bond issuance originally issued on March 24, 2021, for a total aggregate nominal amount of €1 billion. On July 15, 2026, the early redemption of a subordinated bond issuance was carried out for a combined nominal amount of 300 million pounds sterling, and on September 22, it carried out the full early redemption of the public sector covered bond issuance made in March 2022 for an aggregate nominal amount of €540 million.
Foreign exchange
Exchange rate risk management aims to reduce the sensitivity of capital ratios to currency fluctuations, as well as the volatility of net attributable profit resulting from such movements.
During the third quarter of 2026, the Group's main currencies showed an uneven performance against the euro. Given its relevance to the Group, the performance of the Mexican peso is particularly noteworthy, depreciating by 3.3% against the euro. In the case of the US dollar, the currency registered a moderate appreciation of 0.3% against the euro. For its part, the Turkish lira and the Argentine peso depreciated by 4.5% and 2.5%, respectively, against the euro (although, in real terms, both currencies registered an appreciation against the euro). Regarding currencies of the main countries in South America, the performance was also mixed: the Peruvian sol depreciated by 0.5% and the Chilean peso likewise depreciated by 4.6%, while the Colombian peso appreciated by 3.4% against the euro.
| EXCHANGE RATES | |||||||
|---|---|---|---|---|---|---|---|
| Period-end exchange rates | Average exchange rates | ||||||
| Currency/Euro 30-09-26 | 𝚫 % of the currency against 30-06-26 | 𝚫 % of the currency against 30-09-25 | 𝚫 % of the currency against 31-12-25 | Currency/Euro Jan.-Sep.26 | 𝚫 % of the currency against Jan.-Sep.25 |
||
| U.S. dollar | 1.1355 | 0.3 | 3.4 | 3.5 | 1.1611 | (3.6) | |
| Mexican peso | 20.5816 | (3.3) | 4.6 | 2.6 | 20.2017 | 7.9 | |
| Turkish lira (1) | 55.6596 | (4.5) | (12.3) | (9.3) | — | — | |
| Peruvian sol | 3.9082 | (0.5) | 4.5 | 1.0 | 3.9441 | 2.8 | |
| Argentine peso (1) | 1,730.47 | (2.5) | (9.0) | (0.9) | — | — | |
| Chilean peso | 1,101.96 | (4.6) | 2.4 | (3.3) | 1,052.20 | 1.7 | |
| Colombian peso | 3,793.97 | 3.4 | 20.7 | 16.4 | 4,061.94 | 13.7 | |
| (1) According to IAS 21 "The effects of changes in foreign exchange rates", the year-end exchange rate is used for the conversion of the Turkey and Argentina income statement. | |||||||
In relation to the hedging of capital ratios, BBVA aims to hedge between 50% and 70% of the capital excess of the currencies of its main subsidiaries. The sensitivity of the Group's CET1 ratio to 10% depreciations in major currencies is estimated at: +13 basis points for the U.S. dollar, -13 basis points for the Mexican peso and -3 basis points for the Turkish lira13. With regard to the hedging of results, BBVA hedges between 40% and 50% of the aggregate net attributable profit it expects to generate in the next 12 months. For each currency, the final amount hedged depends, among other factors, on its expected future evolution, the costs and the relevance of the income related to the Group's results as a whole.
Interest rate
Interest rate risk management seeks to limit the impact that BBVA may suffer, both in terms of results (short-term) and economic value (long-term), from adverse movements in the interest rate curves in the various currencies in which the Group operates. BBVA carries out this work through an internal procedure, pursuant to the guidelines established by the European Banking Authority (EBA), with the aim of analyzing the potential impact that could derive from a range of scenarios on the Group's different balance sheets.
Risk measurement is based on assumptions intended to realistically mimic the behavior of the balance sheet. The assumptions regarding the behavior of accounts with no explicit maturity and prepayment estimates are especially relevant. These assumptions are reviewed and adapted, at least once a year according to the evolution in observed behaviors.
At the aggregate level, BBVA continues to maintain a moderate risk profile in line with the target set in the changing interest rate cycle environment preserving positive sensitivity to interest rate rises in net interest income.
The first nine months of 2026 have been marked by the conflict in Iran and its repercussions on energy markets. Following the initial volatility, the persistence of oil prices at high levels has intensified inflationary pressures and conditioned expectations regarding the evolution of monetary policy. In this context, financial markets have priced in expectations of further monetary tightening, anticipating hikes in official reference interest rates, some of which have already materialized across different geographical areas. This dynamic has translated into a global rebound in yields across interest rate curves in the third quarter of the year. In this respect, the valuation of ALCO14 portfolios has shown a negative performance so far this year.
By geographical areas:
Spain has a balance sheet characterized by a lending portfolio with a high proportion of variable-rate loans (mortgages and corporate lending) and liabilities composed mainly by customer demand deposits. The ALCO portfolio acts as a management lever and hedge for the balance sheet, mitigating its sensitivity to interest rate fluctuations. The exposure of the net interest income to movements in interest rates remains limited. In June 2026, the ECB carried out its first interest rate hike in three years, with an increase of 25 basis points, and an additional hike in September that brought the reference interest rate in the eurozone to 2.65%, the rate on the deposit facility at 2.50% and the rate on the marginal lending facility at 2.90% at the end of September 2026.
Mexico continues to show a balance between fixed and variable interest rates balances, which results in a limited sensitivity to interest rates fluctuations. Among the assets that are most sensitive to interest rate changes, the commercial portfolio stands out, while consumer and mortgage portfolios are mostly at a fixed rate. With regard to customer funds, the high proportion of non-interest-bearing deposits, which are insensitive to interest rate movements, should be highlighted. The ALCO portfolio is invested primarily in fixed-rate sovereign bonds. The monetary policy rate stood at 6.50% at the end of September 2026, 50 basis points below the year-end level for 2025, and the central bank is expected to leave it unchanged through the end of 2027.
In Turkey, the sensitivity of net interest income to rates remains limited in both local and foreign currencies, thanks to the bank's management. The Central Bank of the Republic of Turkey (CBRT) continued its monetary easing process at the beginning of the year, supported by improved inflation, reducing the monetary policy rate by 100 basis points to 37.0% in January 2026, the level at which it remained as of the end of September. However, the outbreak of the conflict in Iran led the institution to temporarily increase (until August 2026) the effective cost of financing toward the upper limit of its corridor (40%) in response to geopolitical tensions and their inflationary impact. At its October meeting, the CBRT resumed rate cuts, with a 100 basis point reduction that brought the monetary policy rate down to 36.0%.
In South America, the sensitivity of net interest income continues to be limited, since most of the countries in the area have a balanced fixed/variable composition between assets and liabilities. In addition, in balance sheets with several currencies, the interest rate risk is managed for each of the currencies, showing a very low level of exposure. Regarding benchmark interest rates, in Argentina, the central bank abandoned the official interest rate as a monetary anchor and began to regulate the monetary base using other tools such as setting reserve requirements or intervening in the foreign exchange market for its management. In Colombia, the reference rate stood at 12.25% at the end of September 2026, 300 basis points above the end of 2025, with an increase of 25 basis points in the third quarter of 2026, a level at which it is expected to remain until the end of next year, when the first rate cuts could take place. In Peru, the official monetary policy rate closed September 2026 at 4.25%, unchanged with respect to the end of the previous year.
| INTEREST RATES (PERCENTAGE) | |||||
|---|---|---|---|---|---|
| 30-09-26 | 30-06-26 | 31-03-26 | 31-12-25 | 30-09-25 | |
| Official ECB rate (1) | 2.50 | 2.25 | 2.00 | 2.00 | 2.00 |
| Euribor 3 months (2) | 2.64 | 2.34 | 2.11 | 2.05 | 2.03 |
| Euribor 1 year (2) | 3.25 | 2.80 | 2.57 | 2.27 | 2.17 |
| USA Federal rates | 4.00 | 3.75 | 3.75 | 3.75 | 4.25 |
| Banxico official rate (Mexico) | 6.50 | 6.50 | 6.75 | 7.00 | 7.50 |
| CBRT (Turkey) | 37.00 | 37.00 | 37.00 | 38.00 | 40.50 |
| (1) Deposit facility. (2) Calculated as the month average. |
|||||
13 This sensitivity does not include the cost of capital hedges, which are currently estimated at 1 basis point per quarter for Mexican peso and 1 basis point per quarter for Turkish lira.
14 Structural portfolio managed by the Asset and Liability Committee, designed to mitigate the sensitivity of the balance sheet to interest rate movements.
Read legal disclaimer of this report.