Report 3Q 2026
BBVA Exceeds €9 Billion in Profit in the First Nine Months of 2026 and Increases Lending by 20 Percent Year-on-Year
The share
The global economy has maintained relatively solid growth during the third quarter of 2026, despite the persistence of geopolitical tensions, rising energy costs due to the prolongation of conflicts in the Middle East, and the increase in long-term sovereign yields. Investment linked to artificial intelligence, defense spending, and fiscal stimulus have continued to cushion the effect of these factors. BBVA Research leaves its global growth forecast for 2026 unchanged at 3.1%, and places it at 3.3% for 2027.
The relatively good performance of the US economy and the greater dynamism of the Eurozone explain the resilience of global growth in the third quarter. In particular, the expected GDP growth for the United States stands at 2.4% in 2026, the same forecast as in the previous scenario, and at 2.2% for the following year, supported by still solid domestic demand and investment in artificial intelligence. For the Eurozone, BBVA Research raises expected economic growth for 2026 by two-tenths of a percentage point, to 0.9%, and places it at 1.2% for 2027, to the extent that the increase in energy and financing costs is partially offset by a weaker euro. In China, the GDP growth forecast remains at 4.5% for 2026 and 4.2% for 2027, in a context of structural slowdown led by the adjustment in the real estate sector.
For its part, the resilience of demand and the maintenance of commodity prices at relatively high levels will limit the correction of inflation in the short term. In the United States, headline inflation could end 2026 slightly above 3%, leaving the annual average at around 3.3%. In the Eurozone inflation could exceed 3.5% by year-end (the annual average would be around 3%). In both economies, a progressive reduction in inflation is expected during 2027 toward average levels of 2.5%, under the assumption of a gradual moderation in energy prices. In this environment, the United States Federal Reserve and the European Central Bank have raised their reference rates. BBVA Research anticipates additional hikes before the end of 2026, up to 4.25% and 2.75%, respectively, and expects them to remain at these levels during 2027. In China, where inflation remains very contained, monetary conditions will continue to be accommodative, with reference rates at levels similar to those of 2025.
The balance of risks for the global economy remains tilted to the downside, given the uncertainty regarding the resolution of conflicts in the Middle East and Ukraine, the restoration of trade in the affected areas, and the performance of energy input prices. Added to this are doubts about the sustainability of public debt in several developed economies, tensions in sovereign debt yields, and the effects of protectionist measures in the areas of trade and immigration. The occurrence of extreme weather events, as well as a potential reactivation of the threat of interventionist actions by the US administration, also constitute sources of risk. Conversely, a faster normalization of energy markets and a greater impact of artificial intelligence on the productivity of the economies actively promoting its adoption are worth mentioning.
The main indexes have shown a flat performance during the third quarter of 2026. In Europe, the Stoxx Europe 600 index declined by -1.1% compared to the end of June 2026, and in Spain the Ibex 35 decreased by -0.2% in the same period, showing a better relative performance. In the United States, the S&P 500 index increased by 2.0%.
With regard to the banking sector indexes, the performance in the third quarter of 2026 was better than the general indexes in Europe. The Stoxx Europe 600 Banks index, which includes the banks in the United Kingdom, and the Euro Stoxx Banks, an index of Eurozone banks, increased by 5.6% and 5.8% respectively, while in the United States, the S&P Regional Banks sector index decreased by -7.3% in the period.
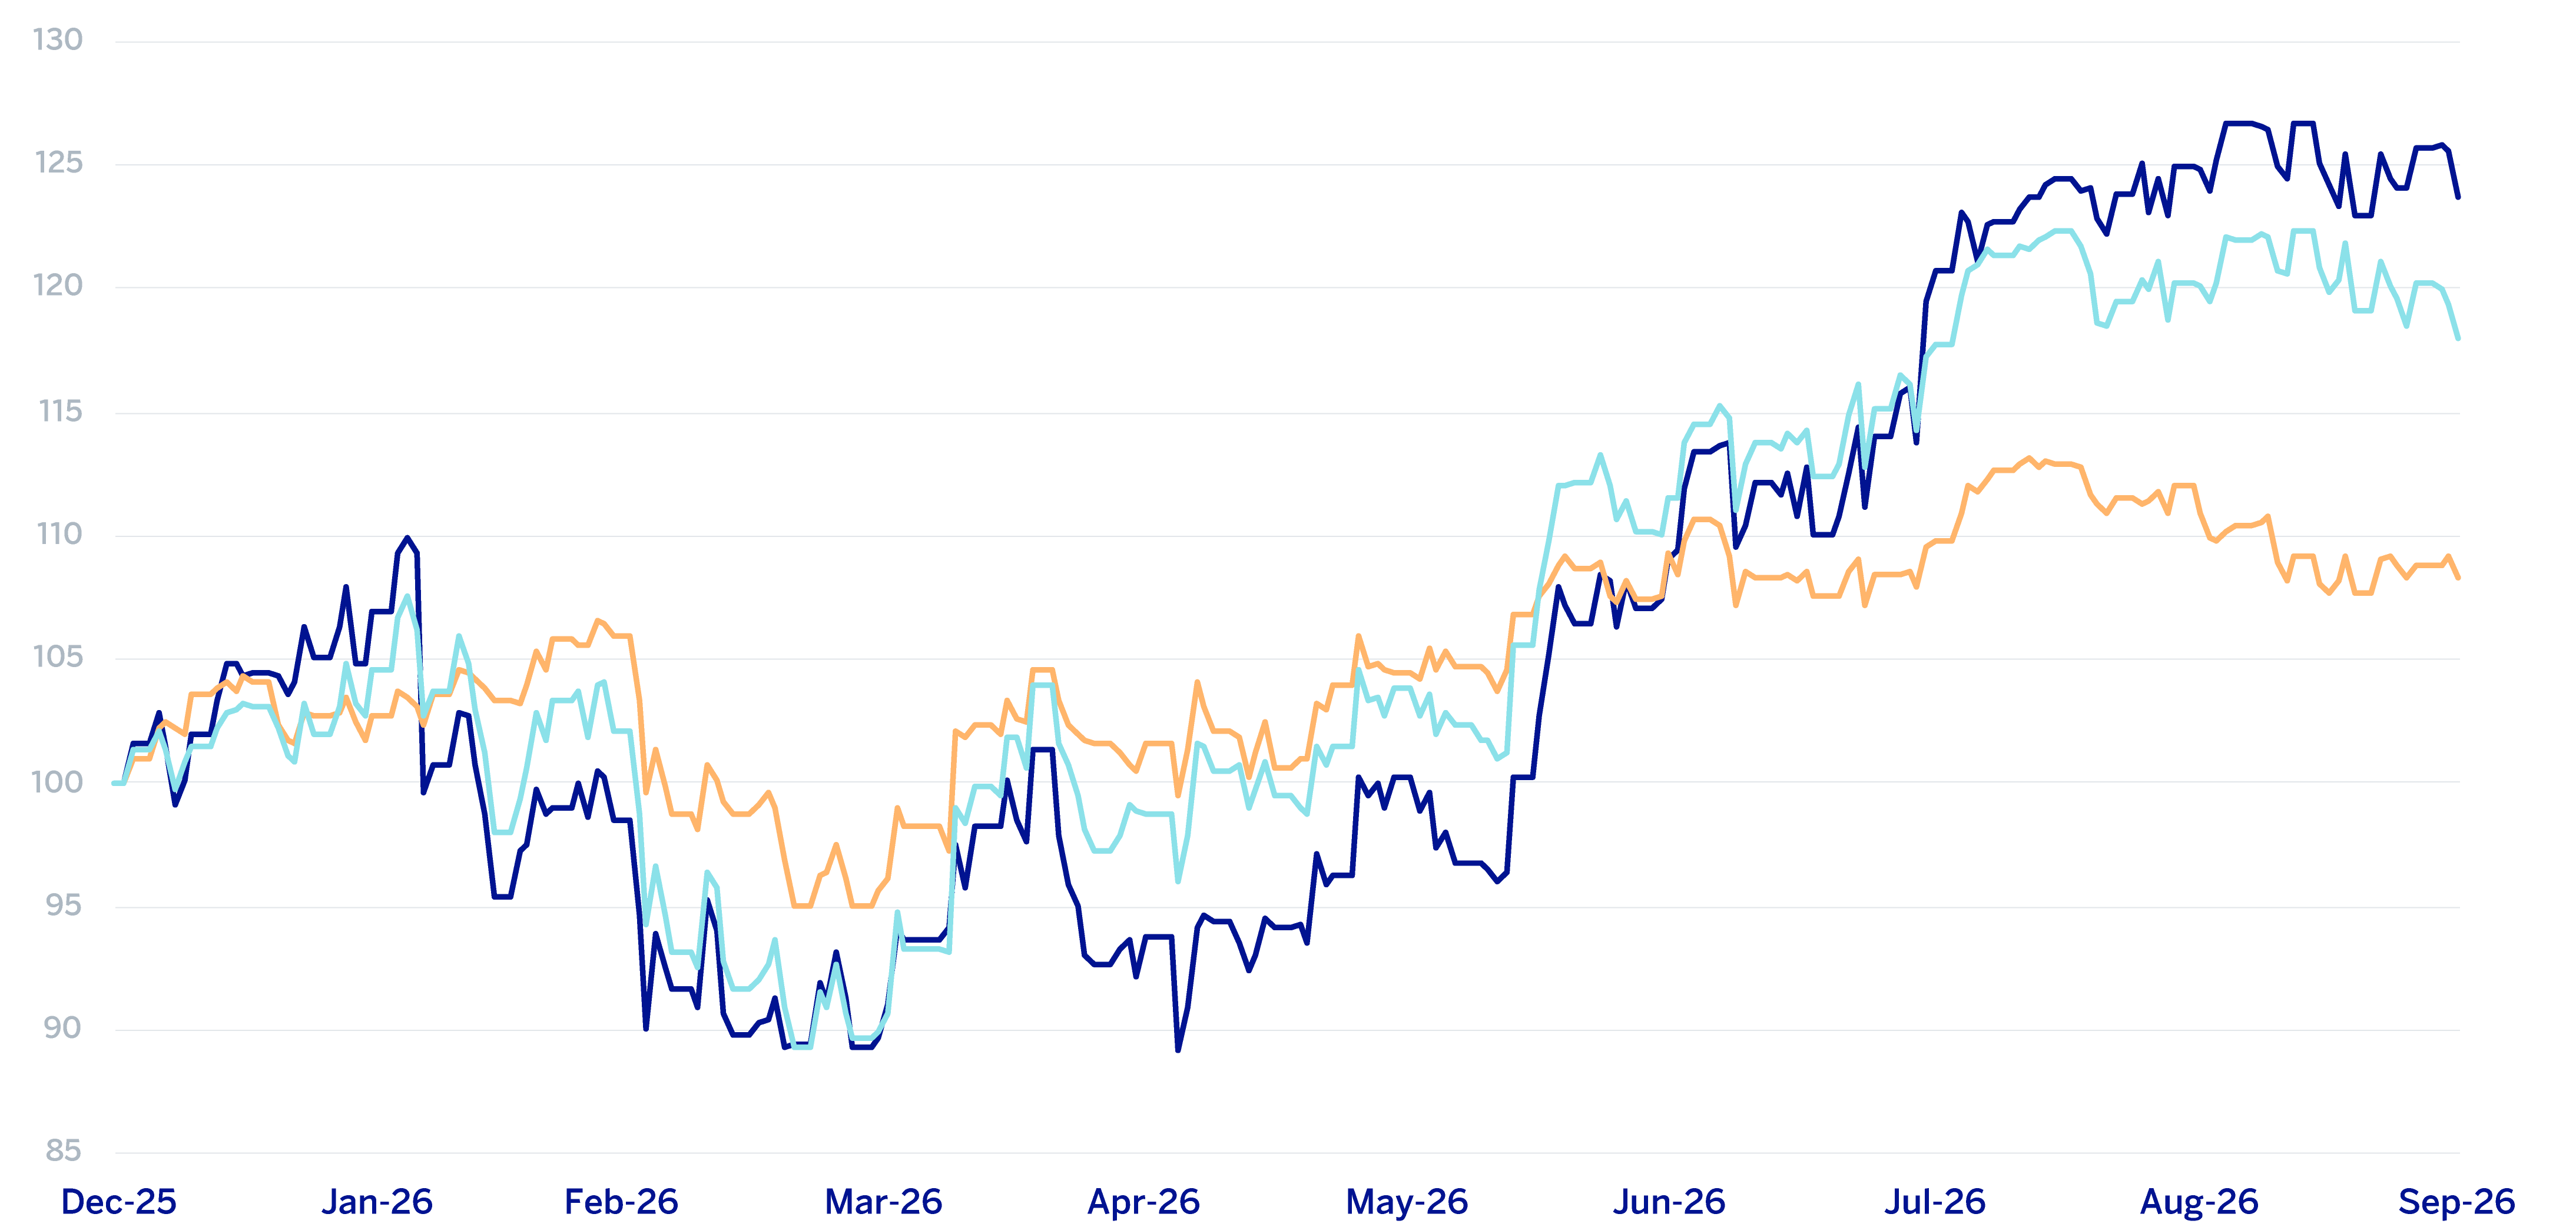
BBVA’s share price increased by 13.4% during the quarter, outperforming its sector index, closing the month of September 2026 at €24.81.
BBVA share evolution
Compared with European indexes (base indice 100=31-12-25)
BBVA
Eurostoxx-50
Eurostoxx Banks
| THE BBVA SHARE AND SHARE PERFORMANCE RATIOS | ||
|---|---|---|
| 30/09/2026 | 30/06/2026 | |
| Number of shareholders | 648,520 | 655,706 |
| Number of shares issued (millions) | 5,511 | 5,581 |
| Closing price (euros) | 24.81 | 21.87 |
| Book value per share (euros) (1) | 10.54 | 10.71 |
| Tangible book value per share (euros) (1) | 9.95 | 10.14 |
| Market capitalization (millions of euros) | 136,725 | 122,061 |
| (1) For more information, see Alternative Performance Measures at the end of the quarterly report. | ||
The shareholder remuneration policy contemplates that cash distributions may be combined with share buybacks, all subject to the authorization and approvals applicable at any given time1.
Regarding cash distribution, the Annual General Shareholders' Meeting of BBVA held on March 20, 2026, approved, under item 1.3 of the Agenda, a cash distribution against the 2025 results as a final dividend for the 2025 financial year, for an amount equal to €0.60 gross per outstanding BBVA share entitled to participate in this distribution, which was paid on April 10, 2026. Thus, the total amount of cash distributions for the 2025 financial year, taking into account that in November 2025 a gross amount of €0.32 per share was distributed, stood at €0.92 gross per share.
Likewise, the BBVA Board of Directors agreed on the payment of a cash interim dividend against 2026 earnings in the gross amount of €0.37 (€0.2997 net of applicable withholding tax) for each outstanding share entitled to participate in said distribution, which was paid on October 15, 2026.
The 2026 share buyback programs comprise an extraordinary program for almost €4 billion, executed in several tranches between December 2025 and August 3, 2026. Added to this a new extraordinary share buyback program amounting to €2 billion, structured into two tranches of €1 billion each. The first of these tranches was executed between August 5 and October 1, 2026, while the execution of the second began on October 14, 2026.
On September 30, 2026, the number of BBVA shares outstanding was 5,511 million. The number of shareholders reached 648,520 and, by type of investor, 68.14% of the capital belonged to institutional investors and the remaining 31.86% was in the hands of retail shareholders.
BBVA shares are included on the main stock market indexes. At the closing of September 2026, the weighting of BBVA shares in the Ibex 35, Euro Stoxx 50 and the Stoxx Europe 600 index, were 13.73%, 3.09% and 1.05%, respectively. They are also included on several sector indexes, including Stoxx Europe 600 Banks, which includes the United Kingdom, with a weighting of 6.5% and the Euro Stoxx Banks index for the eurozone with a weighting of 10.4%. Moreover BBVA maintains a significant presence on a number of international sustainability indexes, such as, Dow Jones Sustainability Index (DJSI), FTSE4Good or MSCI ESG Indexes.
1 For further information, please refer to the "Share buyback programs" section in the "Capital and shareholders" chapter of the quarterly report.
Group's information
- 2025-2029 Strategic Plan
- Results
- Balance sheet and business activity
- Solvency
- Sustainability
In the first nine months of 2026, the BBVA Group has continued to make progress in executing its 2025-2029 Strategic Plan, with the ambition of leading the banking of the future. The objective is to radically embed a customer-centric perspective, as well as to drive and strengthen the Group's commitment to growth and value creation.
Artificial intelligence is a key lever for accelerating the Group's transformation and amplifying the impact of all strategic priorities. In this regard, BBVA is driving its cross-cutting integration across the entire organization through The Eight, the artificial intelligence transformation agenda, to evolve toward a more personalized and proactive relationship with customers, redesign and streamline processes, and enhance employee capabilities. Furthermore, BBVA is developing The Frame, a common operating model that enables scaling the deployment of artificial intelligence solutions and agents safely and efficiently.
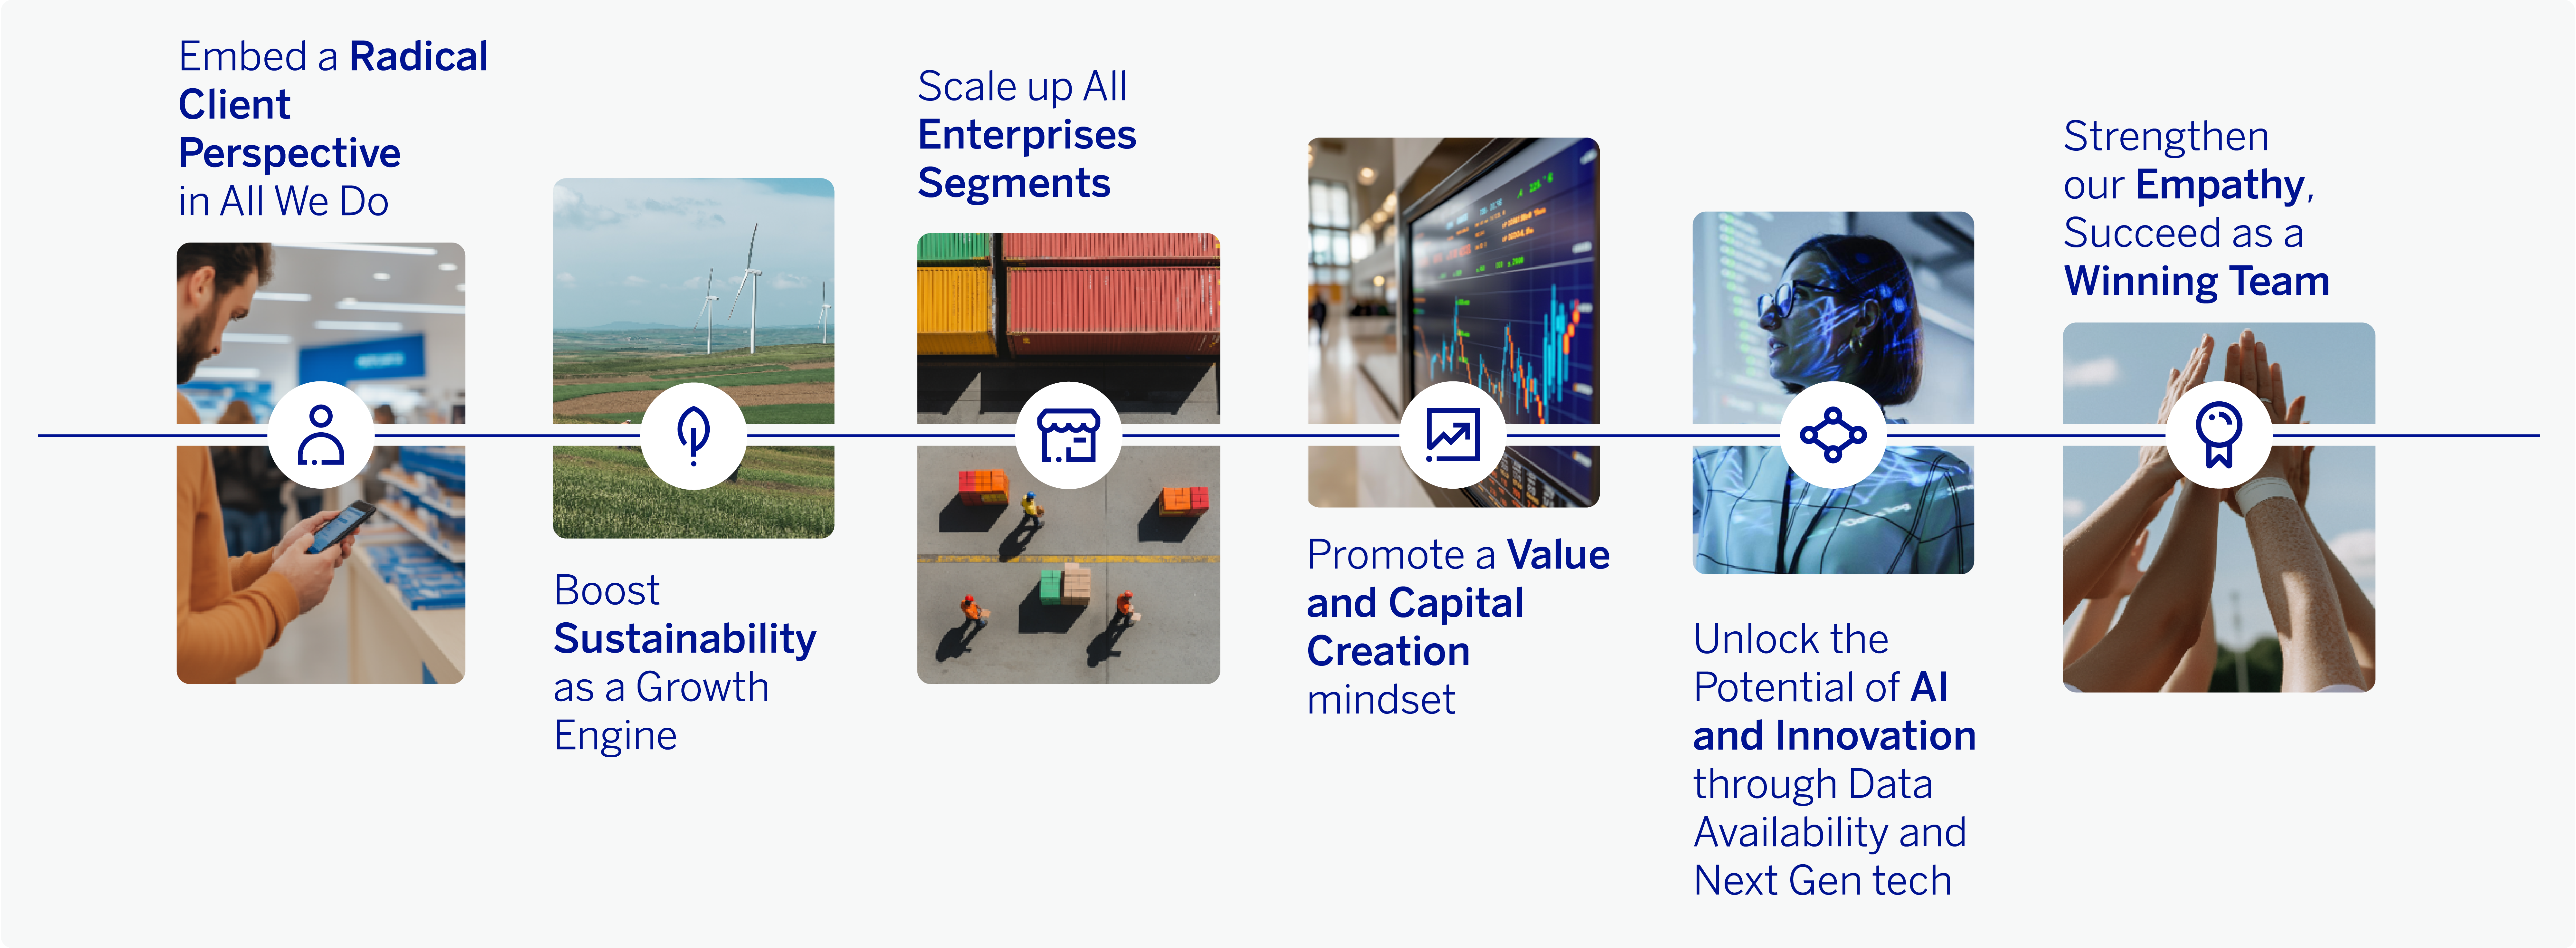
STRATEGIC PRIORITIES
BBVA has established six strategic priorities to advance its strategy. These Priorities form the framework for implementing the 2025-2029 Strategic Plan.
Thanks to the strong execution of the Strategic Plan, BBVA continues to make progress in achieving the financial targets defined for the 2025-2028 period.
BBVA GROUP FINANCIAL KPIS GOALS EVOLUTION
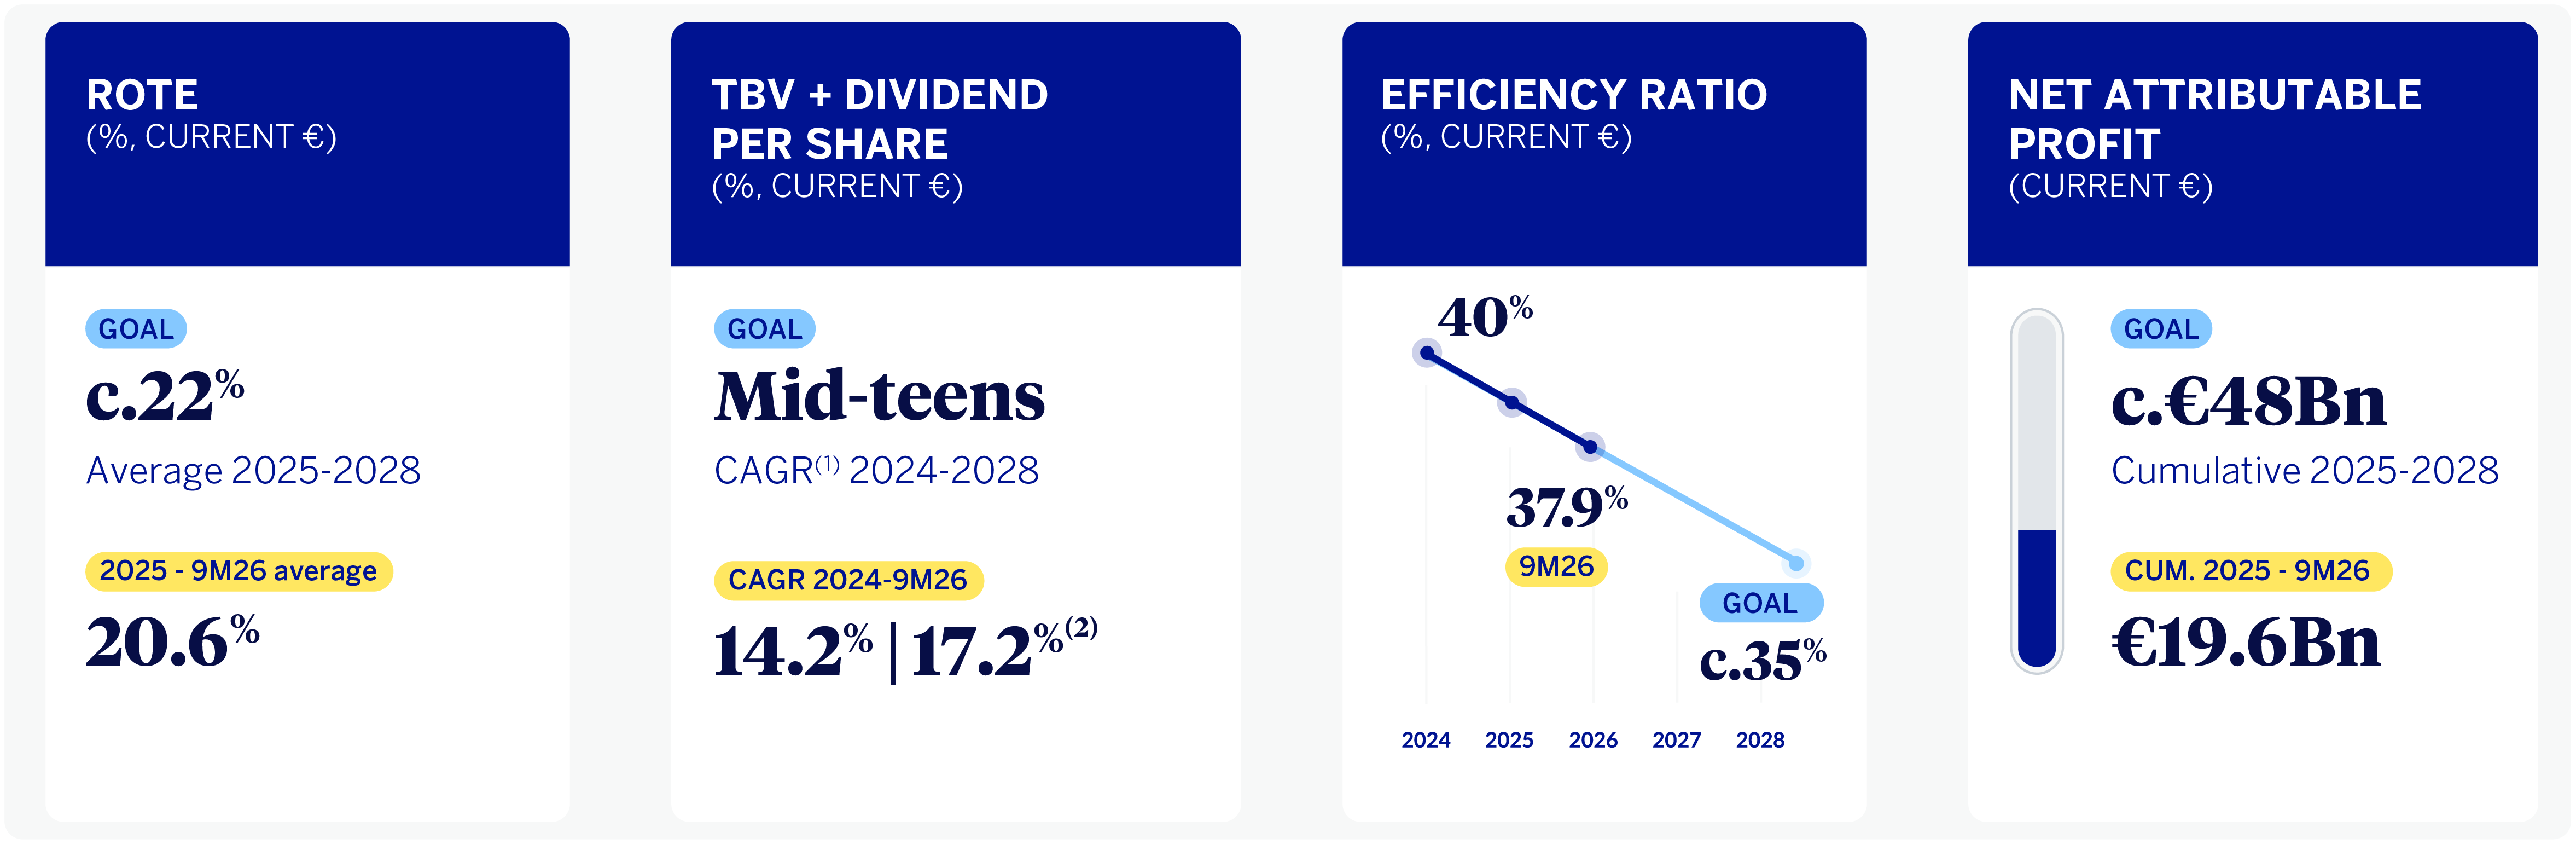
(1) Compound Annual Growth Rate.
(2) Excluding the effect of Share Buybacks.
 Read more
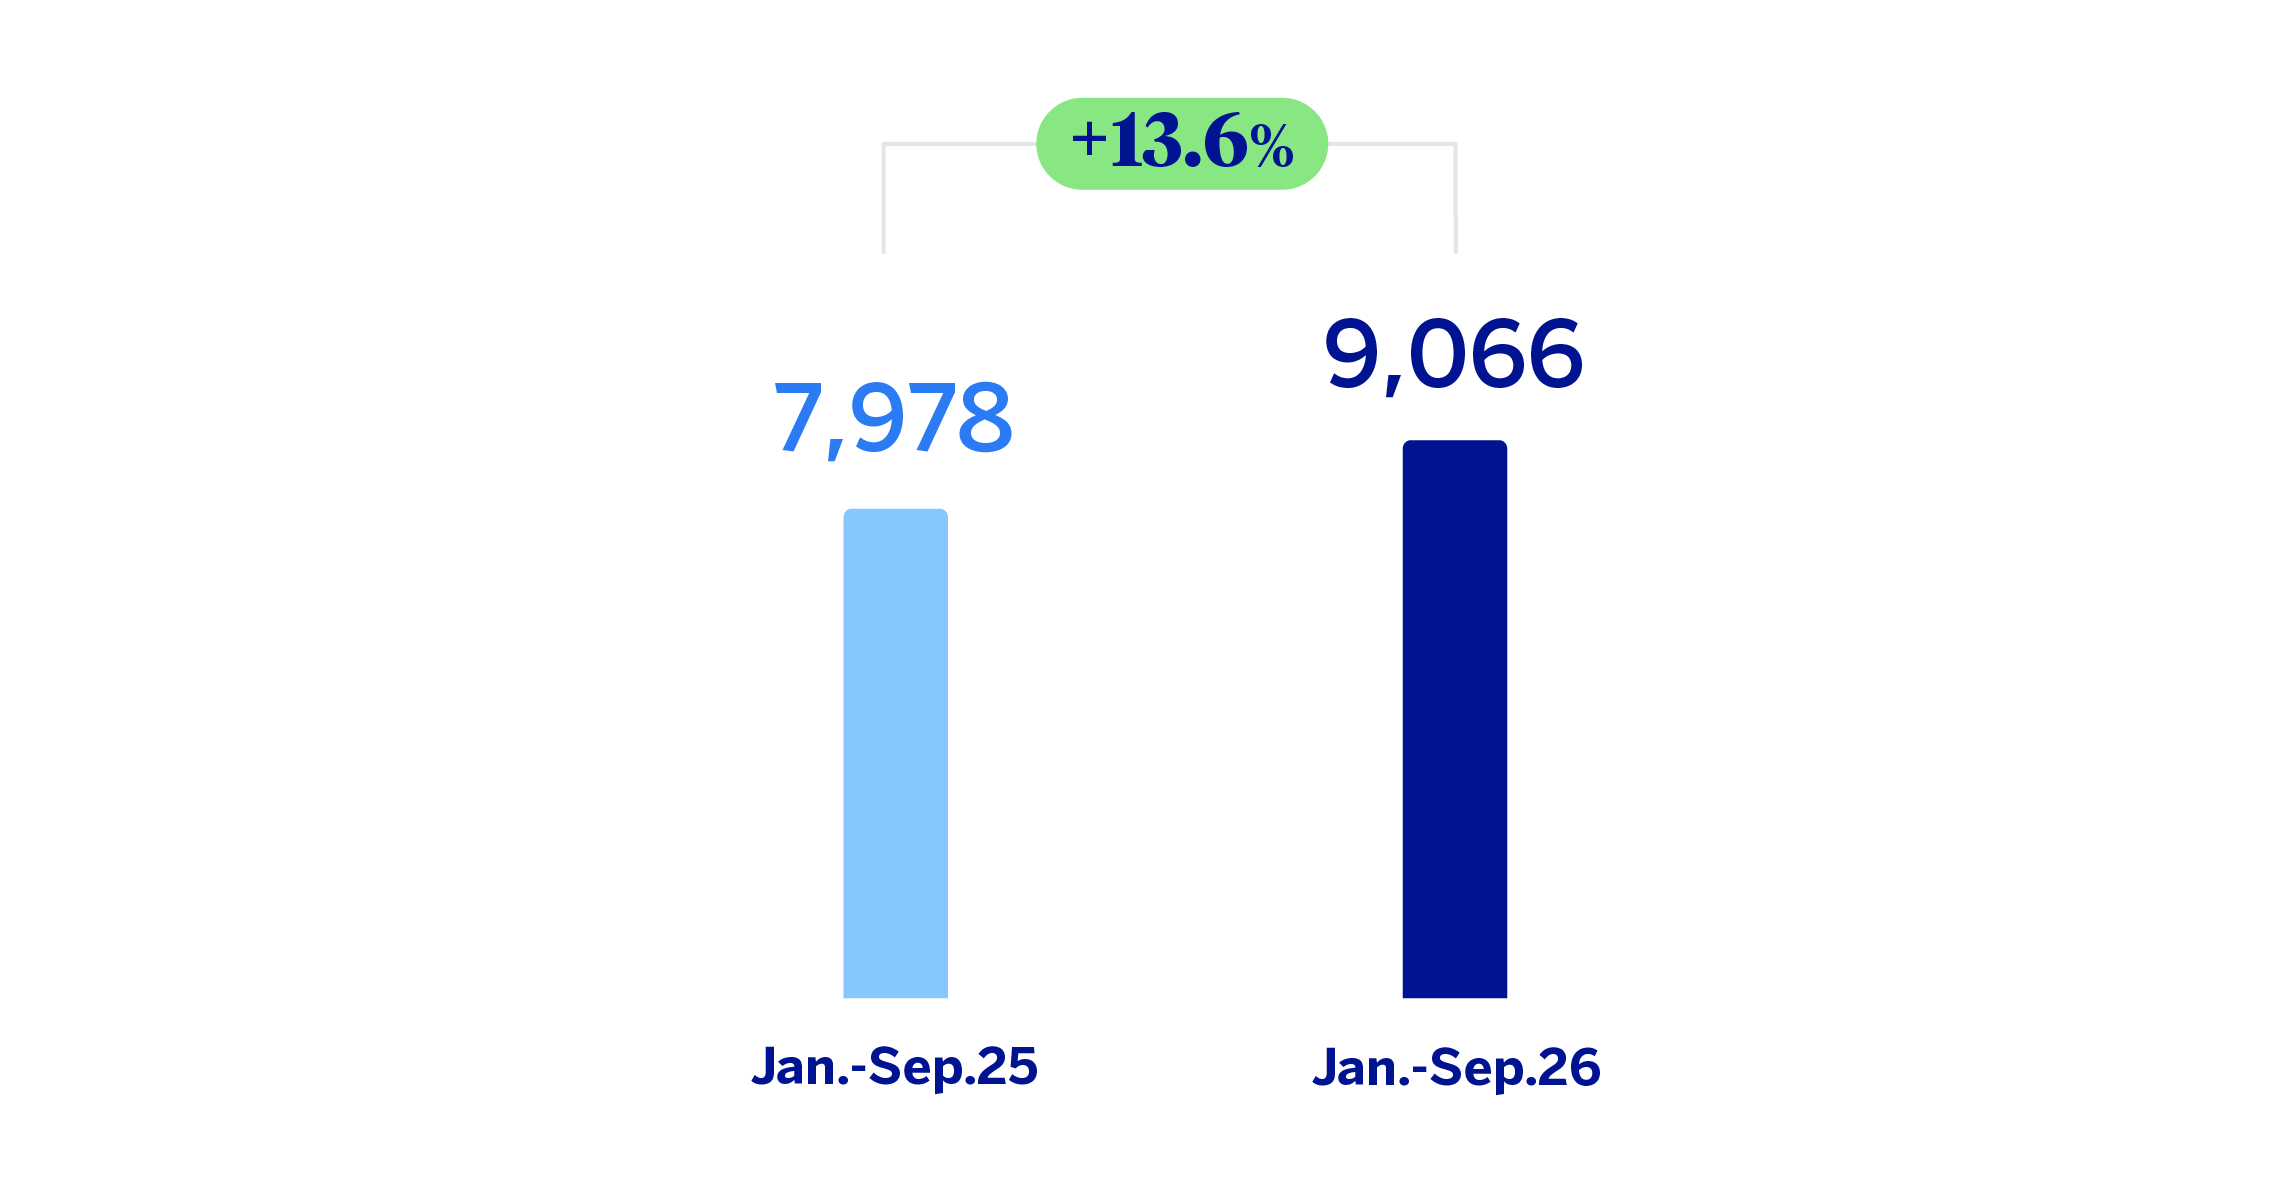
The cumulative net attributable profit of the BBVA Group in the first nine months of 2026 reached €9,066 million, representing an increase of 13.6% over the same period last year supported by the strong performance of recurring revenues from the banking business, that is, net interest income, which increased by 20.8%, and, to a lesser extent, net fees and commissions, which grew at a year-on-year rate of 13.8%, with a particularly strong evolution of payment systems fees.
The solid evolution of net interest income, with a positive performance in all business areas, offset the growth in operating expenses, which increased by 17.4%, and the provisions for impairment on financial assets, which grew by 25.8% compared to the cumulative balances as of September 30, 2025, in a context of lending growth.
NET ATTRIBUTABLE PROFIT (LOSS) (MILLIONS OF EUROS)
 Read more
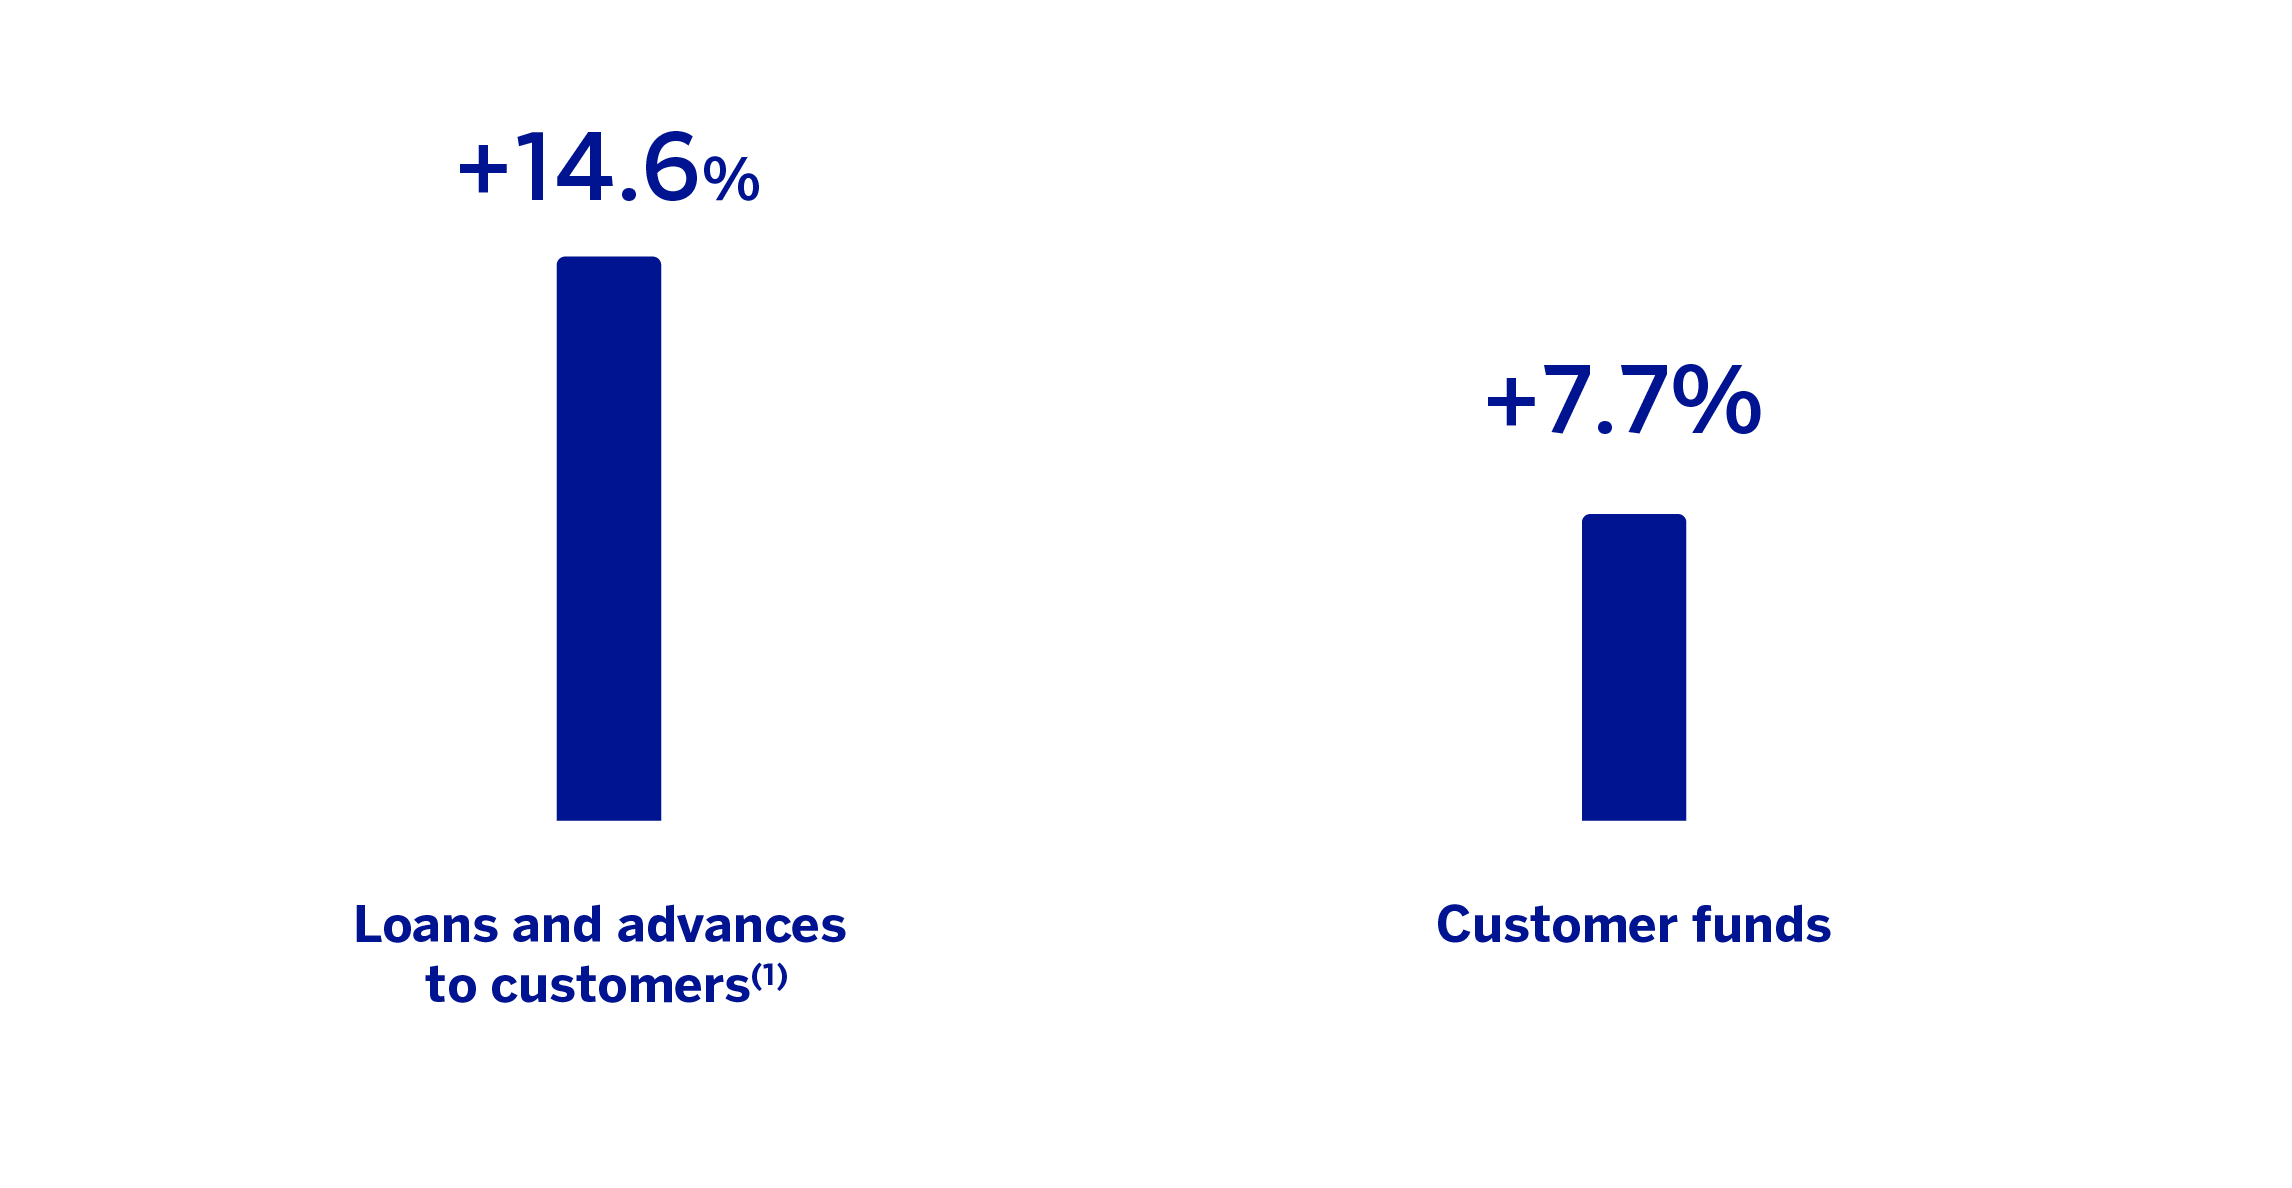
Regarding activity, during the first nine months of 2026, loans and advances to customers increased by 14.6%, driven for another quarter by the dynamism of corporate loans, growing by 19.9% at the Group level. For their part, loans to individuals increased by 6.8%, with a favorable evolution across all products.
Customer funds registered an increase of 7.7% year-to-date, with standout growth in time deposits (+20.7%) and mutual funds (+8.3%) at the Group level.
LOANS AND ADVANCES TO CUSTOMERS AND TOTAL CUSTOMER FUNDS (VARIATION COMPARED TO 31-12-2025)
(1) The growth of performing loans and advances to customers under management (excluding repos) stands at 15.1%.
Read more
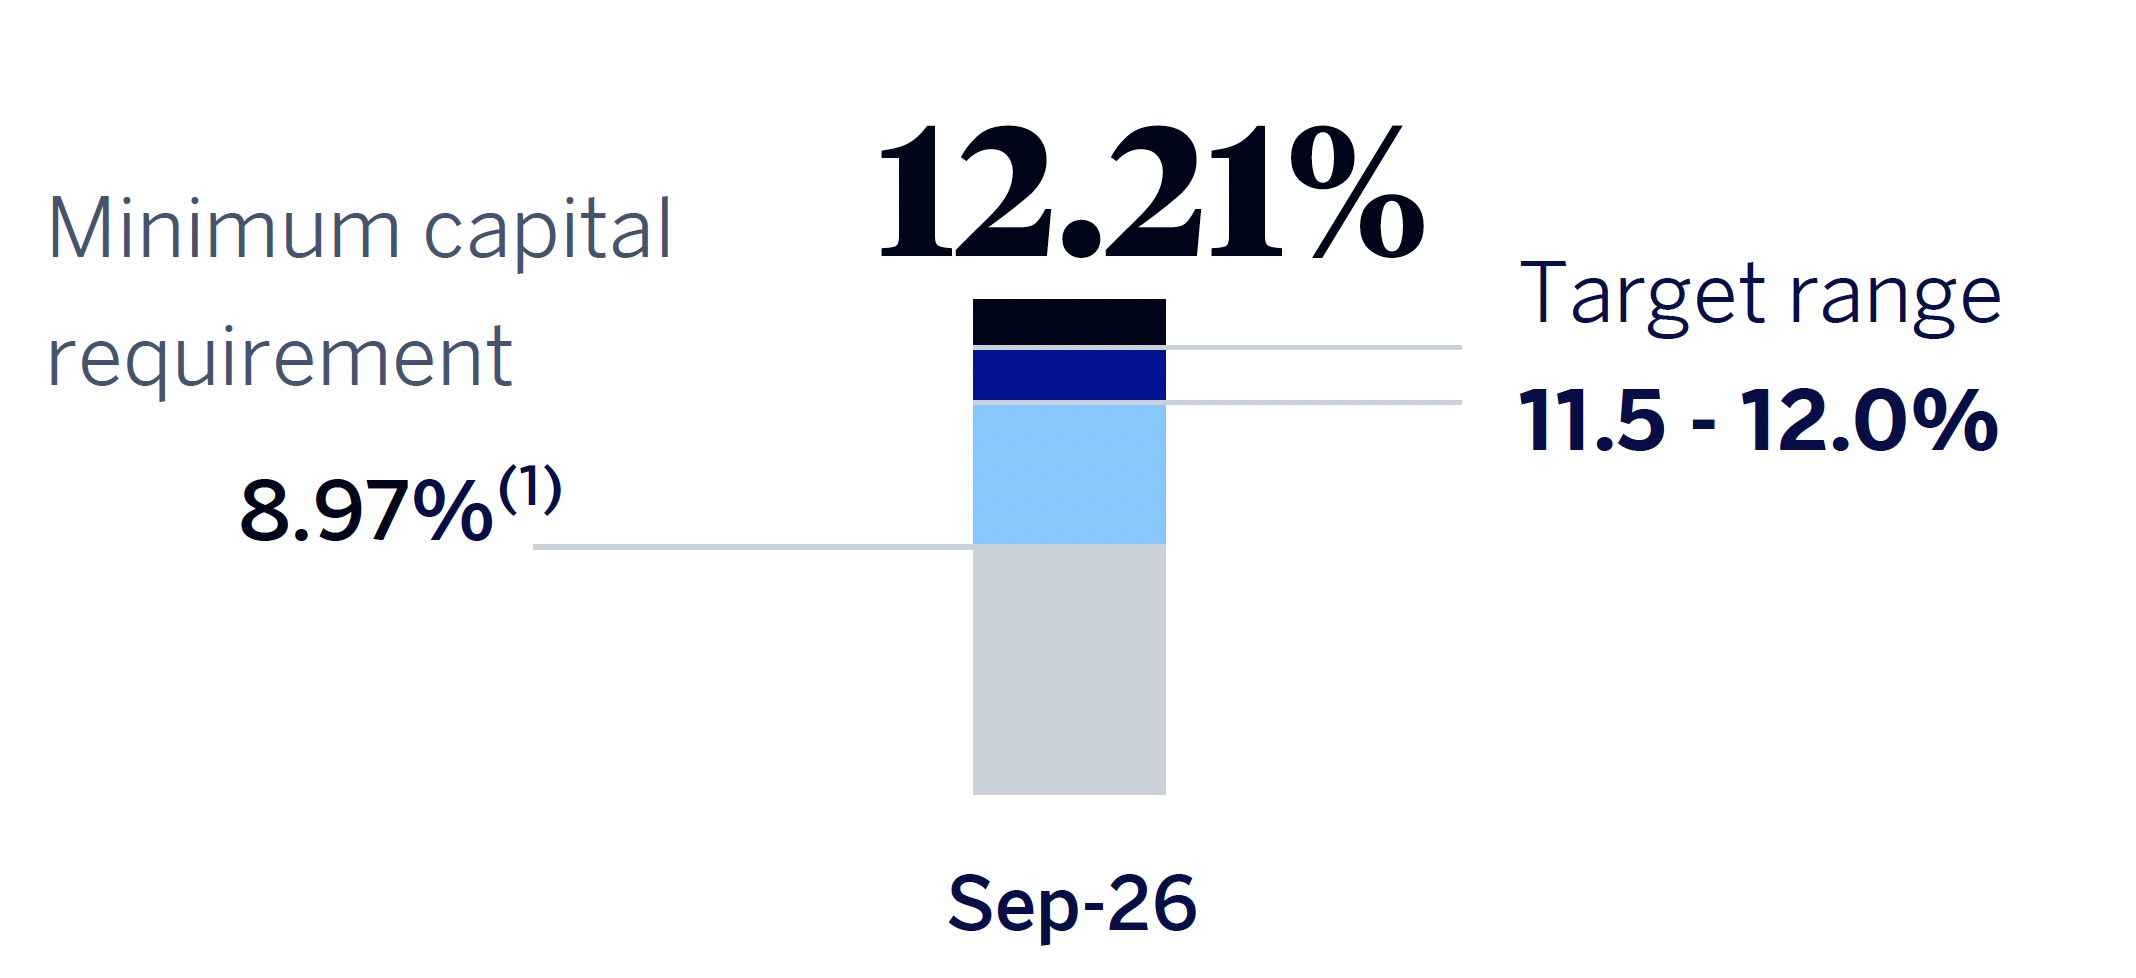
The BBVA Group's CET12 ratio stood at 12.21% as of September 30, 2026, which allows it to maintain a large management buffer over the Group's CET1 requirement as of that date (8.97%3), and is also above the Group's target management range of 11.5% - 12.0% of CET1.
CET1 RATIO
(1) Considering the latest official updates to the countercyclical capital buffer and the systemic risk buffer, applied on the basis of exposure as of June 30, 2026.
2 As of September 30, 2026, there were no differences between fully loaded and phased-in ratios given that the impact associated with the transitional adjustments is nil.
3 Considering the latest official updates to the countercyclical capital buffer and the systemic risk buffer, applied on the basis of exposure as of June 30, 2026.
Read more
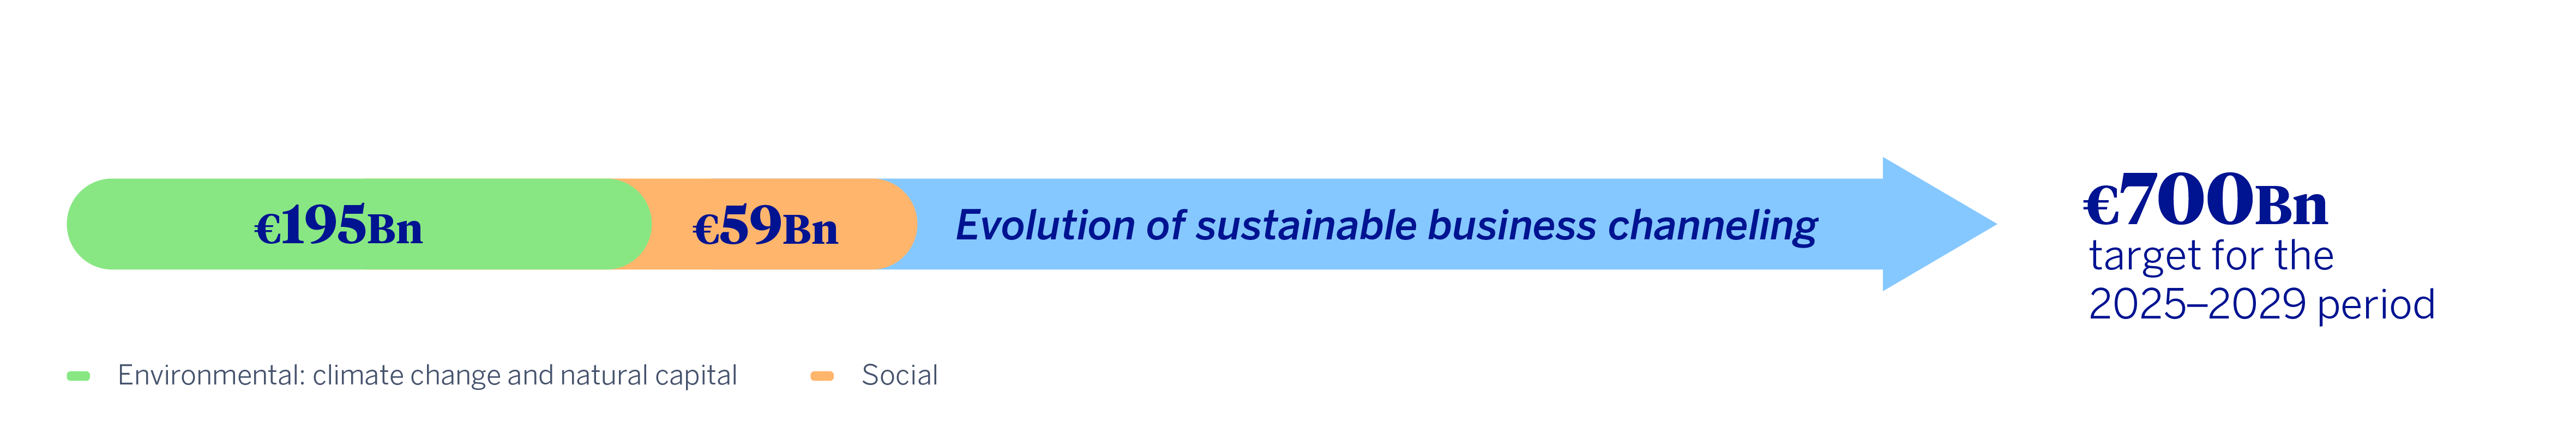
BBVA is driving sustainability as a differential growth engine. Within the framework of its ambitious target of channeling €700 billion into sustainable business for the 2025–2029 period4, the BBVA Group has channeled approximately €120 billion in the first nine months of 2026, bringing the cumulative total to €254 billion since the announcement of this target.
SUSTAINABLE BUSINESS CHANNELING 2025–SEPTEMBER 2026
(1) Sustainable business channeling as of September 30, 2026 also includes transition activities in accordance with the Guide for Sustainable and Transition Business Channeling. The amount corresponding to these activities is not visible in the charts or table due to the scale used, expressed in billions of euros.
SUSTAINABLE BUSINESS CHANNELING 9M26
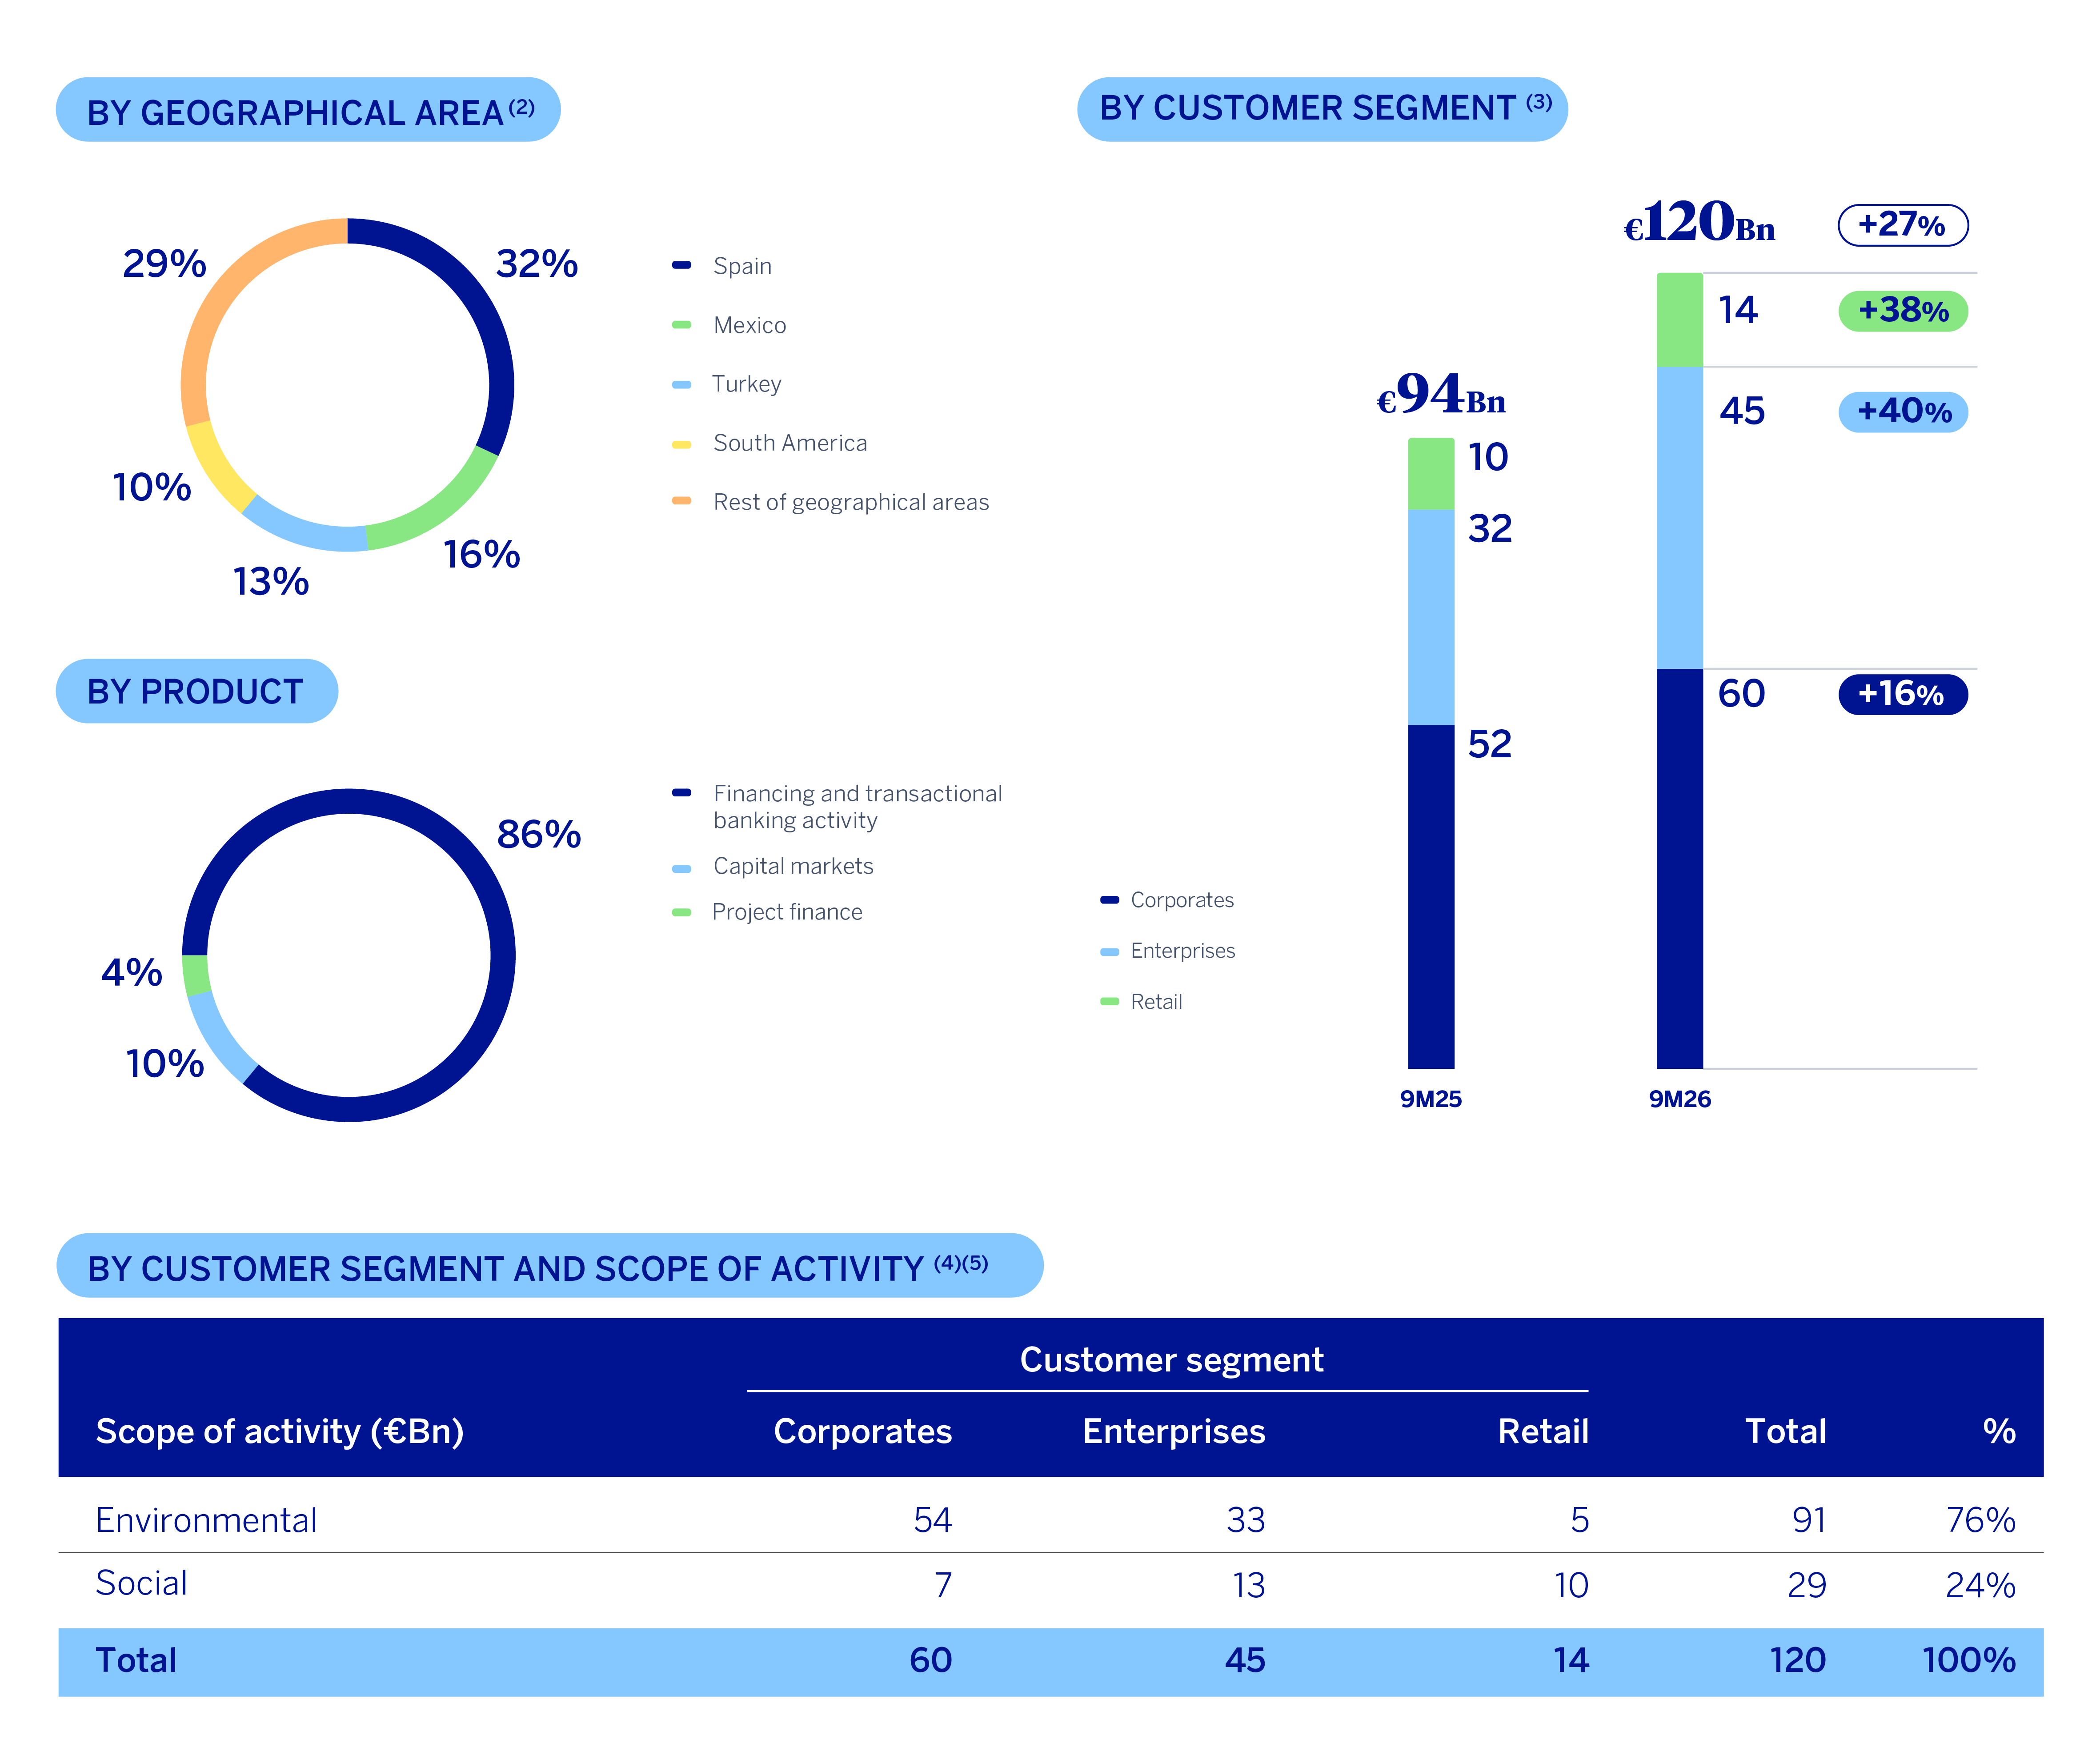
(2) Generally, the criterion used for distributing sustainable business channeling by geographical area is the location of the corresponding operation's registration. However, there are certain exceptions when several geographies are involved in the operation.
(3) At current exchange rates.
(4) In cases where data granularity does not allow for a direct attribution between the scope of activity, internal estimation models based on the best available information are applied. For reporting purposes, the “Environment” category integrates activities related to climate change and natural capital.
(5) The amounts indicated have been rounded; therefore, the amounts or variations shown may not be the exact arithmetic sum of the figures that precede them.
4 The Goal 2029 includes the channeling of financial flows, cumulatively, in relation with activities, clients or products considered to be sustainable, transition and/or linked to sustainability, in accordance with internal standards inspired by existing regulations, market standards such as the Green Bond Principles, the Social Bond Principles, the Climate Transition Bond Guidelines, the Sustainability Linked Bond Principles of the International Capital Markets Association, as well as the Green Loan Principles, Social Loan Principles, Guide to Transition Loans and the Sustainability Linked Loan Principles of the Loan Market Association, and best market practices. The foregoing is understood without prejudice to the fact that said channeling, both at an initial stage or at a later time, may not be registered on the balance sheet. The products and eligibility and accounting criteria are described in the BBVA Sustainable and Transition Business Channeling Guide available on the BBVA Group's shareholders and investors website.
Read more
In the first nine months of 2026, the BBVA Group has continued to make progress in executing its 2025-2029 Strategic Plan, with the ambition of leading the banking of the future. The objective is to radically embed a customer-centric perspective, as well as to drive and strengthen the Group's commitment to growth and value creation.
Artificial intelligence is a key lever for accelerating the Group's transformation and amplifying the impact of all strategic priorities. In this regard, BBVA is driving its cross-cutting integration across the entire organization through The Eight, the artificial intelligence transformation agenda, to evolve toward a more personalized and proactive relationship with customers, redesign and streamline processes, and enhance employee capabilities. Furthermore, BBVA is developing The Frame, a common operating model that enables scaling the deployment of artificial intelligence solutions and agents safely and efficiently.
STRATEGIC PRIORITIES
BBVA has established six strategic priorities to advance its strategy. These Priorities form the framework for implementing the 2025-2029 Strategic Plan.
Thanks to the strong execution of the Strategic Plan, BBVA continues to make progress in achieving the financial targets defined for the 2025-2028 period.
BBVA GROUP FINANCIAL KPIS GOALS EVOLUTION
(1) Compound Annual Growth Rate.
(2) Excluding the effect of Share Buybacks.
Read more
The cumulative net attributable profit of the BBVA Group in the first nine months of 2026 reached €9,066 million, representing an increase of 13.6% over the same period last year supported by the strong performance of recurring revenues from the banking business, that is, net interest income, which increased by 20.8%, and, to a lesser extent, net fees and commissions, which grew at a year-on-year rate of 13.8%, with a particularly strong evolution of payment systems fees.
The solid evolution of net interest income, with a positive performance in all business areas, offset the growth in operating expenses, which increased by 17.4%, and the provisions for impairment on financial assets, which grew by 25.8% compared to the cumulative balances as of September 30, 2025, in a context of lending growth.
NET ATTRIBUTABLE PROFIT (LOSS) (MILLIONS OF EUROS)
Read more
Regarding activity, during the first nine months of 2026, loans and advances to customers increased by 14.6%, driven for another quarter by the dynamism of corporate loans, growing by 19.9% at the Group level. For their part, loans to individuals increased by 6.8%, with a favorable evolution across all products.
Customer funds registered an increase of 7.7% year-to-date, with standout growth in time deposits (+20.7%) and mutual funds (+8.3%) at the Group level.
LOANS AND ADVANCES TO CUSTOMERS AND TOTAL CUSTOMER FUNDS (VARIATION COMPARED TO 31-12-2025)
(1) The growth of performing loans and advances to customers under management (excluding repos) stands at 15.1%.
Read more
The BBVA Group's CET12 ratio stood at 12.21% as of September 30, 2026, which allows it to maintain a large management buffer over the Group's CET1 requirement as of that date (8.97%3), and is also above the Group's target management range of 11.5% - 12.0% of CET1.
CET1 RATIO
(1) Considering the latest official updates to the countercyclical capital buffer and the systemic risk buffer, applied on the basis of exposure as of June 30, 2026.
2 As of September 30, 2026, there were no differences between fully loaded and phased-in ratios given that the impact associated with the transitional adjustments is nil.
3 Considering the latest official updates to the countercyclical capital buffer and the systemic risk buffer, applied on the basis of exposure as of June 30, 2026.
Read more
BBVA is driving sustainability as a differential growth engine. Within the framework of its ambitious target of channeling €700 billion into sustainable business for the 2025–2029 period4, the BBVA Group has channeled approximately €120 billion in the first nine months of 2026, bringing the cumulative total to €254 billion since the announcement of this target.
SUSTAINABLE BUSINESS CHANNELING 2025–SEPTEMBER 2026
(1) Sustainable business channeling as of September 30, 2026 also includes transition activities in accordance with the Guide for Sustainable and Transition Business Channeling. The amount corresponding to these activities is not visible in the charts or table due to the scale used, expressed in billions of euros.
SUSTAINABLE BUSINESS CHANNELING 9M26
(2) Generally, the criterion used for distributing sustainable business channeling by geographical area is the location of the corresponding operation's registration. However, there are certain exceptions when several geographies are involved in the operation.
(3) At current exchange rates.
(4) In cases where data granularity does not allow for a direct attribution between the scope of activity, internal estimation models based on the best available information are applied. For reporting purposes, the “Environment” category integrates activities related to climate change and natural capital.
(5) The amounts indicated have been rounded; therefore, the amounts or variations shown may not be the exact arithmetic sum of the figures that precede them.
4 The Goal 2029 includes the channeling of financial flows, cumulatively, in relation with activities, clients or products considered to be sustainable, transition and/or linked to sustainability, in accordance with internal standards inspired by existing regulations, market standards such as the Green Bond Principles, the Social Bond Principles, the Climate Transition Bond Guidelines, the Sustainability Linked Bond Principles of the International Capital Markets Association, as well as the Green Loan Principles, Social Loan Principles, Guide to Transition Loans and the Sustainability Linked Loan Principles of the Loan Market Association, and best market practices. The foregoing is understood without prejudice to the fact that said channeling, both at an initial stage or at a later time, may not be registered on the balance sheet. The products and eligibility and accounting criteria are described in the BBVA Sustainable and Transition Business Channeling Guide available on the BBVA Group's shareholders and investors website.
Read more
Business Areas
Click on each area to learn more
Spain
Spain
HIGHLIGHTS FOR THE PERIOD
|
RESULTS
| |
| Net interest income | Gross income |
| 5,055 | 7,601 |
| +3.4% (2) | +2.2% (2) |
| Operating income | Net atributable profit |
| 4,999 | 3,106 |
| -0.4%(2) | -0.2% (2) |
ACTIVITY (1)
|
|
| Variation compared 31-12-25. Balances as of 30-09-26. |
|
| Performing loans and advances to customers under management | Customer funds under management |
| +4.7% | +3.5% |
RISKS |
| NPL coverage ratio |
| 67% | 72% |
| NPL ratio |
| 3.0% | 2.9% |
| Cost of risk |
| 0.34% | 0.33% |
(2) Year-on-year changes.
Mexico
Mexico
HIGHLIGHTS FOR THE PERIOD
|
RESULTS
| |
| Net interest income | Gross income |
| 9,826 | 13,026 |
| +8.5% (2) | +8.5% (2) |
| Operating income | Net atributable profit |
| 9,033 | 4,522 |
| +8.4% (2) | +8.4% (2) |
ACTIVITY (1)
|
|
| Variation compared 31-12-25. Balances as of 30-09-26. |
|
| Performing loans and advances to customers under management | Customer funds under management |
| +7.9% | +5.4% |
RISKS |
| NPL coverage ratio |
| 124% | 111% |
| NPL ratio |
| 2.7% | 2.9% |
| Cost of risk |
| 3.31% | 3.19% |
(2) Year-on-year changes.
Turkey
Turkey
HIGHLIGHTS FOR THE PERIOD
|
RESULTS
| |
| Net interest income | Gross income |
| 3,357 | 5,085 |
| +74.8% (2) | +55.1% (2) |
| Operating income | Net atributable profit |
| 3,038 | 789 |
| +69.4% (2) | +60.1% (2) |
ACTIVITY (1)
|
|
| Variation compared 31-12-25. Balances as of 30-09-26. |
|
| Performing loans and advances to customers under management | Customer funds under management |
| +24.5% | +17.3% |
RISKS |
| NPL coverage ratio |
| 76% | 76% |
| NPL ratio |
| 3.9% | 4.2% |
| Cost of risk |
| 1.94% | 2.55% |
(2) Year-on-year changes.
South America
South America
HIGHLIGHTS FOR THE PERIOD
|
RESULTS
| |
| Net interest income | Gross income |
| 4,518 | 5,065 |
| +26.1% (2) | +24.8% (2) |
| Operating income | Net atributable profit |
| 2,964 | 821 |
| +31.0% (2) | +41.1% (2) |
ACTIVITY (1)
|
|
| Variation compared 31-12-25. Balances as of 30-09-26. |
|
| Performing loans and advances to customers under management | Customer funds under management |
| +10.3% | +13.3% |
RISKS |
| NPL coverage ratio |
| 92% | 89% |
| NPL ratio |
| 4.0% | 3.8% |
| Cost of risk |
| 2.50% | 2.72% |
(2) Year-on-year changes.
Rest of business
Rest of business
HIGHLIGHTS FOR THE PERIOD
|
RESULTS
| |
| Net interest income | Gross income |
| 833 | 1,873 |
| +40.2% (2) | +43.5% (2) |
| Operating income | Net atributable profit |
| 1,087 | 801 |
| +53.4% (2) | +58.5% (2) |
ACTIVITY (1)
|
|
| Variation compared 31-12-25. Balances as of 30-09-26. |
|
| Performing loans and advances to customers under management | Customer funds under management |
| +47.8% | +15.2% |
RISKS |
| NPL coverage ratio |
| 172% | 84% |
| NPL ratio |
| 0.2% | 0.3% |
| Cost of risk |
| 0.15% | 0.11% |
(2) Year-on-year changes.
* Gross income.
(1) At constant exchange rate.
(2) At constant exchange rates.
Regarding the cumulative results as of the end of September 2026 by business areas, excluding exchange rate fluctuations unless otherwise specified, it is worth mentioning:
Spain generated a net attributable profit of €3,106 million in the first nine months of 2026, which is in line with that achieved in the same period of 2025 favored by the good performance of net interest income.
Mexico achieved a net attributable profit of €4,522 million, which represents a year-on-year growth of 8.4%, explained mainly by the favorable evolution of net interest income, supported by robust lending activity growth and driven also by the rest of components of gross income.
Turkey reached a net attributable profit of €789 million, which compares very favorably with the result achieved in the same period of the previous year, mainly as a result of the strong performance of net interest income.
South America generated a net attributable profit of €821 million, which represents a year-on-year growth of 42.1% at current exchange rates, favored by the evolution of net interest income.
Rest of Business achieved a net attributable profit of €801 million, 58.5% higher than in the same period of the previous year, favored by the evolution of the recurring revenues and the NTI.
The Corporate Center recorded in the first nine months of 2026 a net attributable loss of €-974 million which represents a worsening compared to the same period of the previous year, associated with higher personnel expenses.
Lastly, and for a better understanding of the Group's activity and results, supplementary information is provided on the wholesale business, Corporate & Investment Banking (CIB), carried out by BBVA in the countries where it operates. CIB generated a net attributable profit of €3,082 million in the first nine months of 20265. This result represents, excluding the impact of currency fluctuations, a 19.0% increase over the previous year, which once again reflects the strength of the Group's wholesale businesses, with the aim of offering a value proposition focused on the needs of its customers.
NET ATTRIBUTABLE PROFIT BREAKDOWN (1)
(PERCENTAGE. JAN.-SEP.26)
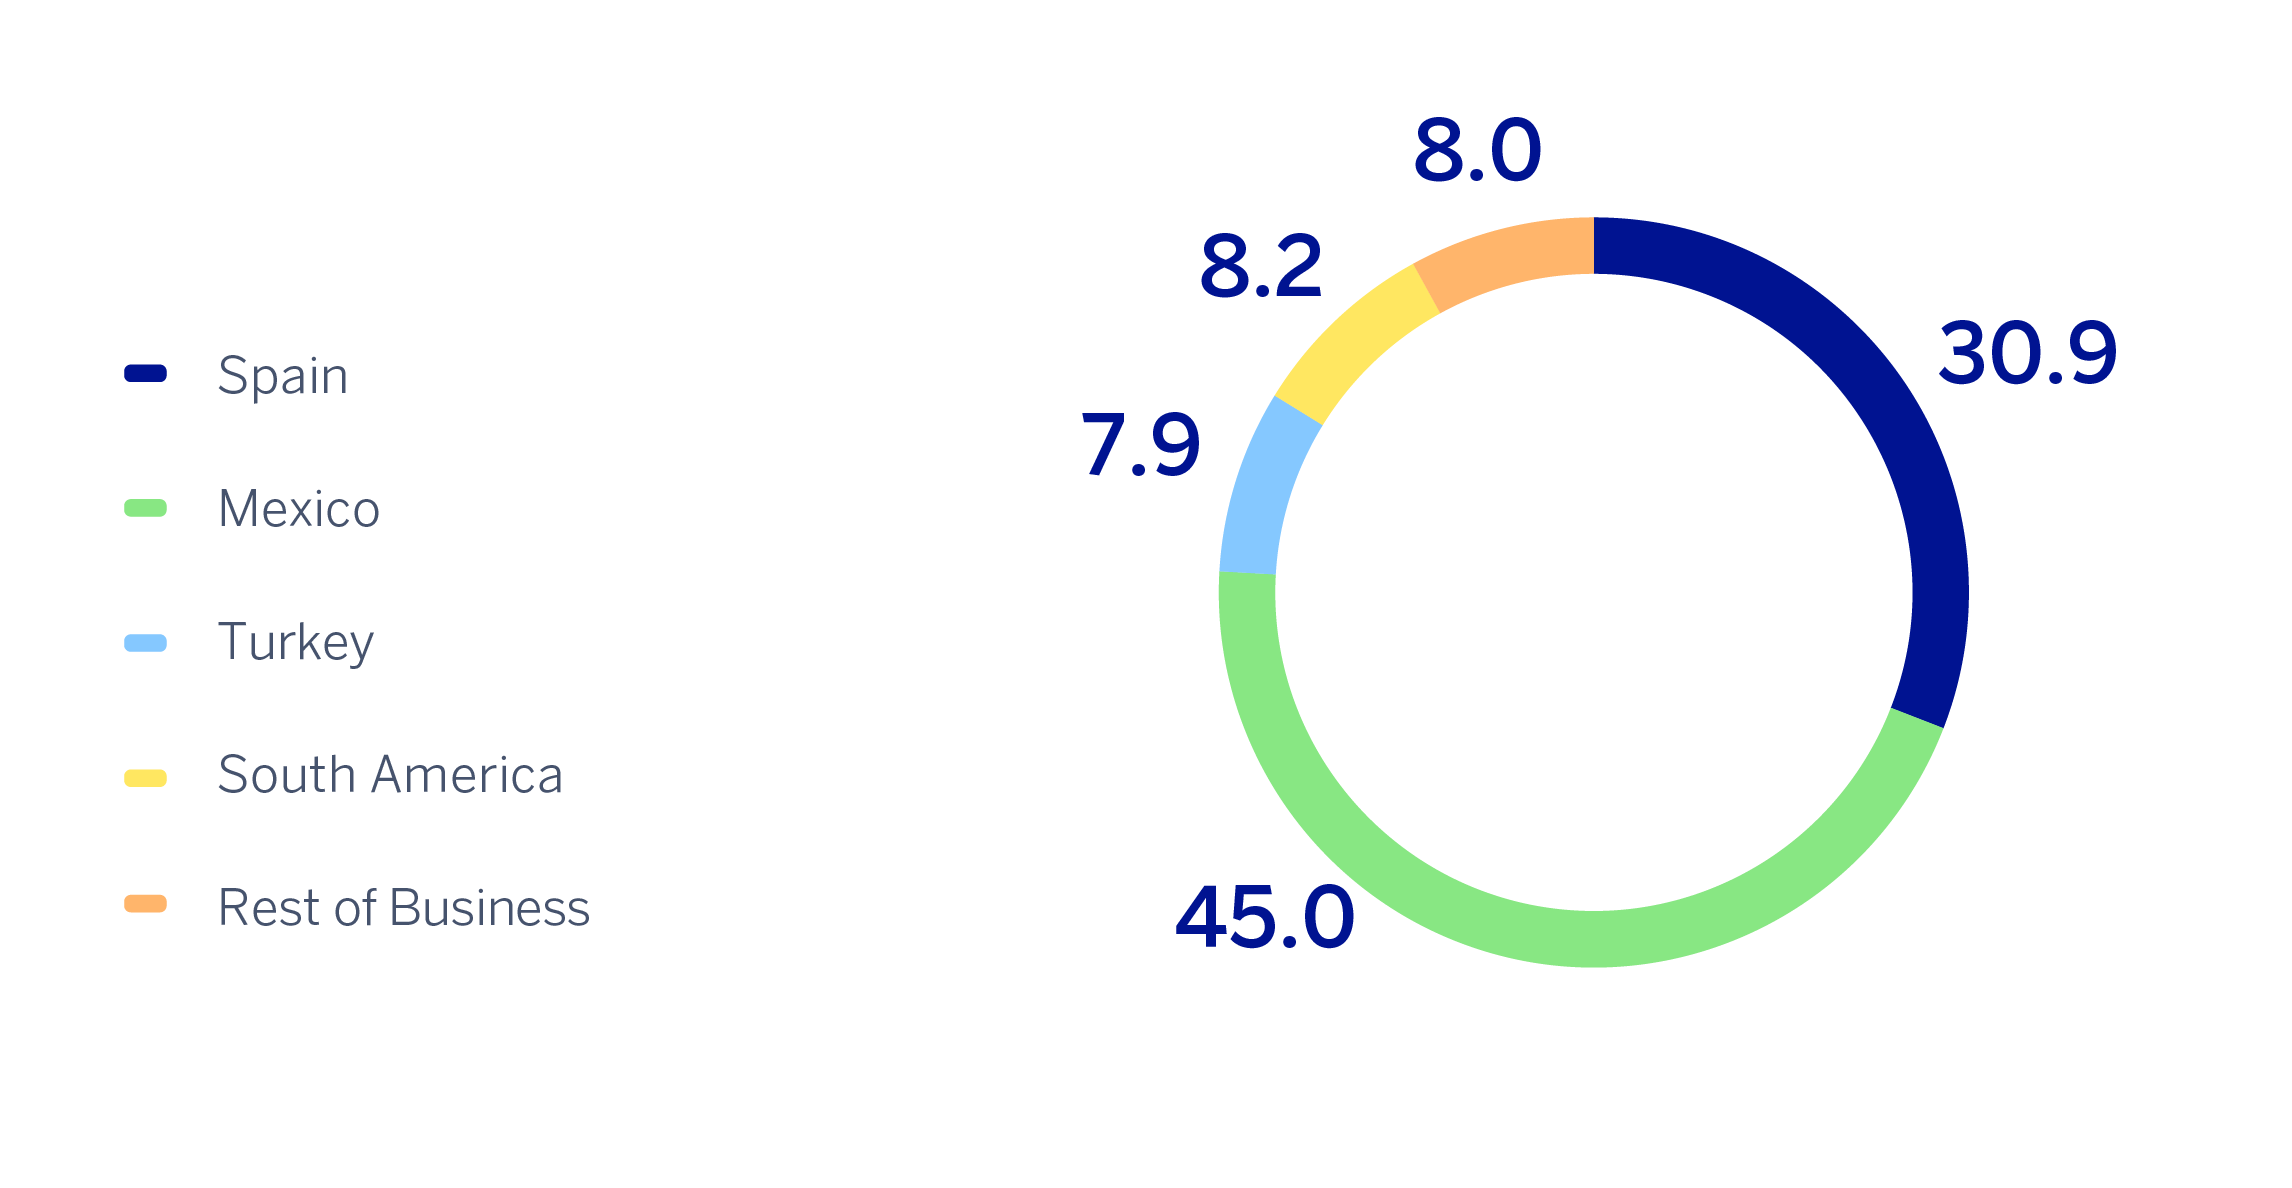
(1) Excludes the Corporate Center.
5 The additional pro forma information from CIB excludes the application of hyperinflation accounting and the Group's wholesale business in Venezuela.
Read legal disclaimer of this report.
News
Contact
 Shareholder attention line
912 24 98 21
 Subscription service
 Shareholder Office
 Contact email